Last Updated on December 29, 2021 at 5:26 pm
The shut down of six Franklin debt mutual fund have shaken mutual fund investors with “what if the same happens to my funds?” fears. Many are exploring the pros and cons of invest in gilt mutual funds (investing in govt bonds). Here is what investors need to know before investing in gilt mutual funds.
At the outset, let us clarify that credit risk where one or more bonds in the portfolio get downgraded to default with a vertical drop in the NAV is significantly scarier and devastating to the investor psyche than interest rate risk where the NAV can rise up or fall significantly due to market supply and demand forces.
Credit risk is like walking through a house of horrors in an amusement park to be scared out of our boots if we turn a wrong corner – we do not know where the next monster will pop out. Interest rate risk is like walking through a slushy ground or a wet and slippery bathroom. We can see the risk clearly but can get hurt if we do not have a strategy or invest with incorrect assumptions.
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
You can buy a gilt (govt bond) directly from the primary or secondary market. This practically carries no risk, unless the govt runs out of money and defaults on its debt. A few months ago, that sentence would have been reassuring. Now, in the middle of a lockdown, it assumes a whole new meaning. We shall proceed with the assumption that the likelihood of govt default is low.
You would receive interest payouts every six months until the bond matures and the principal would be returned. This is safer than a bank fixed deposit. The only catch is the interest is taxable as per slab.
If you were to buy a debt mutual fund exclusively in gilts, everything changes. The fund manager buys and sells gilts (assuming only gilts, which is not true!) depending on the fund in- and out-flows and market conditions. This will result in capital gains or losses.
Most importantly, even if a gilt fund has a single govt bond (with some cash to handle AUM changes), its NAV will move up and down as per the market price of the bond. So an investor who moves in and out of the fund at different times will experience notional or real gains or losses.
This is the big difference between holding a gilt directly and buying a gilt mutual fund. The market value of a directly purchased gilt is irrelevant to the investor as long as they choose to hold the bond.
Now for the bad news: There are currently no debt funds that invest exclusively in short-term gilts. These carry no credit risk and minimal interest rate risk (relatively). The SEBI regulations took care of that – Death of a good mutual fund: DSP BlackRock Treasury Bill Fund
When I say exclusively, I am referring to wording in the scheme document that says, “we will only invest in gilts”, not the predatory fund emails that proclaim safety of their portfolios.
This means, considering the volatility of the NAV, existing gilt mutual funds cannot be used for short-term goals (instead of an FD or RD). The medium and long -term gilts are subject to fund manager risks.
Normally, a longer-term govt bond is expected to carry a higher interest rate than short-term bonds because of higher risk (the int rate when the longer bond matures could be considerably lower aka reinvestment risk).
Due to changes in economic conditions, all bonds could carry similar rates or short-term bonds could be more rewarding. Read more: The Bond Yield Curve as an indicator of what’s going on with the economy. A few years ago (July 2013), RBI increased rates by 2% overnight to stop the Rupee from falling and liquid fund investors enjoyed 9% returns (and assumed this would be the future!). Now, we see them go, “is my liquid fund safe?”.
Even if they exclusively invest in gilts (they don’t have to, thanks to SEBI), if the fund manager shuffles between long-term and short-term gilts. If short-term rates are lower, the manager could some bonds in the portfolio for a profit and invest in long-term bonds or vice-versa. If they get it wrong (and they do), the investor will suffer.
The alternative is the constant maturity 10-year gilt fund. See for example SBI Magnum Constant Maturity Fund: A Debt Fund With Low Credit Risk for long term goals!
The catch is (there is always one!) when interest rates drop, these funds can give spectacular gains. How is that a catch? Because when interest rates increase (they have to!), they can lead to spectacular losses.
I had recently published Ten years of investing in the NPS: Performance report. My NPS portfolio (40% of my retirement corpus, now 50% after the crash!) consists of three gilt funds (not by choice) and they have given both wild profits and wild losses.
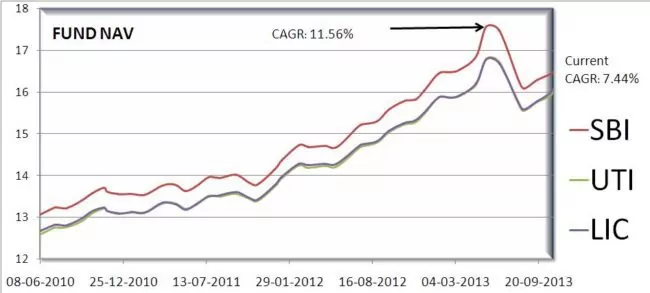
My NPS CAGR just before the fall was 11% ish and overnight it became 6-ish% recovering over the next few months. When this occurred, PFRDA realised “aisa bhi hota hai! What if this happens just before the person retires?!”, and introduced staggered withdrawals.
This is the cumulative gain (as of March 18th 2020). Notice the losses, the gains and the periods of no returns.

Unless you are mentally prepared for such a journey do not invest in any kind of gilt mutual funds. In the current climate, fear may drive investors to these funds, but just a few years ago, they complained about falling or negative gilt fund returns: Why are Long Term Gilt Funds Falling?
I have recently pointed out in a series of articles that the volatility of long-term gilt funds can be effectively exploited to reduce overall portfolio risk by combining them with equity. This, however, requires near-impossible investor traits like conviction, focus, discipline and portfolio-level analysis.
- Will Benjamin Graham’s 50% Stocks 50% Bonds strategy work for India?
- This portfolio works in all market conditions! Will you invest?
- This is how buying US stocks will affect your portfolio
- Will including gold in my portfolio help?
Rolling returns of long-term gilt indices
To appreciate “what kind of returns one can expect from gilt funds?” – a wrong question to ask – let us look at how returns can fluctuate in two gilt indices: The CRISIL 10Y gilt index and the I-BEX I-SEC gilt index which is a composite index (with a hard to locate average portfolio maturity).
Please the spread in returns possible. Taxes and exit loads are not accounted for.
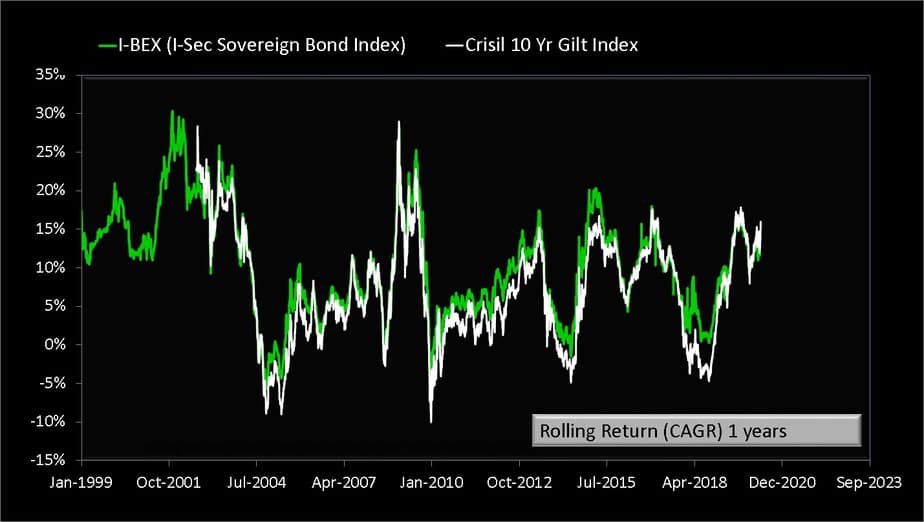
Notice 1-year returns have been frequently negative.
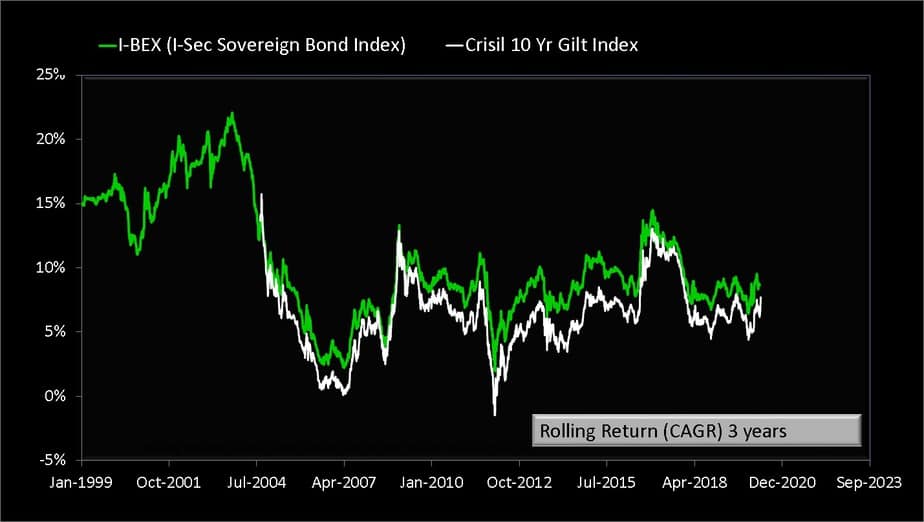
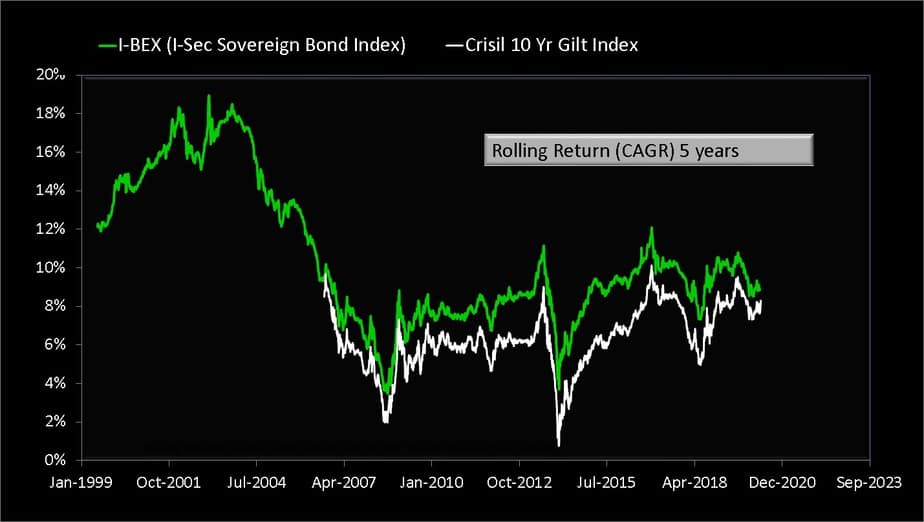
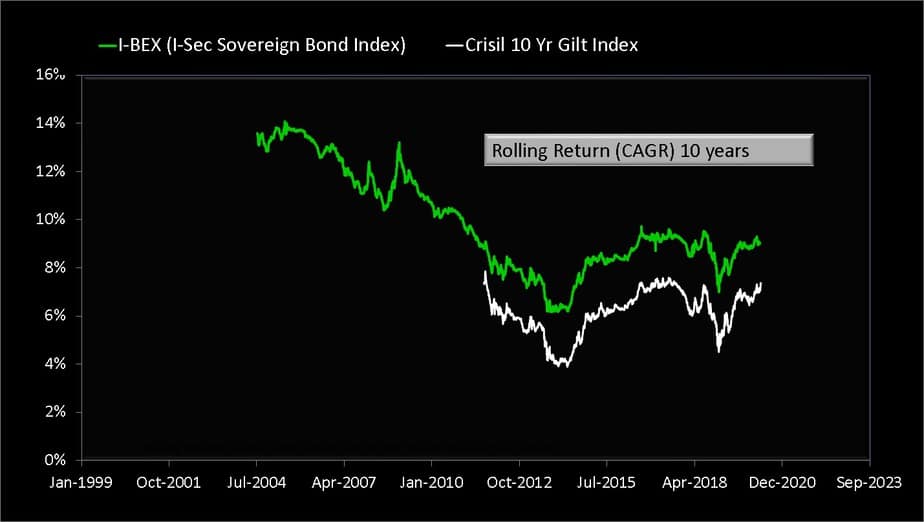
An unmanaged investment in gilts can produce just about any return. Investors who wish to use them for long term goals must take care of the following:
- Invest more or rebalance (if possible) into gilt funds when they are negative.
- Appreciate gilts and equity need not move oppositely
- Unlike the normal increase of debt allocation with time, they will have to shift the corpus to less volatile fixed income because bonds can crash like stocks.
Gilt mutual funds are only for those who can appreciate risks and hold firm. Gilt bonds can be used for income generation, but are subject to reinvestment risks.