Last Updated on April 23, 2023 at 1:02 pm
If diversification is about ‘not keeping all eggs in the same basket‘, rebalancing is realising that ‘what goes up, will come down‘. Yes, investment portfolio management is all about simple common sense. In this post, I would like to revisit the topic of portfolio rebalancing and discuss what it is, why do it is, and simple ways to do it.
I would like to thank Sunny Sachdeva for suggesting this topic, forcing me to reframe posts on rebalancing first published in May-June 2013 (links below). This is important for two reasons, (a) I have learnt a lot more in these three years and (b) I can probably write a lot better now than earlier.
What is portfolio rebalancing?
First, let us get a few things out of the way:
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
Rebalancing is redeeming from one asset class and reinvesting immediately in another. Rebalancing is not profit booking.
Rebalancing is not timing the market.
Rebalancing is not a method to get higher returns.
Yesterday we looked at how to build a diversified portfolio. The primary idea behind this and behind any successful investment strategy is asset allocation (% exposure to equity, fixed income, gold etc.).
There are many types of asset allocation strategies (more on that later), but I would like to stick to a simple plan: 60% equity and 40% fixed income.
However, as we keep investing and as the value of these asset classes increases or decreases, the asset allocation will deviate from the target allocation.
Rebalancing refers to the method by which we reset the asset allocation. There are many ways to do this too. Will discuss a simple method here. Other examples can be seen in the posts below.
We start with a portfolio with X% equity allocation and Y% fixed income. At the end of each year, the asset allocation is reset back to X:Y (will become clear with the example below).
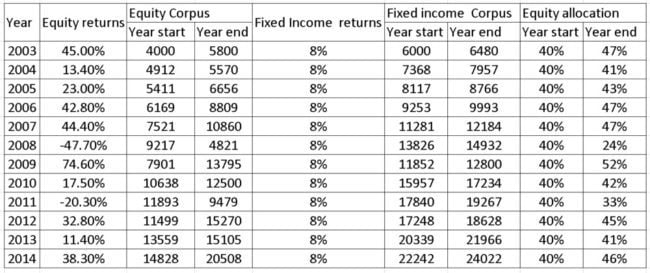
Let equity exposure be 40% (for illustration) and fixed income exposure 60%. Suppose a lump sum of Rs. 10,000 was invested at the start of 2003, the value of the equity portfolio and fixed income folio (fixed 8% return for simplicity) will evolve in the following way.
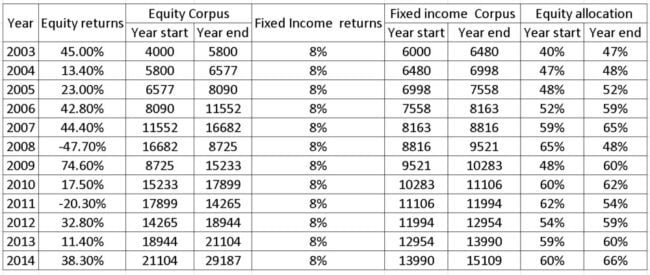
Notice how much the equity allocation varies from 40% at the end of each year. The idea behind rebalancing is to reset it back to 40% at the start of each year.
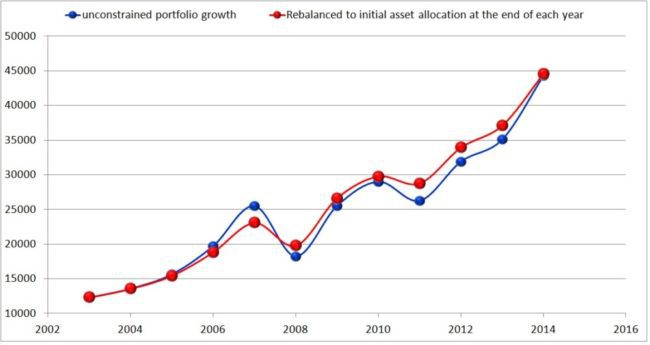
Note the lower volatility in the rebalanced portfolio. This is the primary objective of rebalancing. It is purely accidental that for the given set of returns, rebalancing has resulted in a higher value at the end of the tenure. For the above data set, this is true for any equity allocation from 36% to 99%.
I can easily show you another return data set for which rebalancing lowers volatility but also lowers final portfolio value.
When I say volatility, I am also referring to psychological comfort or mental peace, if you will. If the equity folio has moved up 90%, a fall is inevitable. Rebalancing is a way to cushion your mind and folio against such a fall. Whether it will lead to more returns or not is neither certain nor necessary.
Practical considerations
A diversified portfolio is ‘usually’ built with asset classes that are poorly or negatively correlated with each other. For example, a long-term gilt fund and equity is one way to do it.
Under ideal circumstances, interest rates are increased just before the start of a bull run. This allows the gains made in long-term gilts or gilt funds to shift to equity. As a bull run progress, inflation gradually increases and interest rates will also increase. Gilts would lose and the gains from equity can be shifted there.
Therefore, rebalancing is the process of shifting gains from an asset that has performed well to an asset that had done poorly but is expected to do well. This sounds easy to say, but quite hard to implement. Also, both asset classes can rally or crash at the same time.
I refer to this as two-way rebalancing, which is illustrated above, although the fixed income rate is 8%. Two-way rebalancing requires two poorly correlated volatile asset classes.
I generally prefer and recommend low volatile fixed income. For the simple reason, natural choices like PPF or EPF is available this way. If such fixed income is EPF of PPF, unconstrained withdrawals are not possible, and only one-way rebalancing is typically possible. That is, positive deviations from equity are shifted to fixed income. Negative deviations are ignored.
Positive deviations could have a threshold. That is, if equity allocation changes from 50% to 53%, do nothing. But if the difference increases by 5% or 10%, then and only then, rebalance.
I can use the benefit of hindsight to tell you what has worked. This does not mean such a strategy will work. If you like the idea of lower portfolio volatility and peace of mind by shifting gains to fixed income or vice versa, rebalancing will be a good idea.
How about taxes and exit loads? This can easily be lowered by letting a portfolio grow for a couple of years. Then withdrawals from equity funds will be free of tax and exit load (depending on fund structure).
Previous studies on rebalancing and portfolio management
Understanding Volatility of Investment Returns with a Portfolio Rebalancing Simulator
The What, Why, How and When of Portfolio Rebalancing With Calculators to Boot
Deciding on asset allocation for a financial goal
Asset allocation for long-term goals
Quantifying Portfolio Diversification – Part I
Portfolio Diversification with International Stocks
Portfolio Diversification: Correlation among Stock Sectors