Last Updated on July 14, 2023 at 8:24 am
A reader wants to know, “I have just started a SIP in an equity mutual fund. I plan to continue this for 15 years. Can I expect a 15% return?”.
The honest answer is, “No idea. No one knows”. We have discussed this at length before. Do not expect returns from mutual fund SIPs! Do this instead! Here is an updated graph relevant to the reader’s question.
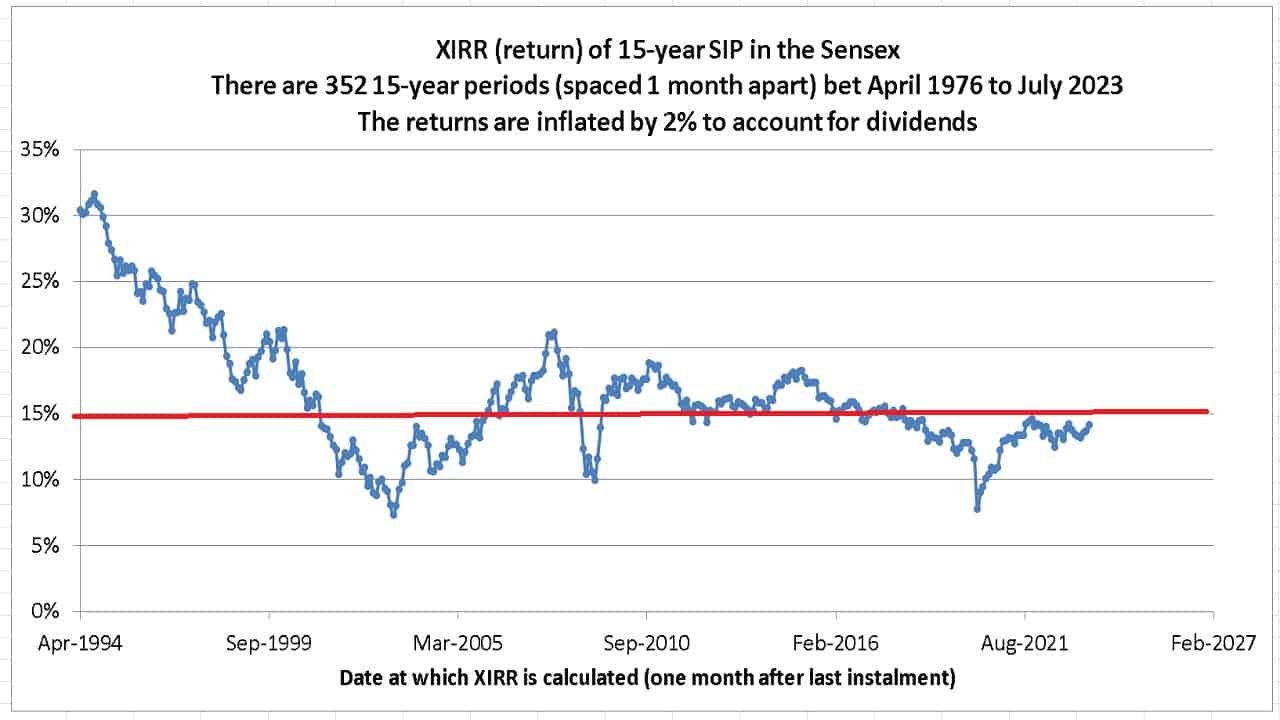
Each dot in the graph below is a return from a 15-year SIP in the Sensex. Notice that it can just about be anything. If the markets crash, so do SIP returns. If the markets recover, so do SIP returns.
This chart
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
You can expect 10% or 12%, or 15%, but the market will give you what it wants. Notice that many returns are lower than 15% (red line). The return has been below 15% for the last six years.
It would be foolhardy to expect 15% or any set return from equity mutual funds (or gold, debt mutual funds, NPS, or any market-linked asset!) Also, Equity may beat inflation, but that doesn’t mean you will!
So what is the solution?
So one cannot expect any return, but what is the solution? First, let us clarify that a bit. One should not expect any return if the idea is to simply buy units and live in hope. As shown before – How to reduce risk in an investment portfolio, no matter what the sequence of returns is (which is the reason for the return variations), one can, with a clear asset allocation plan and stepwise reduction of equity can, help us reach a target corpus.
This does not mean all is lost, and equity investing is useless! Equity investing offers us more than a reasonable chance of beating inflation. This is much more than what we get from many situations in life. That does not mean we will get our expected return! The two are quite different benchmarks. See: Why should I invest in equity mutual funds when there is no guarantee of returns?
So the solution is to replace target return (= expectation) with a target corpus. This is possible only when we are clear about the purpose of the investment. You can use the Freefincal Robo Advisory Tool and create a concise plan for each goal.
Take the case of a 15-year goal. We can use 10% before-tax or 9% after-tax returns from equity. We need some return expectation to kick-start planning. The lower, the better, but beyond that, we don’t care much about it.
However, we should not expect our portfolios to grow at that rate. First of all, 100% equity investment is a mistake. The risk is too high because the swing in the possible returns is too high.
The robo tool recommends an initial asset allocation of 50% equity and 50% fixed income. This might seem “too conservative” to many. However, by adding more equity, we only add more risk, not more reward.
Also, a 15Y goal will not always remain a 15Y goal. Before you know it, there will only be 5-6Y left, and in any case, the equity allocation has to be reduced. If, at this time, the returns are poor, the overall portfolio return will be lower than expected, and the time lost is lost forever (we cannot go back in time and invest more). See: Equity may beat inflation, but that doesn’t mean you will!
So moderate equity exposure to begin with, plus gradual tapering, will greatly increase the chances of getting close to our target corpus with lower portfolio volatility. This asset allocation plan is auto-generated by the robo tool for a 15-year and 10-year goal.
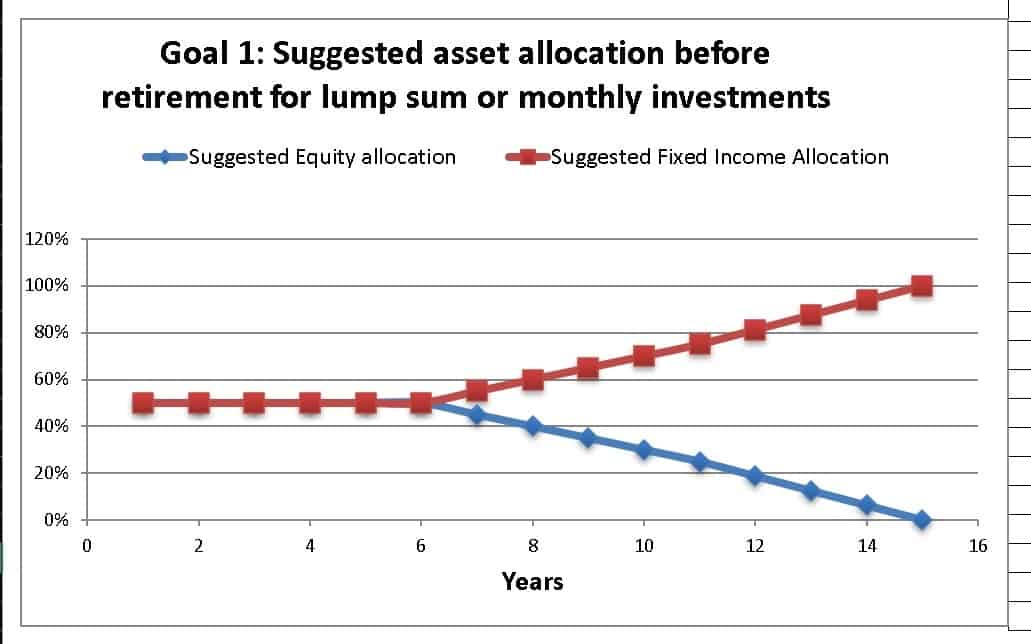
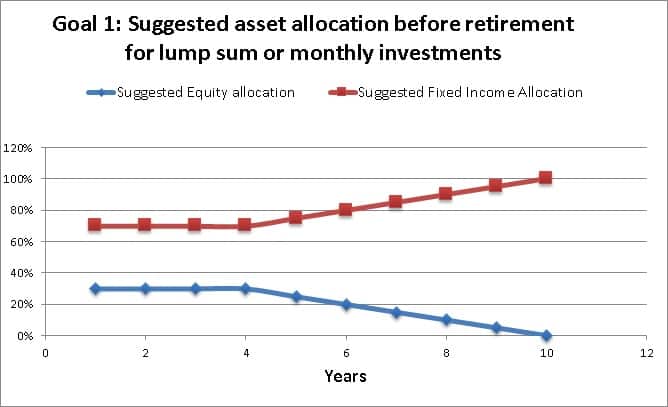
The main advantage of variable asset allocation is our focus shifts from some set return target to the target corpus. We don’t need to worry about news and events that affect market returns.
In summary, we recommend that the reader first appreciate the importance of asset allocation, including a substantial amount of debt (fixed income) in the portfolio, and then consider an equity de-risking plan as indicated above. To start from scratch, see Basics of portfolio construction: A Guide for Beginners.