Last Updated on September 9, 2022 at 8:48 am
“Has anyone ever gotten rich using mutual funds?”. You may have seen this question do the rounds on social media and personal financial forums from time to time. This is asked by two sets of people.
(1) Those who wish to push other products: Insurance, stock advisory services or a PMS and (2) young investors unsure about the capital markets. The former group has an agenda and can safely be ignored. We will focus on the latter group here.
To offer a superficial answer, I know plenty* of people who have gotten rich using mutual funds. I am one of them: Fourteen Years of Mutual Fund Investing: My Journey and lessons learned. *I stopped to count: the number of readers who have changed their social station predominantly due to mutual funds over the years is at least 17, excluding me. If a loner like me can count 17, I am sure there are thousands more.
That is not the point, though. We have been brainwashed by the financial services industry with tales of compounding and huge returns. We believe we can change our lives if there is a guaranteed way of getting such huge returns. That is why we are looking for “solved example problems.”
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
In my talks, I often ask the audience this question. Two co-workers started investing the same day. One chose only fixed deposits and the other only mutual funds. The FD guy got 7% returns after 25 years, while the MF guy got 13% returns. Who made more money?
Most people in the audience assume it is the MF guy until someone realises that the amount invested by the co-workers is not known. A 7% portfolio can result in greater wealth than a 12% portfolio if the amount invested in MFs is less.
The point is that returns are important but not as important as the amount we keep investing and the time we allow it to grow. We need money to make money.
The instrument is only secondary. Anyone who systematically invests and anyone who systematically increases their investment each year will end up with a sizeable chunk of wealth no matter where they put it – MFs, FDs etc.
We cannot buy anything with “huge returns”. We cannot beat inflation with “huge returns” – unless we invest enough. See: Equity may beat inflation, but that doesn’t mean you will! And, Why you need time, money and returns to beat inflation.
So anyone looking to create “wealth” should aim for two things: (1) Time – start immediately (don’t waste time thinking about lost time!) and (2) Increase your income but do not proportionately increase your expenses! Invest as much as possible and increase this investment each year as much as possible.
Yes, you need a good chunk of equity for long term goals. This equity can be in any place you are comfortable with: stocks, MFs, ETFs, stock baskets, PMS, whatever. The point is that it is not the instrument that will make you rich. Only your understanding of it and how much you invest in it consistently will.
Take my equity mutual fund portfolio for retirement, for instance. For the first five years from June 2008, returns were zero. Then it shot up. In March 2020, it fell to 2.75% – My retirement equity MF portfolio return is 2.75% after 12 years! Not much happened to my financial independence status, though.
If this happens after 12 years, it can happen at any time. So one of my biggest lessons is: Do not expect returns from mutual fund SIPs! (Do this instead!)
The rate at which our investments grow keeps changing. We have no control over it. We have better control over the rate at which our investing grows. The primary reason I was able to achieve financial independence is that I was able to increase my investments much more than the return I got from them. I was lucky that my investing rate was also significantly more stable than portfolio returns. See: Why increasing investments each year is crucial for financial freedom.
Therefore I urge young earners not to search for that magic instrument or magic return that will change their life. Have a long-term vision of your lives: In 20-30 years, I will be a multi-crorepati. I will not waste my time chasing shortcuts. I will increase my income and invest as much as possible without expecting immediate results. Choose a balanced portfolio of 50-60% equity (ideally index funds) and 50-40% fixed income (EPF/PPF/NPS/Debt funds etc.).
In this portfolio, they should start investing as much as possible immediately and increase investments each year as much as possible. They should invest without worrying about market conditions. Once this is set in motion, they should learn portfolio risk management (rebalancing, de-risking) as per their need and implement it as required. That is it. If this is done for a decade, we will see the change. If this is done for two decades, we can cement the change.
We are on Google News
Use this button to add freefincal.com as a preferred personal finance source on Google News.
Explore 1,400+ videos on YouTube!
Subscribe to get posts via email!
Join 32,000+ readers and get free money management solutions delivered to your inbox! (Link takes you to our email sign-up form)Join our WhatsApp Channel
Explore our products
🔥Join our community of 9000+ users! 🔥- Use our Robo-advisory Tool to create a complete financial plan! More than 3,500 investors and advisors use this! Use the discount code robo25 for 20% off. Plan your retirement (early, normal, before, and after), plus non-recurring financial goals (such as child education) and recurring financial goals (such as holidays and appliance purchases). The tool helps anyone aged 18 to 80 plan for retirement, plus six non-recurring and four recurring financial goals, with a detailed cash flow summary.
- Our Flagship Course! Learn to manage your portfolio like a pro to achieve your goals regardless of market conditions! More than 3,500 investors and advisors are part of our exclusive community! Get clarity on how to plan for your goals and achieve the necessary corpus no matter the market conditions! Watch the first lecture for free! One-time payment! No recurring fees! Lifelong access to videos! Reduce fear, uncertainty and doubt while investing! Learn how to plan for your goals before and after retirement with confidence.
- Join the freefincal investor circle! An exclusive space for investors, advisors, fintech employees and students to access financial planning and insurance tools, mutual fund and stock analysis tools, coding strategies and Excel macros for data extraction. 750+ members are now part of our investor circle.
- Increase your income by getting people to pay for your skills! More than 900 salaried employees, entrepreneurs and financial advisors are part of our exclusive community! Learn how to get people to pay for your skills! Whether you are a professional or small business owner seeking more clients through online visibility, or a salaried individual looking for side or passive income, we will show you how to do it by showcasing your skills and building a community that trusts and pays you. (Watch the 1st lecture for free). One-time payment! No recurring fees! Lifelong access to videos!
- Portfolio Tracker! Track your mutual funds and stock investments with our Google Sheet!
- We also publish monthly screeners for
Our Podcast: Let's Get Rich With Pattu
On Spotify: Let's Get RICH With PATTU! Every single Indian CAN grow their wealth! On Audible: Listen to the Let's Get Rich with Pattu Podcast
Listen to the Let's Get Rich With Pattu podcast on YouTube.
Now watch Let's Get Rich With Pattu தமிழில் (in Tamil)!About The Author
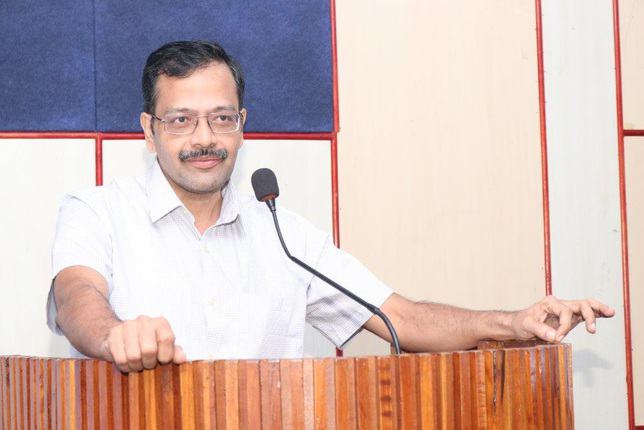
Dr M Pattabiraman giving a lecture
- Dr M. Pattabiraman (PhD) is the founder, managing editor and primary author of freefincal. He is an associate professor at the Indian Institute of Technology, Madras.
- He has over 14 years of experience publishing news analysis, research and financial product development. He has over 28 years of teaching and research experience. He is also a public speaker and keynote presenter.
- He is a patron and co-founder of “Fee-only India,” an organisation promoting unbiased, commission-free, AUM-independent investment advice.
- Connect with him via @pattufreefincal on X LinkedIn YouTube
- Pattabiraman has co-authored three print books.
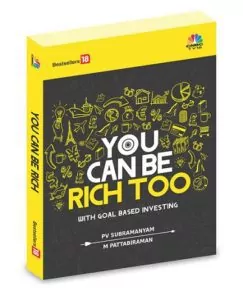
This book helps you ask the right questions and find the right answers. It also includes nine online calculators to create custom solutions.
(2) Gamechanger: Forget Startups, Join Corporate & Still Live the Rich Life You Want. 
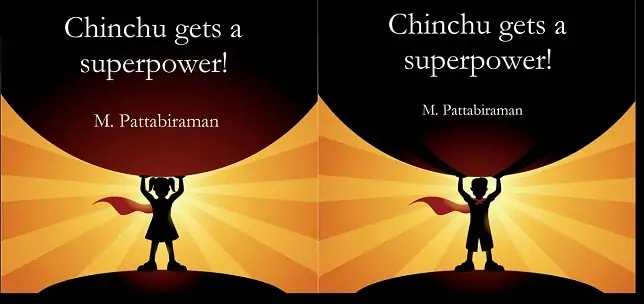
Both the boy and girl versions of "Chinchu Gets a Superpower".
Most investor problems stem from a lack of poor decision-making. We made bad decisions and money mistakes when we started earning, and we spent years undoing them. Why should our children go through the same pain? What is this book about? As parents, what if we had to groom one ability in our children that matters not only for money management and investing but for every aspect of life? My answer: Sound decision-making. So, in this book, we meet Chinchu, who is about to turn 10. The story follows what he wants for his birthday and how his parents plan it, while also teaching him key ideas about decision-making and money management. What readers say! 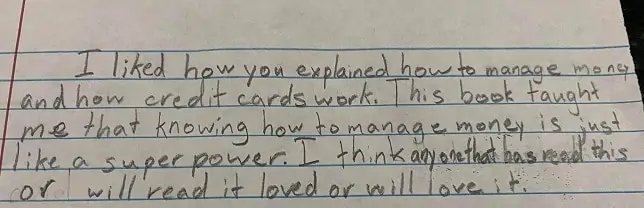
Feedback from a young reader after reading Chinchu Gets a Superpower!
Must-read book even for adults! This is something that every parent should teach their kids right from a young age. The importance of money management and decision-making based on their wants and needs. Very nicely written in simple terms. - Arun.
About freefincal & its content policy
Freefincal is a News Media organisation dedicated to providing original analysis, reports, reviews and insights on mutual funds, stocks, investing, retirement and personal finance developments. We do so without conflict of interest and bias. Follow us on Google News. Freefincal serves more than three million readers a year (5 million page views) with articles based only on factual information and detailed analysis by its authors. All statements made will be verified with credible and knowledgeable sources before publication. Freefincal does not publish paid articles, promotions, PR, satire or opinions without data. All opinions will be inferences backed by verifiable, reproducible evidence/data. Contact Information: To get in touch, please use our contact form. (Sponsored posts or paid collaborations will not be entertained.)Our publications
- Your Ultimate Guide to Travel. This is an in-depth exploration of vacation planning, including how to find affordable flights, budget accommodations, and practical travel tips. It also examines the benefits of travelling slowly, both financially and psychologically, with links to relevant web pages and guidance at every step. Get the PDF for Rs 300 (instant download)
- How to profit from content writing: Our ebook is for those interested in getting a side income via content writing. It is available at a 50% discount for Rs. 500 only!