A reader says that he has realized the importance of retirement planning only at age 35 and his current net worth is essentially zero. He would like to retire by age 55 and wants to know how to go about it.
With twenty years to go, there is a good chance of accumulating enough corpus for retirement. If necessary, one can consider an extension up to age 60. Let us find out using the freefincal robo advisory tool.
- Current monthly expenses that will persist in retirement 50,000
- Additional Annual expenses that will persist in retirement 50,000
- Age at the end of the current year: 35
- Age you wish to retire 55
- Years to retirement 20
- Total average monthly expenses (annual/12) 54,167
- Inflation before retirement (%) 6
- The assumed life expectancy of a younger spouse: 90 (spouse is aged 30)
- Inflation during retirement (%) 6
- Years to retirement 20
- Monthly expenses in the first year of retirement 1,73,720
- Years in retirement (until younger spouse reaches age 90) 40
- The Corpus required for retirement: 6,38,05,162 (that is 6.38 Crores)
- monthly investment required, including EPF/NPS contributions (scroll down to see investment schedule): 1,02,762
- If the investments can be increased by 5% each year, the initial monthly investment will be: Rs. 70,870
- If the investments can be increased by 10% each year, the initial monthly investment will be Rs. 46,275
- If the retirement age is increased to 60, the corpus will increase to Rs. 8.24 Crores. This may be counterintuitive and is explained here: Retire early to lower your retirement corpus!
- At a 10% increase each year, the initial monthly investment will be Rs. 30,706.
Thus the reader can adjust his retirement goals according to his investment capability.
The asset allocation schedule is given below, along with the variation in the expected portfolio return.
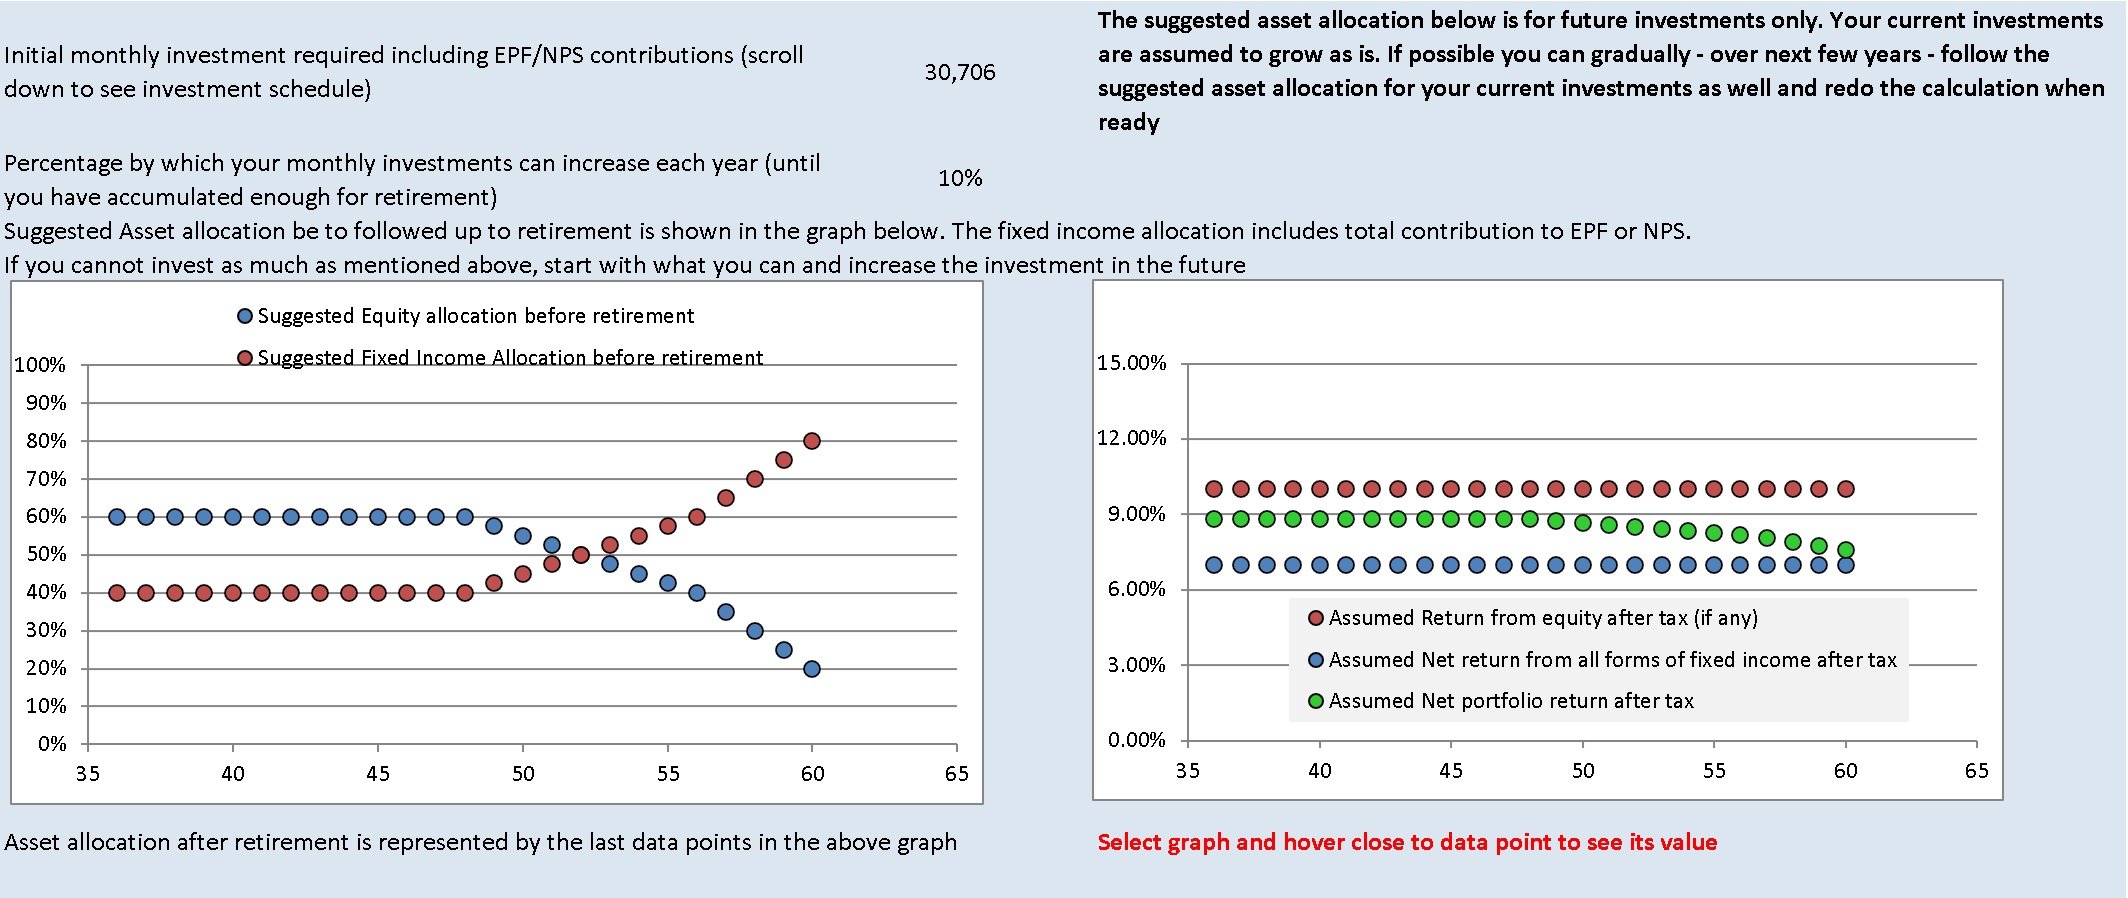
The retirement calculation uses a five-bucket strategy (this example assumes retirement at age 60):
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
- An emergency bucket to handle unexpected expenses.
- An income bucket providing guaranteed income for the first 15 years of retirement. During this time, investments are made in the following three buckets.
- Corpus from a low-Risk bucket that provides income from year 16 to year 25 in retirement. To provide this income, the low-risk bucket will have an asset allocation of 30% equity and 70% debt during the investment period (years 1 to 15 of retirement).
- Corpus from a medium-risk bucket will provide retirement income from years 26 to 30. To provide this income, this bucket shall have an asset allocation of 50% equity and 50% debt during the investment period (year 1 to year 26)
- Corpus from a high-risk bucket will provide income from year 31 to 35 in retirement. To provide this income, this bucket shall have an asset allocation of 70% equity and 30% debt during the investment period (year 1 to year 34)
In summary, the reader can still accumulate enough corpus for retirement, provided he can stick to the investment schedule either for retirement at age 55 or 60.