Last Updated on May 28, 2022 at 6:43 pm
It is every parents’ dream and duty to ensure our children can do what they want to in life. It would also be great if our children do not start their earning lives with an educational loan Therefore it is important that we plan and invest right for our child’s future. Here is a simple calculation and a set of tips for this purpose. Please sit with your spouse this weekend and finish this task!
Readers may recall that I had done a similar exercise for retirement planning in two steps: Part one: Find out how much you need to retire in 15 mins: build your own calculator Video version is here(part 1). Part 2 video is here. One may ask which is more important? Planning for a secure retirement or our children’s future. Emotionally this is an easy question to answer: Our children come first!
Especially if we became young parents and can work for at least a decade after they start school. However since couples are becoming parents in their early and mid 30s with tough corporate jobs, both goals become equally important. Unless we sit and calculate how much investment is to be made, we will never take them seriously. That is why it is crucial to do this exercise as a couple.
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
Step 1: Project current and current class (in school) into the future
Set up the following columns in any spreadsheet software of your choice. It will tel you when exactly you need the money for college. Or how many years you have to invest. Here it is 9 years
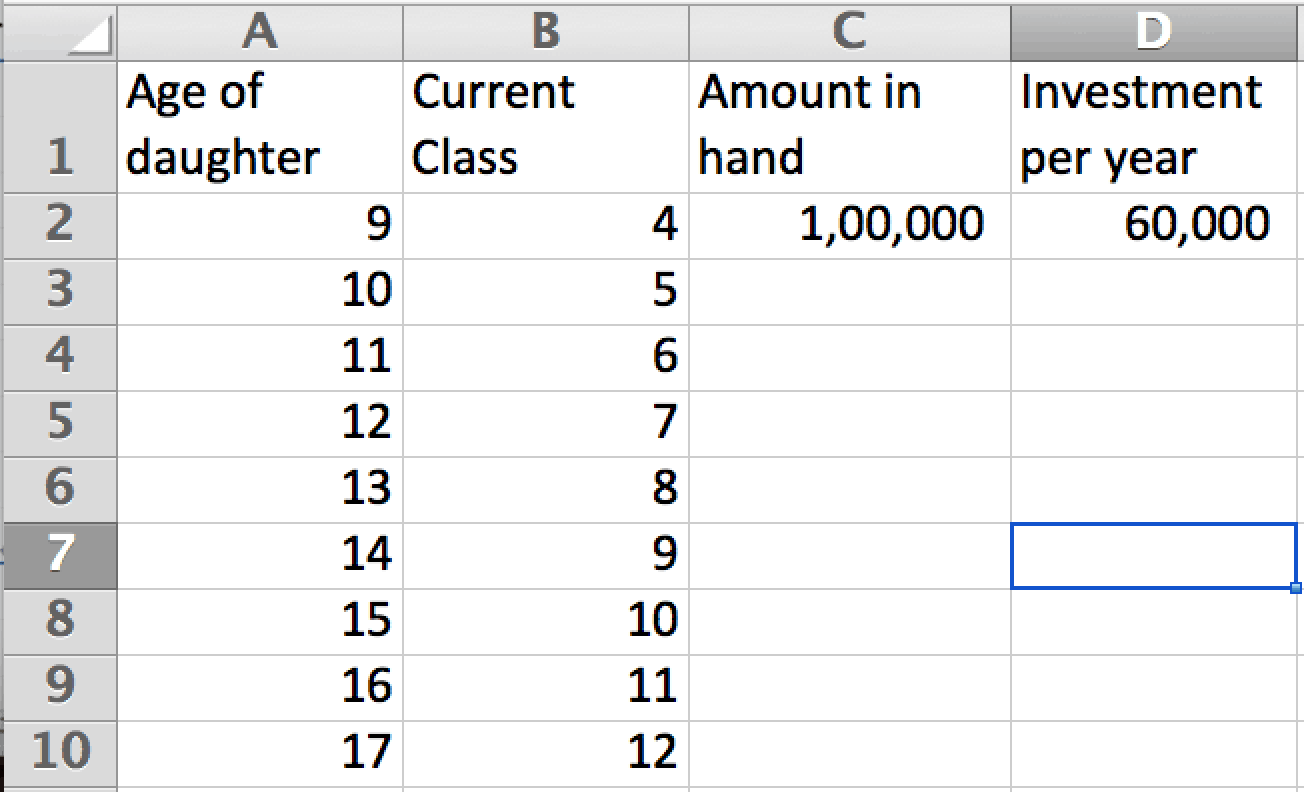
We also add the money available at hand, say Rs. one lakh in previous investments. We also assume you can invest Rs. 5000 a month or Rs. 60,000 a year. Here are assuming the girl will enter class four this coming academic year.
Step 2: Growth of the amount in hand
We assume that the Rs. One lakh in hand grows at about 7% post-tax a year, resuling in about 1.8 lakh after 9 years.

Step 3: Growth of future investment amount
This step is crucial. Please try to increase the investment amount by at least 10% a year!

Step 4: Computing the value of monthly investments
To do this, we first need to know how much to invest in equity and how to invest in fixed income. We need an asset allocation. Alternatively, we can enter a portfolio return each year as shown below.
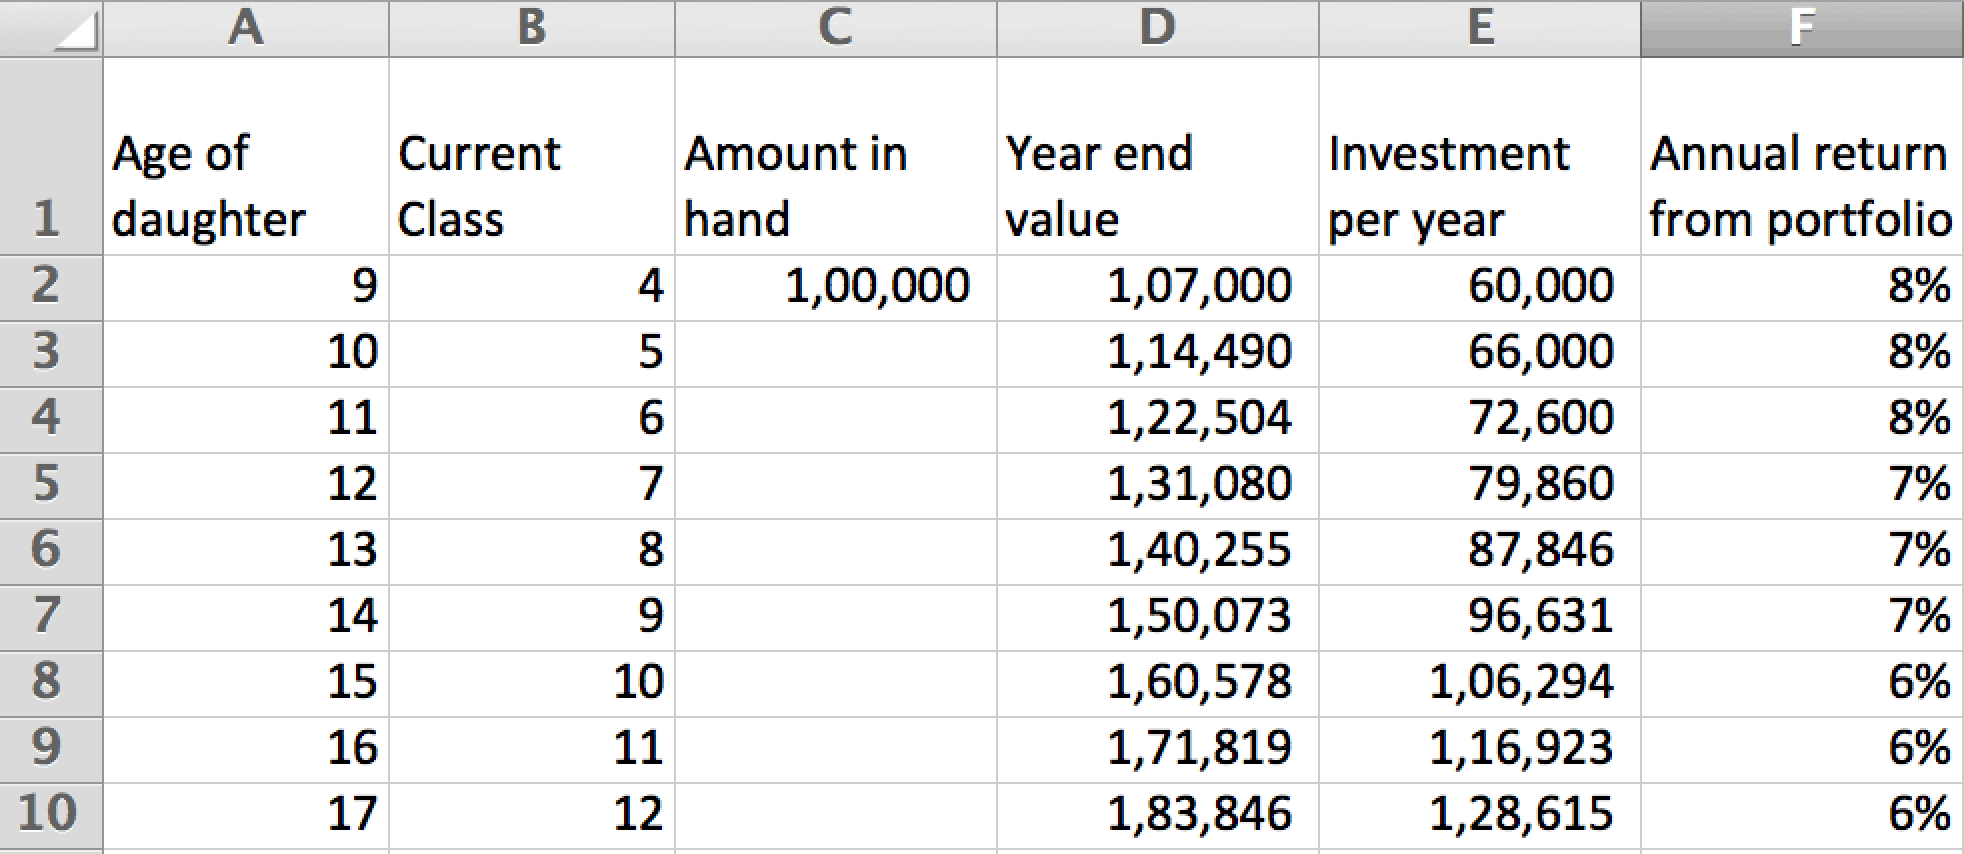
This corresponds to about 40% equity initially and 60% fixed income for the first 3 years or so, reduced to 20% equity in the middle three years and 0% equity in the last three years. Where to invest this? I have made product suggestions in the video version linked below.
Step 5: finding the final investment amount
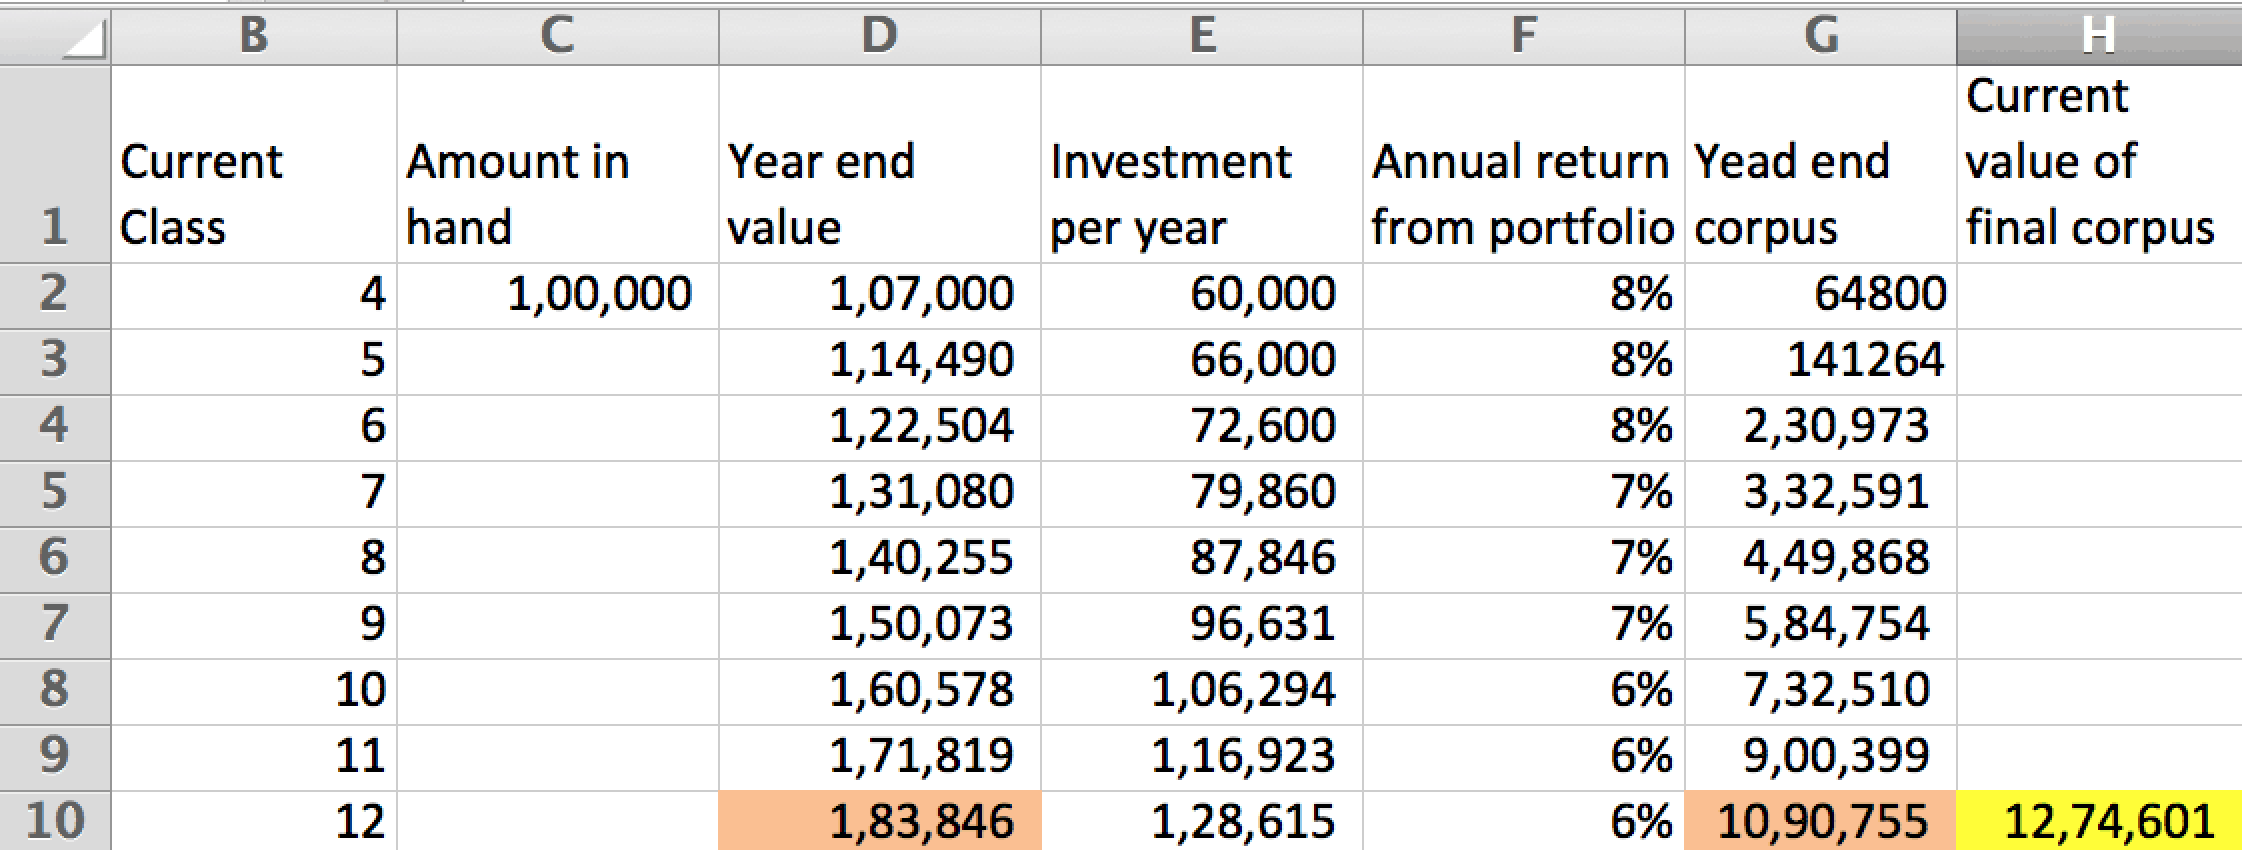
In column G, we compute how the investments made each year grows with the corresponding annual return in column F. In column H, the total final value is shown. The yellow cell is the sum of two orange cells. If you want some help in computing column G, see the vide version.
Step 6: Finding what the projected corpus is worth today
Now we take the value in the yellow cell and devalue it by 10% (assumed inflation in education expenses) year after year to find what the current value of the projected corpus is. To ensure I do it for 9 years, the cell in blue is devalued twice to get the current value.
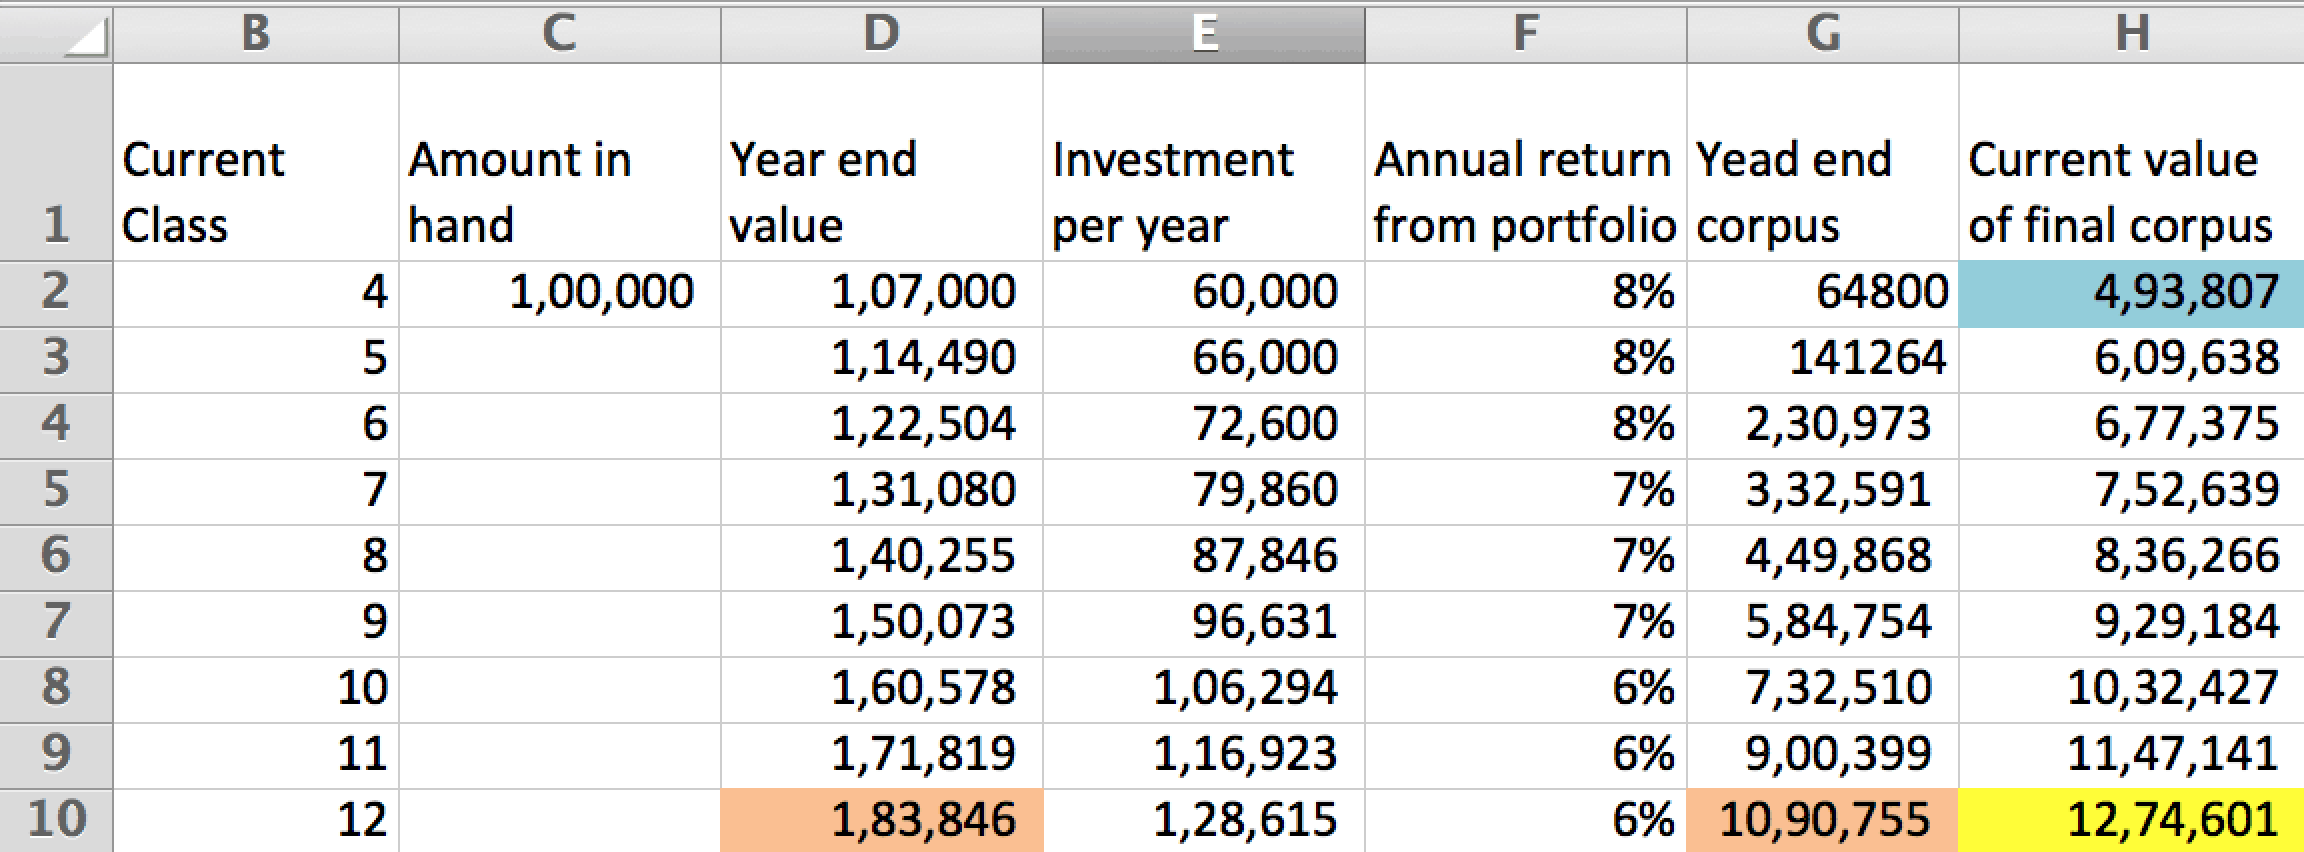
So this means our future investments are worth about 5 lakh today. If this amount is at least 70-80% of a college education today, then the child will probably not need an educational loan.
Step 7: Choosing the investment products (watch video version)
The advantage of the above calculation is flexibility and a better understanding of what is going on and what has to be done.
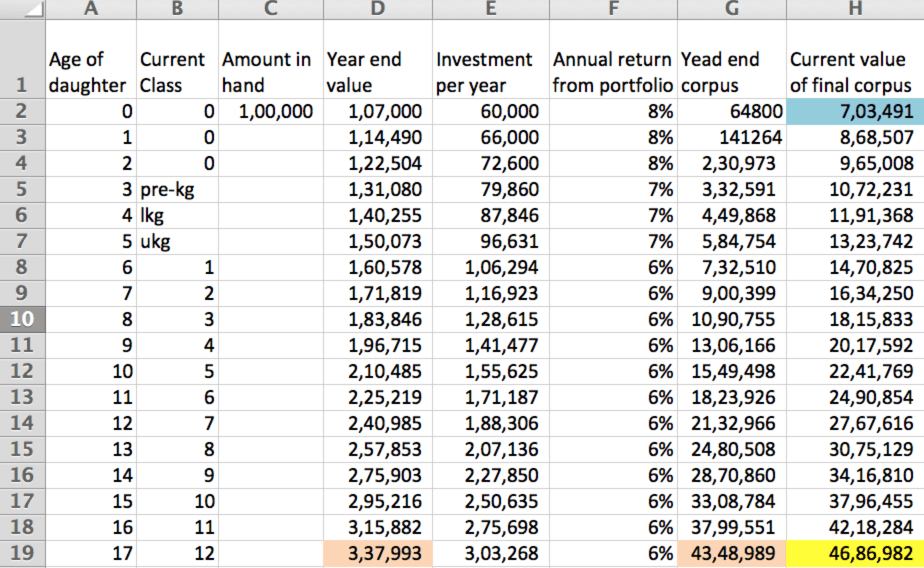
Step 8: Projections for a newborn (<1-year-old) conservative
I have made two projections for a newborn with a full 17-18 years of time for investment. Even with a conservative return projection, the corpus is decent.
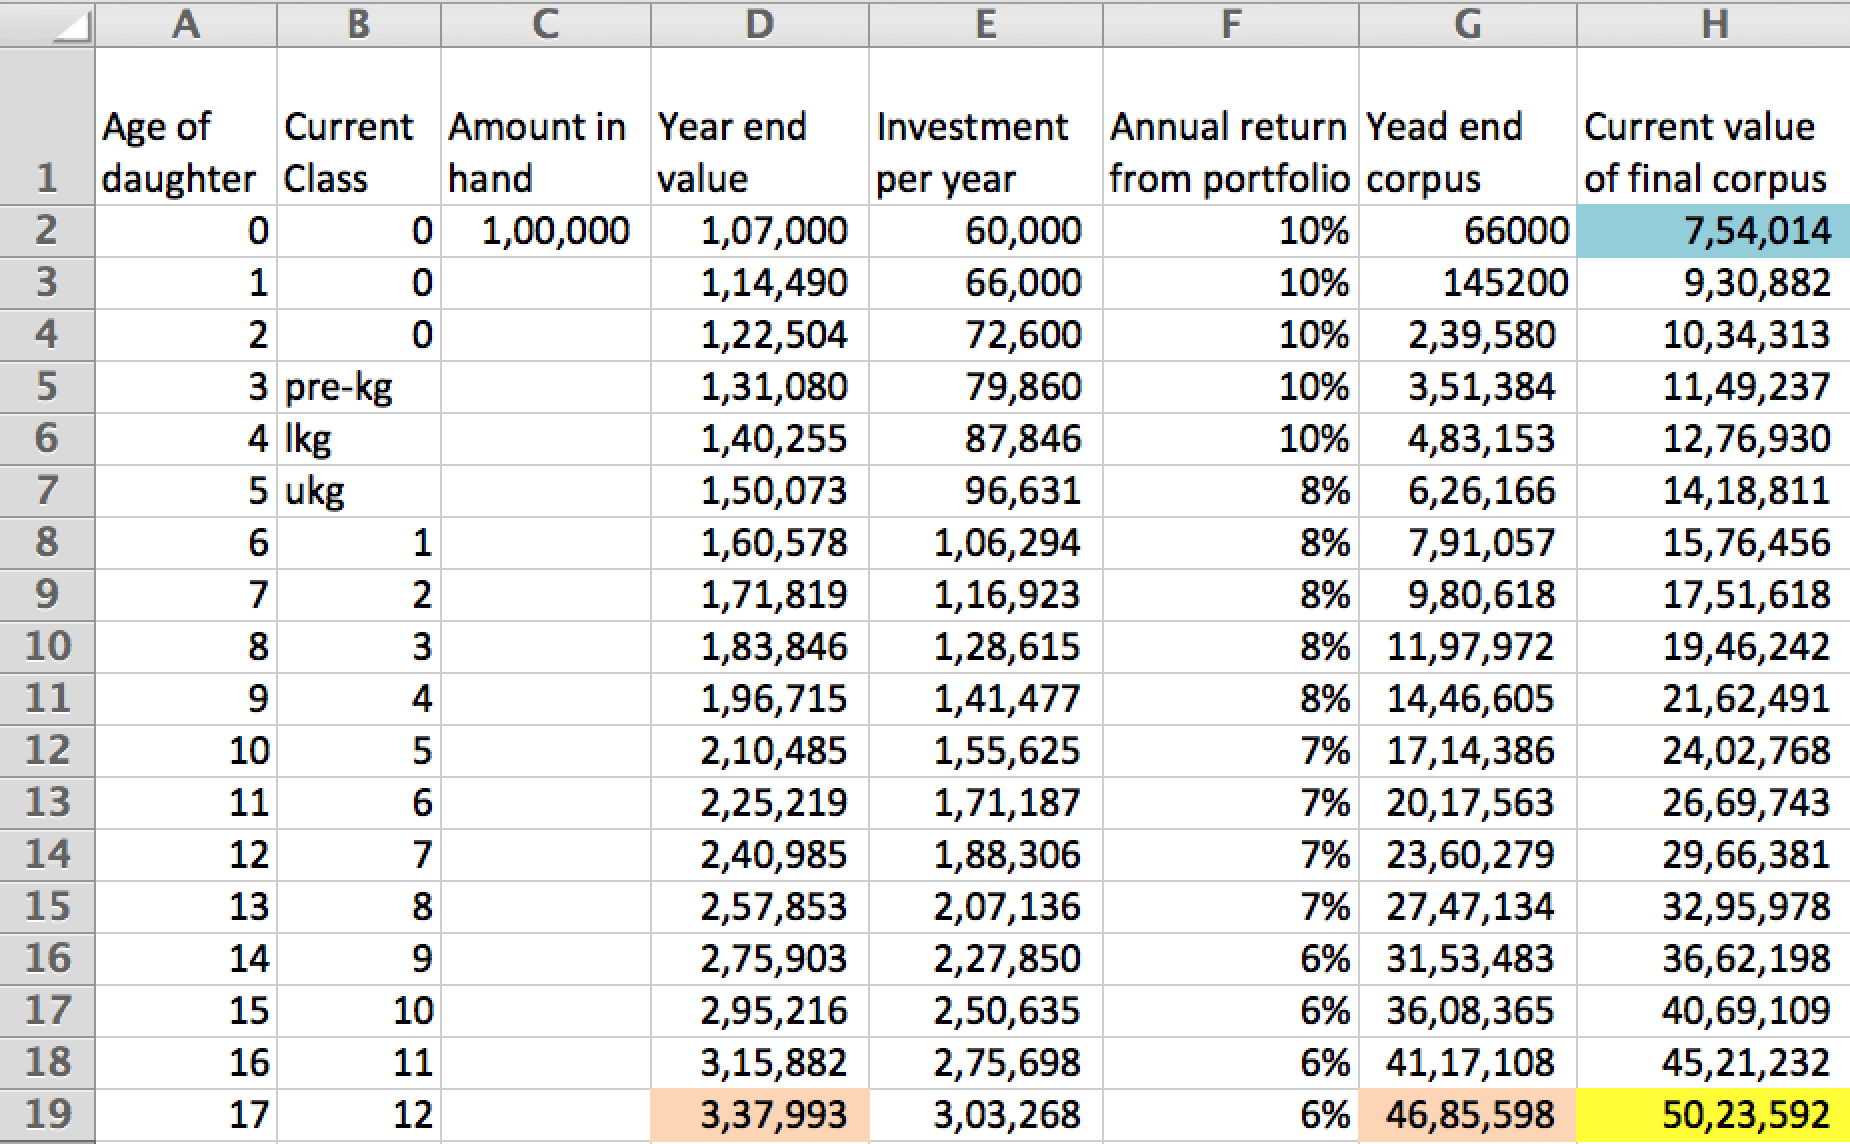
Step 9: Projections for a newborn (<1-year-old) aggressive
This is the same as above with with a more aggressive return expectation (higher equity)
Weekend exercise
- Please do these steps with your spouse and let me know if it was useful
- What kind of asset allocation would you use for step 8 and 9. Hint: How to reduce risk in an investment portfolio
Explore more videos from freefincal on YouTube