Last Updated on February 5, 2026 at 5:58 am
Can I retire at 40 with one crore in India? Is it possible to retire early in India with just one crore? Since the answer is not a simple “yes” or “no” let us do a how to retire early at 40 feasibility check with some reasonable and close to reality assumptions. First, it is important to understand what early retirement means and what it is not. SInce there are many misconceptions about FIRE – financial independence, retire early, I would strongly suggest that you check out this video first.
Assumptions for a 40-year-old with one crore wanting to retire early in India
Not every 40-year-old can retire early. So we will have to define our universe and make several assumptions. The feasibility of the plan entirely depends on these assumptions. So utmost care is necessary. For a more thorough feasibility check please use the freefincal Robo Advisory Software Template.
Warning: This article has several projections based on assumptions which can often be far removed from reality. So no part of this article should be considered as investment advice. It is meant to educational to a potential early retiree. I shall take no responsibility for your gains or losses arising from adapting this or any other approach discussed here. Be sure to read the limitations section below.
- The person is unmarried or married without kids (with no plans to become parents). Unless there is there is a separate corpus to provide for their needs, it is not possible to retire early with kids in India with just one crore. No need to compute that!
- We shall assume that the spouse or partner does not work.
- There is no separate emergency fund
- Health insurance for Rs. 25 lakh is available and the premium at 40 is Rs. 15,000 for a single person and Rs, 25,000 for the couple (floater, both aged 40). The health insurance premium increases every 5 years by 10%
- Current annual expenses are Rs. 2.5 Lakh year (20K a month) for one person and Rs. 30K for two. This is assumed to increase at 6% inflation year on year.
- Forty lakh is put in fixed income that returns 6% a year (post-tax). The rest in equity with a 10% post-tax return assumption. As pointed out earlier: if we want to be financially free, we should not count on frugality, but worry about sequence of returns risk! So instead of a constant 10% return, testing with variable return testing is mandatory but we do not have enough history for this. We shall however consider one example.
- From the six year onwards, we shift 10% of equity corpus to fixed income.
How to retire early at 40: Case 1: single: early retirement feasibility check
This table illustrates how the above assumptions play out year on year. I shall explain how to create this table in a video. The number under “how long will the money last?” column is calculated as: total corpus (year end) divided by expected annual expensed in the next year. When this number falls below one, income withdrawals are not possible. The idea is to ensure that this number fall below one at least after age 85 (of the younger spouse/partner).
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
For Rs. 20,000 monthly expenses and 15,000 health insurance and above assumptions the corpus can last up to age 95-96 which is decent. Scroll down the table to see pictorial representation.
| Age | Total expenses | Fixed Income corpus year end | Equity corpus year end | How long will the money last? |
| 40 | 2,55,000 | 39,69,700 | 66,00,000 | 39.23 |
| 41 | 2,69,400 | 39,22,318 | 72,60,000 | 39.28 |
| 42 | 2,84,664 | 38,55,913 | 79,86,000 | 39.36 |
| 43 | 3,00,844 | 37,68,374 | 87,84,600 | 39.48 |
| 44 | 3,17,994 | 45,88,569 | 86,96,754 | 39.34 |
| 45 | 3,37,674 | 54,27,805 | 86,09,786 | 39.33 |
| 46 | 3,56,945 | 62,87,749 | 85,23,689 | 39.25 |
| 47 | 3,77,371 | 71,68,512 | 84,38,452 | 39.11 |
| 48 | 3,99,024 | 80,70,133 | 83,54,067 | 38.92 |
| 49 | 4,21,975 | 89,92,579 | 82,70,527 | 38.54 |
| 50 | 4,47,953 | 99,33,979 | 81,87,821 | 38.25 |
| 51 | 4,73,742 | 1,08,95,761 | 81,05,943 | 37.92 |
| 52 | 5,01,077 | 1,18,77,594 | 80,24,884 | 37.55 |
| 53 | 5,30,053 | 1,28,79,032 | 79,44,635 | 37.13 |
| 54 | 5,60,767 | 1,38,99,492 | 78,65,188 | 36.57 |
| 55 | 5,95,139 | 1,49,36,324 | 77,86,537 | 36.09 |
| 56 | 6,29,649 | 1,59,90,448 | 77,08,671 | 35.57 |
| 57 | 6,66,230 | 1,70,60,790 | 76,31,584 | 35.02 |
| 58 | 7,05,006 | 1,81,46,078 | 75,55,269 | 34.45 |
| 59 | 7,46,109 | 1,92,44,826 | 74,79,716 | 33.76 |
| 60 | 7,91,674 | 2,03,53,191 | 74,04,919 | 33.13 |
| 61 | 8,37,857 | 2,14,71,176 | 73,30,870 | 32.48 |
| 62 | 8,86,810 | 2,25,96,500 | 72,57,561 | 31.80 |
| 63 | 9,38,701 | 2,37,26,568 | 71,84,985 | 31.11 |
| 64 | 9,93,706 | 2,48,58,442 | 71,13,135 | 30.33 |
| 65 | 10,54,207 | 2,59,86,482 | 70,42,004 | 29.60 |
| 66 | 11,16,010 | 2,71,09,153 | 69,71,584 | 28.84 |
| 67 | 11,81,521 | 2,82,22,278 | 69,01,868 | 28.08 |
| 68 | 12,50,962 | 2,93,21,193 | 68,32,850 | 27.29 |
| 69 | 13,24,571 | 3,04,00,701 | 67,64,521 | 26.45 |
| 70 | 14,05,011 | 3,14,52,471 | 66,96,876 | 25.64 |
| 71 | 14,87,718 | 3,24,72,507 | 66,29,907 | 24.82 |
| 72 | 15,75,386 | 3,34,53,718 | 65,63,608 | 23.99 |
| 73 | 16,68,315 | 3,43,88,270 | 64,97,972 | 23.14 |
| 74 | 17,66,819 | 3,52,67,522 | 64,32,992 | 22.25 |
| 75 | 18,73,892 | 3,60,79,146 | 63,68,662 | 21.39 |
| 76 | 19,84,571 | 3,68,15,327 | 63,04,976 | 20.51 |
| 77 | 21,01,892 | 3,74,64,569 | 62,41,926 | 19.63 |
| 78 | 22,26,251 | 3,80,14,261 | 61,79,507 | 18.74 |
| 79 | 23,58,073 | 3,84,50,587 | 61,17,712 | 17.82 |
| 80 | 25,00,726 | 3,87,55,330 | 60,56,534 | 16.92 |
| 81 | 26,48,840 | 3,89,14,872 | 59,95,969 | 16.01 |
| 82 | 28,05,842 | 3,89,11,145 | 59,36,009 | 15.09 |
| 83 | 29,72,263 | 3,87,24,432 | 58,76,649 | 14.17 |
| 84 | 31,48,669 | 3,83,33,233 | 58,17,883 | 13.22 |
| 85 | 33,38,876 | 3,77,10,714 | 57,59,704 | 12.29 |
| 86 | 35,37,086 | 3,68,34,574 | 57,02,107 | 11.35 |
| 87 | 37,47,189 | 3,56,77,051 | 56,45,086 | 10.41 |
| 88 | 39,69,898 | 3,42,07,961 | 55,88,635 | 9.46 |
| 89 | 42,05,970 | 3,23,94,506 | 55,32,749 | 8.50 |
| 90 | 44,59,743 | 3,01,97,320 | 54,77,421 | 7.55 |
| 91 | 47,24,993 | 2,75,81,273 | 54,22,647 | 6.59 |
| 92 | 50,06,159 | 2,45,04,421 | 53,68,421 | 5.63 |
| 93 | 53,04,194 | 2,09,21,294 | 53,14,736 | 4.67 |
| 94 | 56,20,111 | 1,67,82,616 | 52,61,589 | 3.70 |
| 95 | 59,58,874 | 1,20,30,895 | 52,08,973 | 2.73 |
| 96 | 63,13,839 | 66,12,231 | 51,56,883 | 1.76 |
| 97 | 66,90,101 | 4,64,087 | 51,05,314 | 0.79 |
| 98 | 70,88,939 | – 64,81,180 | 50,54,261 | -0.19 |
| 99 | 75,11,708 | – 1,42,96,710 | 50,03,719 | -1.17 |
| 100 | 79,64,122 | – 2,30,66,087 | 49,53,682 | #DIV/0! |

Can a single person retire at 40 in India with one crore?
Answer: Possible; Probable; However needs tremendous luck (see limitations below)
How to retire early at 40 Case 2: Couple (no kids): early retirement feasibility check
Monthly expenses: 25,000. Health insurance premium (annual): Rs. 25,000. All other assumptions as above.
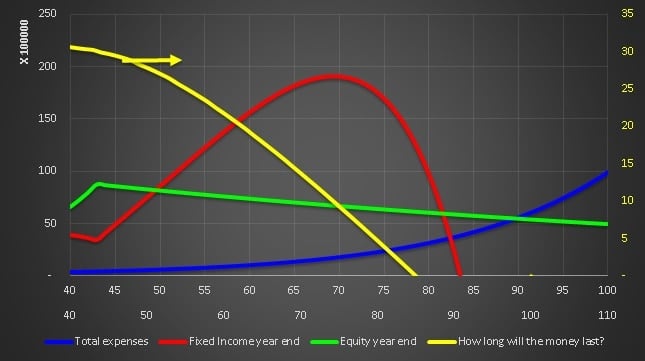
Can a couple person retire at 40 in India with one crore?
Answer: With 25K monthly expenses (+ health insurance costs) the money will last until 84. So it would be a huge risk (see limitations below)
Monthly expenses: 30,000. Health insurance premium (annual): Rs. 25,000. All other assumptions as above. The money will last only until age76.
How would a couple need to retire at 40 in India?
At least 1.5 Crores.
What are the limitations of this study?
Let us go over each of the assumptions
- Monthly expense reasonable but sudden jumps in expenses due to sickness is not considered.
- Lifestyle creep is not considered
- Inflation assumption of 6% for current expenses is “ok”, but 8% is better.
- Fixed income post tax return of 6% is just about possible
- Equity post tax return of 10% is just about possible. However unlike when investing for retirement, this number has little relevance as sequence of returns has to be considered as done here: Want to be financially free? Worry about sequence of returns risk!
- Health insurance costs could suddenly shoot up because of changes in company policy
- 10% transfer from equity to fixed income is possible and necessary but is it practical?
- No emergency corpus is accounted for. Reimbursement health claims can get in trouble otherwise (one can make do with a credit card to some extent). At least 15-20 lakh emergency corpus would be better.
- Anything else? Please leave a comment.
Factoring in the sequence of returns
We have assumed equity return each year is a nice 10%. This is how returns would fluctuate in reality.
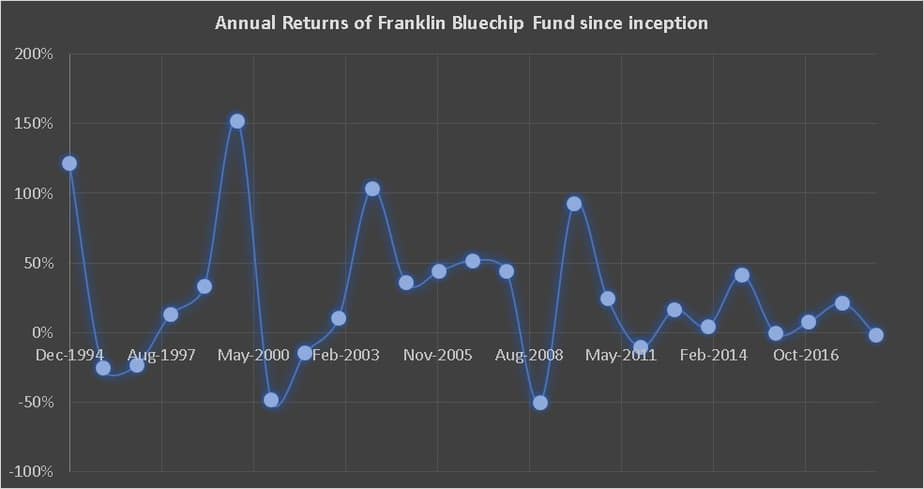
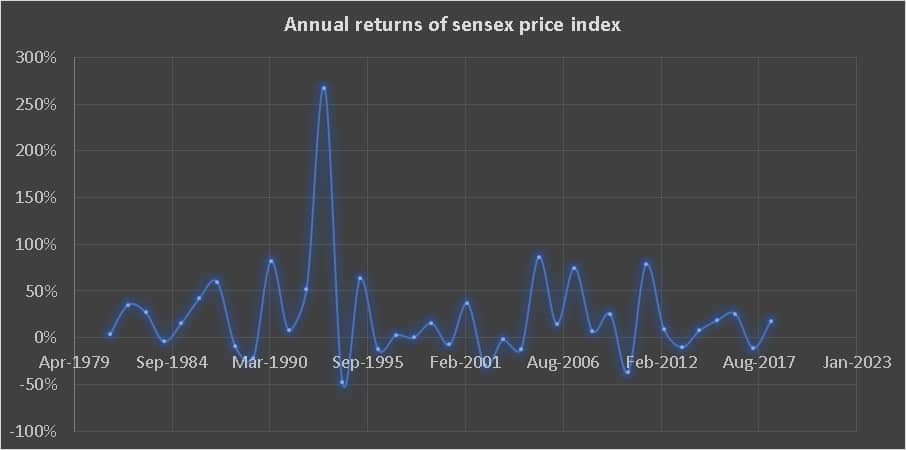
The problem is that there are only 39 data points. This means I can test only one sequence of returns. I will need to test at least 100s of sequence of returns for which we do not have data.
Even for this one favourable sequence of return (where above results are not altered much), the equity corpus can fluctuate this much. How many early retirees can stomach? How many of them have such an experience?
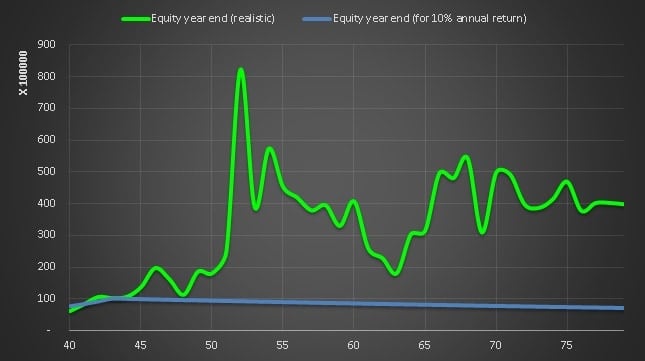
So I would recommend a higher corpus so that you can live off your fixed income assest for at least 15 years while equity recovers. Use the Key features of the freefincal robo advisory software template to stress test your retirement plan. Do not be in a hurry to quit with just one crore.