I have been investing for my son’s future (college and other expenses) since Dec 2009 – a month before he was born (He is 14 now). Here are some lessons from this journey.
Many years ago, I asked in the Jagoinvestor forum, “If anyone has achieved their financial goals using mutual funds, please share your experience”. To this, Manish responded, “It is unlikely that any forum member would have done this”. So I told myself, “Let me be the first person I know to have done this”. Thanks to the freefincal community, I know many more now.
When I started investing for this goal, money management basics were almost in place, except for term insurance, which I got a few months later (March 2010). So, from day one, investments were made with asset allocation in mind – 60% equity and 40% fixed income. Contrast this with how most of us (including me) plan for retirement: heavy on EPF/PPF and trying to catch on to equity exposure for several years.
During the last trimester of my wife’s pregnancy, I started thinking about how to start investing for the college fees. We are victims of our own experience. It took me 14 years after school to land a “permanent position”. Although my father retired in 1997 and my mother in 2002, both with meagre salaries, they never pushed me to get a job,
So, I wish the same for my son. Hence this post: What if our children never had to work?! Very few people (Subra being one of them) understood what I wanted to say there. Parents should provide a wide platform for children to blossom, find themselves, and experiment after school. Also, see: How can we help our children choose their careers?
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
So, after a rough estimate of UG + PG education, I decided on a target corpus when my son finishes school. My son would like to explore a career in physics/astronomy.
I exploited the fungibility of my mother’s cash flow with mine and opened a PPF account for her. I used this as the fixed income component for my son’s education goal.
As her health worsened, I had to consider the possibility of premature closure of the PPF account. So I opened one more in my son’s name. I neither claim these as “good decisions” nor do I recommend that. I am just stating facts.
To this day, neither PPF account has been maxed. The total investment per account per financial year is nowhere near Rs. 1.5 Lakh. If I had done this, the first casualty would have been asset allocation.
First, a SIP in HDFC Top 200 was started for the equity. I added HDFC Prudence and ICICI Dynamic Fund (now multi-asset) a few years later. The Top 200 was shifted to Prudence, and Mirae India Opportunities was added at some point. Again, I am merely stating facts. Unlike what many think, no complex calculations were involved in these decisions. Initially, I was planning for his marriage expenses separately, but later on, I merged it with the education goal.
Readers familiar with my yearly financial audits may recall the equity portfolio.
For an update on my retirement portfolio, see 16 years of Mutual Fund Investing: My Journey and Lessons Learned.
Equity: Asset allocation 58%. Overall portfolio return: 15.74%
| Fund | XIRR | Weight |
| HDFCBalAdv | 21.36% | 31.39% |
| ICICI Multi-asset | 19.46% | 48.05% |
| Mirae Largecap | 16.04% | 20.30% |
| HDFC Sensex | 32.77% | 0.26% |
HDFC Sensex fund is a recent addition with a small exposure (0.12%). See: My 13-year-old begins his investing journey with an index fund.
Fixed income Asset allocation 42%
| Fund | XIRR | Weight |
| ICICI Arbitrage | 6.08% | 24.91% |
| ICICI Gilt | 6.38% | 19.02% |
| Parag Parikh CHF | 16.00% | 16.92% |
| PPF | 39.15% |
I have kept the equity allocation close to 60% throughout these years. Rebalancing five times – three times into the PPF account and twice into an arbitrage fund (ICICI). Initially, I wanted to reduce equity to 55% and lower but backed off after accumulating fairly enough in fixed-income assets.
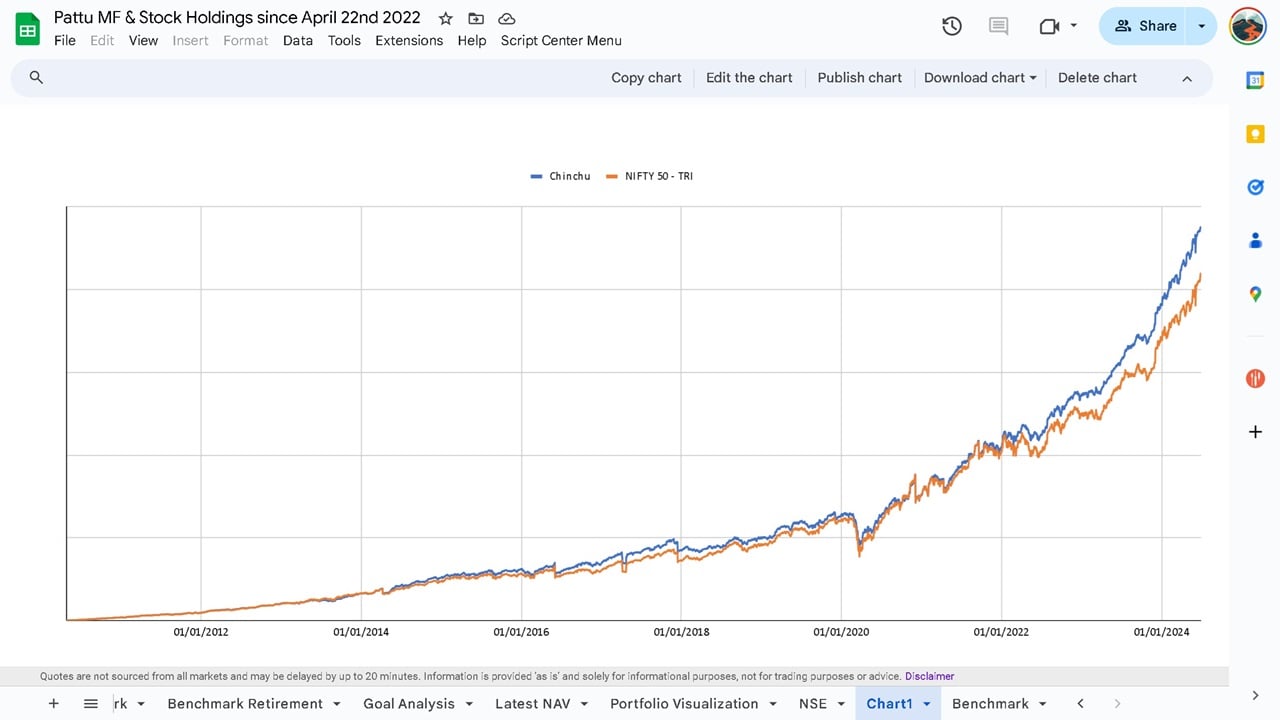
This is the normalized equity portfolio evolution since its inception (Jan 2010), along with an equivalent investment in Nifty 50 TRI. This was plotted with the freefincal portfolio tracker.
Lessons in this 14-year journey
- Time is crucial. I had 18 years before he finished school (because he is Jan-born). Starting allows us to take significant portfolio risk. This applies not just to the initial phase of the investment but also to the latter half.
- Luck is crucial. I have not seen a major market crash in this period.
- Goal-based rebalancing/re-alignment is crucial. I have been able to gradually allocate an amount equal to current PG expenses over the last few years. This allows me to have a high equity exposure despite the sequence of returns risk.
- Increasing the amount invested each year is a huge factor. I have increased my investment amount by about 15% each year. This is the hardest. Luck plays a big role here. Any big expense or break in employment can make things difficult.
- Focus is important. Focus on inflation first. Even 10% is an underestimate here. Despite that, people ask, “Is X child plan good? The “where to invest” question should start here.
- Investing each month based on a system is systematic investing. This investment can be manual or automated but must be based on a plan. Merely automating when money will be debited from a bank account is called SIP.
If you want to start systematically, use our robo-advisor tool to create a complete financial plan.
We are on Google News
Use this button to add freefincal.com as a preferred personal finance source on Google News.
Explore 1,400+ videos on YouTube!
Subscribe to get posts via email!
Join 32,000+ readers and get free money management solutions delivered to your inbox! (Link takes you to our email sign-up form)Join our WhatsApp Channel
Explore our products
🔥Join our community of 9000+ users! 🔥- Use our Robo-advisory Tool to create a complete financial plan! More than 3,500 investors and advisors use this! Use the discount code robo25 for 20% off. Plan your retirement (early, normal, before, and after), plus non-recurring financial goals (such as child education) and recurring financial goals (such as holidays and appliance purchases). The tool helps anyone aged 18 to 80 plan for retirement, plus six non-recurring and four recurring financial goals, with a detailed cash flow summary.
- Our Flagship Course! Learn to manage your portfolio like a pro to achieve your goals regardless of market conditions! More than 3,500 investors and advisors are part of our exclusive community! Get clarity on how to plan for your goals and achieve the necessary corpus no matter the market conditions! Watch the first lecture for free! One-time payment! No recurring fees! Lifelong access to videos! Reduce fear, uncertainty and doubt while investing! Learn how to plan for your goals before and after retirement with confidence.
- Join the freefincal investor circle! An exclusive space for investors, advisors, fintech employees and students to access financial planning and insurance tools, mutual fund and stock analysis tools, coding strategies and Excel macros for data extraction. 750+ members are now part of our investor circle.
- Increase your income by getting people to pay for your skills! More than 900 salaried employees, entrepreneurs and financial advisors are part of our exclusive community! Learn how to get people to pay for your skills! Whether you are a professional or small business owner seeking more clients through online visibility, or a salaried individual looking for side or passive income, we will show you how to do it by showcasing your skills and building a community that trusts and pays you. (Watch the 1st lecture for free). One-time payment! No recurring fees! Lifelong access to videos!
- Portfolio Tracker! Track your mutual funds and stock investments with our Google Sheet!
- We also publish monthly screeners for
Our Podcast: Let's Get Rich With Pattu
On Spotify: Let's Get RICH With PATTU! Every single Indian CAN grow their wealth! On Audible: Listen to the Let's Get Rich with Pattu Podcast
Listen to the Let's Get Rich With Pattu podcast on YouTube.
Now watch Let's Get Rich With Pattu தமிழில் (in Tamil)!About The Author
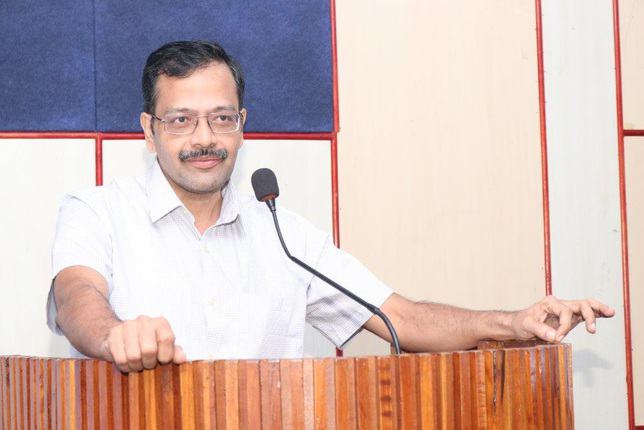
Dr M Pattabiraman giving a lecture
- Dr M. Pattabiraman (PhD) is the founder, managing editor and primary author of freefincal. He is an associate professor at the Indian Institute of Technology, Madras.
- He has over 14 years of experience publishing news analysis, research and financial product development. He has over 28 years of teaching and research experience. He is also a public speaker and keynote presenter.
- He is a patron and co-founder of “Fee-only India,” an organisation promoting unbiased, commission-free, AUM-independent investment advice.
- Connect with him via @pattufreefincal on X LinkedIn YouTube
- Pattabiraman has co-authored three print books.
This book helps you ask the right questions and find the right answers. It also includes nine online calculators to create custom solutions.
(2) Gamechanger: Forget Startups, Join Corporate & Still Live the Rich Life You Want. 
Both the boy and girl versions of "Chinchu Gets a Superpower".
Most investor problems stem from a lack of poor decision-making. We made bad decisions and money mistakes when we started earning, and we spent years undoing them. Why should our children go through the same pain? What is this book about? As parents, what if we had to groom one ability in our children that matters not only for money management and investing but for every aspect of life? My answer: Sound decision-making. So, in this book, we meet Chinchu, who is about to turn 10. The story follows what he wants for his birthday and how his parents plan it, while also teaching him key ideas about decision-making and money management. What readers say! 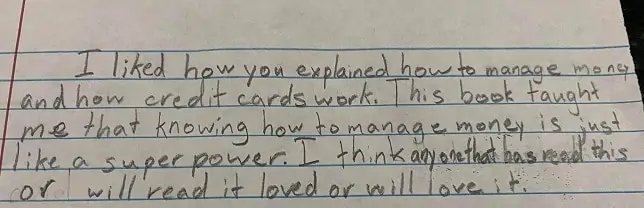
Feedback from a young reader after reading Chinchu Gets a Superpower!
Must-read book even for adults! This is something that every parent should teach their kids right from a young age. The importance of money management and decision-making based on their wants and needs. Very nicely written in simple terms. - Arun.
About freefincal & its content policy
Freefincal is a News Media organisation dedicated to providing original analysis, reports, reviews and insights on mutual funds, stocks, investing, retirement and personal finance developments. We do so without conflict of interest and bias. Follow us on Google News. Freefincal serves more than three million readers a year (5 million page views) with articles based only on factual information and detailed analysis by its authors. All statements made will be verified with credible and knowledgeable sources before publication. Freefincal does not publish paid articles, promotions, PR, satire or opinions without data. All opinions will be inferences backed by verifiable, reproducible evidence/data. Contact Information: To get in touch, please use our contact form. (Sponsored posts or paid collaborations will not be entertained.)Our publications
- Your Ultimate Guide to Travel. This is an in-depth exploration of vacation planning, including how to find affordable flights, budget accommodations, and practical travel tips. It also examines the benefits of travelling slowly, both financially and psychologically, with links to relevant web pages and guidance at every step. Get the PDF for Rs 300 (instant download)
- How to profit from content writing: Our ebook is for those interested in getting a side income via content writing. It is available at a 50% discount for Rs. 500 only!