Last Updated on December 29, 2021 at 6:09 pm
When it comes to managing our money, there are several questions to ask. (1) Should I do it myself? Can I do it myself? Or outsource it to a professional? (2) If I wish to outsource, who should I contact, what should I expect, what questions should I ask them? For the last six-plus years, we have effectively answered the second set of questions. Here is a simple test to answer the first set of questions.
Hundreds of freefincal readers are working with our list of SEBI registered fee-only financial advisors. They get unbiased advice free from conflict of interest and do not pay a fee linked to their networth (this is a proxy for commissions and should be avoided). Check out feedback from clients. Also available as a video.
So the “who should I contact?” question has been effectively answered. As for what to expect and what questions to ask them, please refer to these articles: Looking for a fee-only financial planner? Here is a list of questions to ask before you sign up and seven ways a fee-only financial planner will NOT help you!
So now let discuss a simple test to find out if you need to hire a fee-only advisor. Think of your investment portfolio (SB acct, PPF, real estate, stocks, MFs, etc.) as a clothes cupboard or closet or wardrobe. How does it look?
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
Like this?

Or does it look like this?
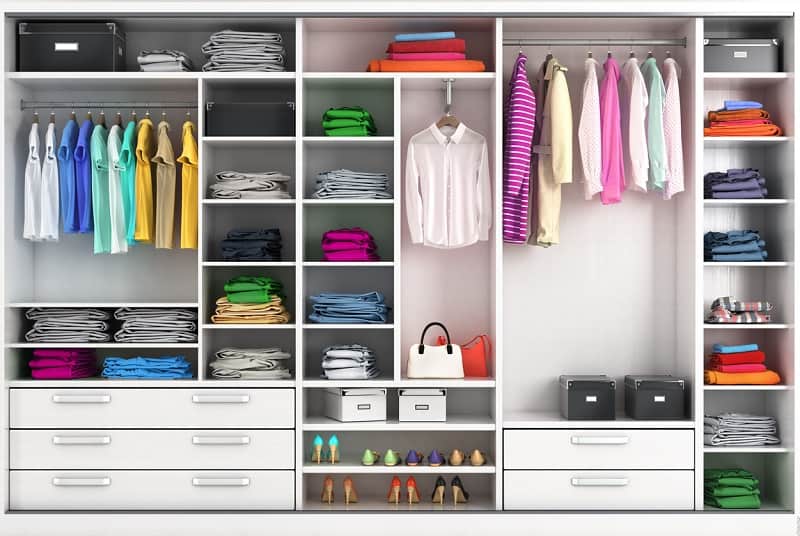
Or perhaps like this?

Anyone can tell you it is easy to go from an empty wardrobe to an organised wardrobe (will it stay that way is another matter!). Going from an untidy wardrobe to an organised one (and keeping it that way) is a lot harder.
Suppose your investment portfolio is practically empty (meaning you have just started earning and have not yet made any investment mistakes like saving tax!). In that case, you can happily become a DIY investor and do not need a financial advisor. That is, assuming you are willing to learn first and invest later!
If your investment portfolio is already organised, then you do not need an advisor either. It might surprise you, but many well-organised investors seek out a fee-only advisor for an unbiased second opinion.
If your investment portfolio is a mess, and assuming you want it set right, then can you clean it up yourself? Even if you can, do you have the time to do this? How soon can you make it organised? How much time can you spare for this? The answers to these questions will help you decide if you need the help of a financial advisor or not.
Ask this question (“do I need an advisor?” in a forum like the Facebook group Asan Ideas for Wealth, and you will see a few responses like, “financial planning is easy, it can be DIYed; there is no need for a financial advisor”. Often the reason for this is, investors who went from empty to organised closets assume anyone can set up an organised closet often forgetting how untidy most closets are.
Sure, that is in principle true, but very investors can pull it off, and even fewer have the time to sit and holistically think about their finances.
The situation is quite similar to how SEO (search engine optimisation) works. A new website can create relevant and helpful content to get traffic from Google without professional help. An older site would large be a collection of mistakes. Often a professional or a paid tool is necessary to get rid of these mistakes.
So do have a good hard look at your investment wardrobe (with your partner, if applicable) and ask, is this organised? If yes, do I need a professional second opinion? If no, can we sort this out ourselves or do we need help?
If you want help, this is the place to start: List of Fee-only Financial Planners in India (SEBI RIAs)