Last Updated on February 12, 2022 at 6:26 pm
Suman asks, “Sir, What return should I use while planning for retirement? I wish to retire by age 50. I am currently 30 years of age”.
Many people make two mistakes while planning their finances. The most common mistake is to assume equity mutual funds offer a 12% return and use that to compute the investment amount required. Unfortunately, this completely ignores asset allocation and the fact that one cannot invest 100% in equity.
Even those who take into account asset allocation, assume that the same weightage of equity and fixed income will persist until the need arises.
We must appreciate that the asset allocation will not remain fixed in time. For example, the 30Y old can start investing 60% in equity and 40% in fixed income.
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
This ratio should not remain the same until he hits 50. That would be like leaving the fate of his hard-earned money in the hands of luck. In order to combat unknown market returns (aka sequence of returns risk), the equity allocation must be continuously tapered throughout the investment journey.
Also, return expectations vary with inflation. In the early 2000s assuming a 15% equity return for “long term goals” seemed reasonable. Today 12% seems high! See: Ten year Nifty SIP returns have reduced by almost 50%
Considering taxation and lower inflation estimates over the long term, we recommend using 9-10% post-tax returns for equity. Many people are shocked by this. They say, “why should I invest in equity if I am going to get only 9-10%?”
The answer is, fixed income returns are also proportionately decreasing and will continue to fall over the long term even though there are some spikes due to inflation (and elections!).
So we recommend using not more than 7% from fixed income (even if tax free!) and 6% if the product is taxed.
So for a 60% equity and 40% fixed income mix, the expected portfolio return (approximately) is (60% x 10%) + (40% x 7%) ~ 9% (approx). This is only the initial asset allocation and return expectation.
The freefincal robo advisory tool auto-generates the recommended asset allocation values at different stages of the investment journey. The user can change all assumptions (returns, inflation etc.) The plot for a 30Y old wishing to retire at 50 is shown below (left image).
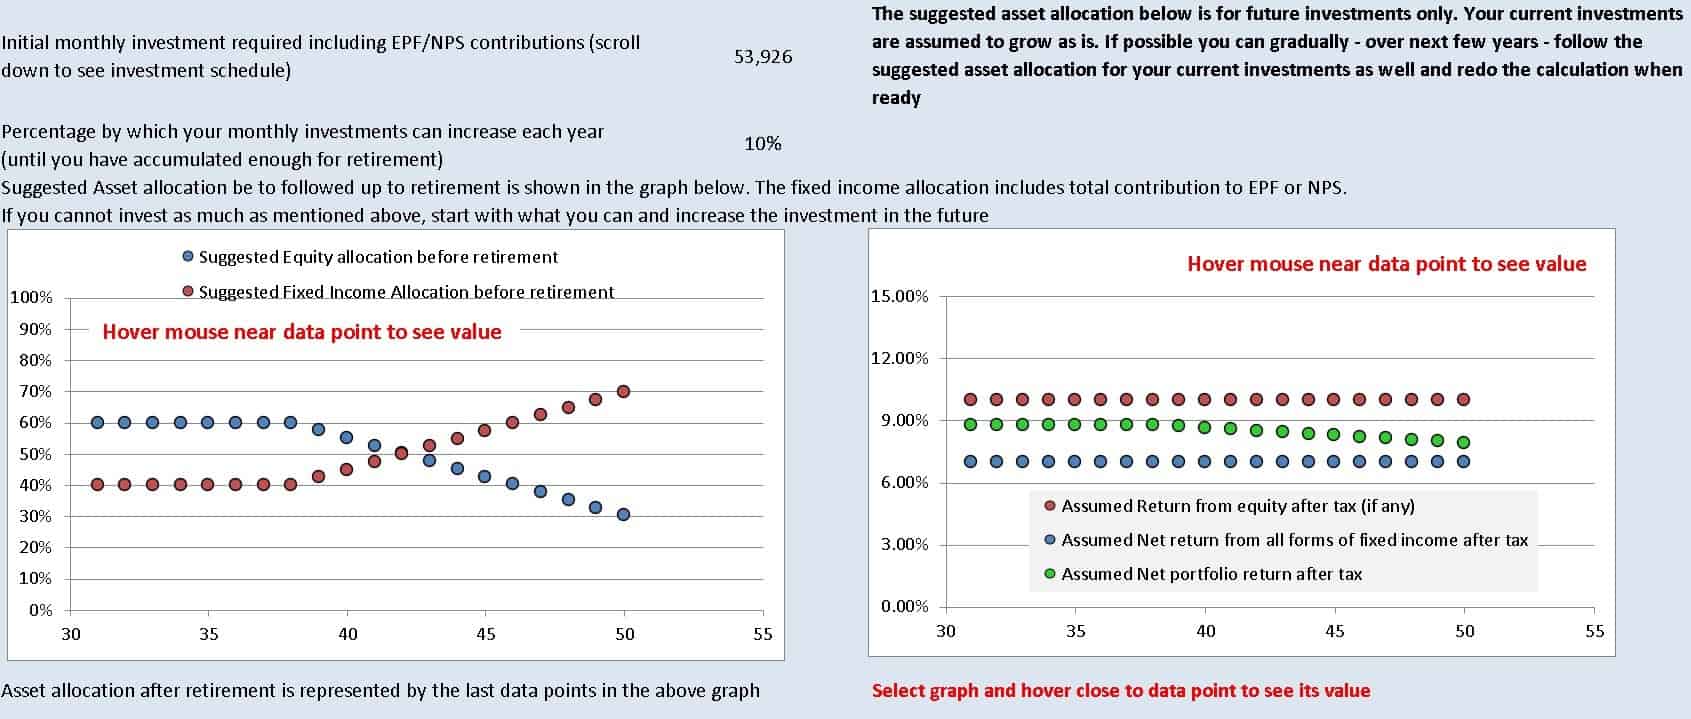
The equity allocation starts at 60% but starts decreasing gradually to 30% from the last 30s. This is to ensure the corpus is not affected by a prolonged stretch of poor returns. This model has been extensively backtested to handle a wide variety of market fluctuations. See for example: Why Understanding Sequence Risk is Crucial for Investing Success! And this video.
This also means that the returns from the entire portfolio change. This must be factored into the investment amount needed from day one (which the robo tool does).
The full retirement planning illustration with post-retirement inflation-protected income generation via a five bucket strategy is available here: I am 30 and wish to retire by 50 how should I plan my investments?
In summary, an investor must never assume a single return value either from one asset class or the entire portfolio for the entire investment duration. The asset allocation and how it varies will determine how the returns vary. We recommend having conservative return expectations from both equity and fixed income.