Last Updated on December 29, 2021 at 5:33 pm
If you sit and think about investment ideas without bothering to check how effective it has been in the past, many extreme strategies like buying only when the market is “low” or buying more often equals better averaging appear “intuitively” correct. When we try to validate them interesting results on SIP and lump sum investing emerge.
A couple of announcements before we begin. (1) Today marks the 8th birthday of freefincal. Thanks to your support the site has grown to serve three lakh plus visitors month with about 4.5-5 lakh monthly views. The Youtube channel is inching towards 28,000 subscribers. The site has now transitioned from a personal blog to a reportage news source with a research and product development component. What started as a personal quest is now fueled and driven by the community. Thank you.
(2) Readers may be aware of my FIRE (financial independence & early retirement) feature by Livemint in Mar 2019. They followed it up yesterday with Can your FIRE dreams get past the COVID-19 impact? Do take a look.
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
Now back to this story. This study is only meant to be illustrative in nature. Yes, a monthly SIP is the best suited for a salaried investor (and the AMC and the sale guys) and a quarterly SIP could work for an entrepreneur with uncertain income. This is not the focus of this article.
Suppose you decided to start investing in Jan 1999 in the Nifty 500 TRI Index. How would the results be today if you had invested
- Daily – 5320 transactions of Rs. 100 each
- Monthly – 257 transactions of Rs. 2070 each
- Quarterly – 86 transactions of Rs. 6186 each
- Half-yearly (bi-annually) – 43 transactions of Rs. 12372 each
- Annually – 22 transactions of Rs. 24181 each
- Biennially- (one in two years) 11 transactions – Rs. 48363 each
The total transaction amount over the 21.4 year period is the same (amounts shown above are rounded off). The valuation is done on May 18th 2020 and would be:
- Daily – Rs. 23,09,095 XIRR: 12.13%
- Monthly – Rs. 23,12,214 XIRR: 12.15%
- Quarterly – Rs. 23,32,537 XIRR: 12.17%
- Half-yearly – Rs. 23,60,460 XIRR: 12.15%
- Annually – Rs. 23,45,786 XIRR: 12.03%
- Biennially – Rs. 27,27,515 XIRR: 12.72%
Yes, the once in two years entry (biennial) is higher. We will get to this. Also, we have not rolled over the investment duration and have only considered a single sequence of return. Since most of the options are above are merely theoretical, the effort taken to roll this over will not be met with a significant change or commensurate reward for the time spent IMO. Different durations can be found in this previous study published seven years ago: Comparing SIP Returns: Monthly vs. Daily vs. Quarterly SIPs
First, let us focus on the rest. Notice that the final value and XIRR for daily, monthly, quarterly, half-yearly and even annual SIPs are pretty much the same.
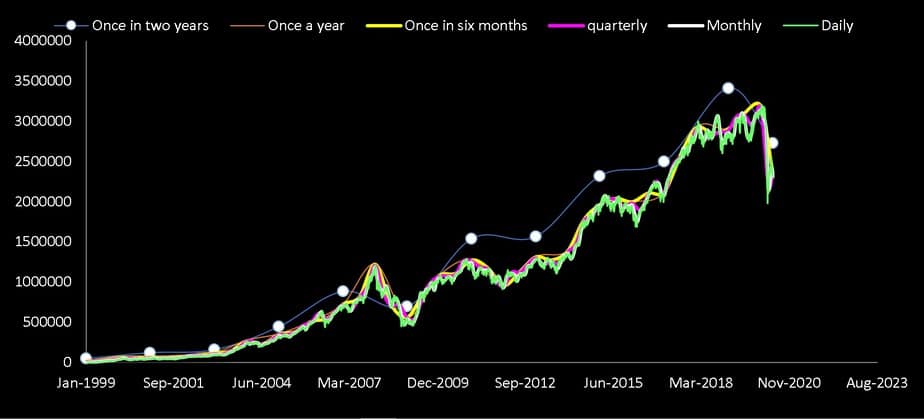
Ruppe or Dollar-cost averaging refers to how the buying price in a SIP varies according to market movements, Sometimes we get more number of units when the price is low and sometimes less when the price is high and these fluctuations “average out” over the long term.
While this is true, it does not mean the risk in the SIP is lowered as we have shown time and time again: 15-year Nifty SIP returns crash to 8% (51% reduction since 2014). This is again seen in the current study. The fate of a lump sum or SIP investment depends on the amount of investment facing the heat of the maker. Notice in monthly or quarterly or other longer duration SIPs, the significantly bigger amount than a daily SIP is invested upfront.
Just to be clear, upfront here means the following: Suppose we invest Rs. 100 daily. In a monthly SIP, the amount 30X100 would be invested on the first of the month. Suppose we invest twice a year, the amount 30x100x6 would be invested in the first month of the year. So we buy more units earlier when the frequency of the SIP decreases.
This shows that at least for long investment durations a lump sum vs gradual investment (STP) does not matter much. In this case, a lump sum of Rs. 12372 is invested in one-shot in the half-yearly SIP whereas in a daily SIP the same amount is divided and invested daily. After 21 years the differences are too small to worry about.
Whether you choose to average buying price daily/monthly/quarterly/half-yearly/yearly, over the long term, only the risk associated with the amount invested and market movements matter
Why is the once in two-years investment different? Notice from the above graph, the dot are far removed from the rest. The number of units purchased upfront is significantly more and the investment sways more than the other investments.
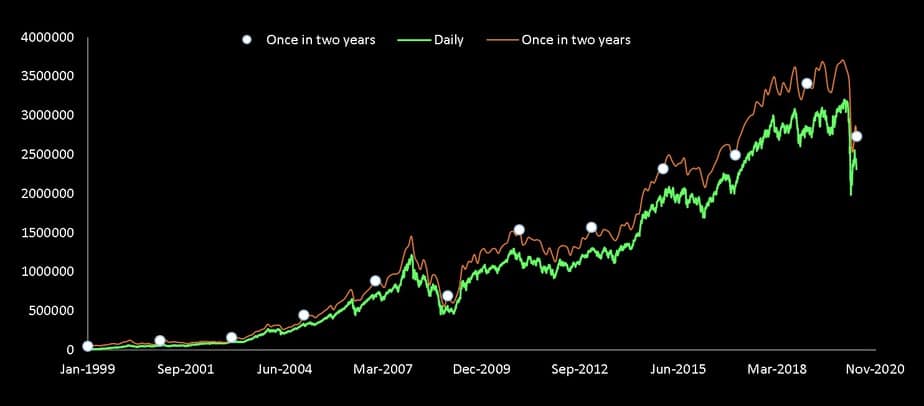
Since the market up movement dominates in this sequence of return, the higher number of units move up in valuation. If we try this in a bear market, the losses could be more. The good old “lump sum works better in a bull run” logic is in play here. Perhaps in a full-fledged rolling SIP study, the once in two-year SIP would underperform the daily SIP for some return sequences.
Though we keep buying more units earlier when the frequency of the SIP keeps decreasing, it is interesting that up to almost a year, the amount invested upfront compared to a daily sip does not seem to make much of a difference!
So what is the point? It is not about the frequency of purchase. The amount you invest and how soon you invest it makes a difference to your wealth. Duh!