Last Updated on September 5, 2022 at 4:49 pm
After the publication of our review of UTI S&P BSE Low Volatility Index Fund, we have received several requests from readers to compare low volatility indices with aggressive hybrid funds/indices.
Such a comparison may seem wrong at first glance. After all, how can we compare a 100% equity portfolio with a 65%-80% equity portfolio? However, a comparison of risk and reward helps us relatively grade and form the correct expectation from aggressive hybrid and low volatility indices.
The aggressive hybrid index considered here has 65% of BSE 200 and 25% of Crisil Composite Bond index. Unlike an actively managed aggressive hybrid fund, the equity allocation is fixed and the lowest possible to qualify as an equity fund for taxation. It must be kept in mind that at the time of writing, there are no aggressive hybrid index funds.
Let us start with the 5Y Rolling standard deviation of Nifty 100 Low Volatility 30 Index vs CRISIL Hybrid 35+65 – Aggressive Index vs Nifty 50 TRI. The standard deviation is a measure of much the monthly returns deviates from the average monthly return. This is a measure of volatility. Higher the value, the higher the volatility and the higher the likelihood of a deviation from an expected return.
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
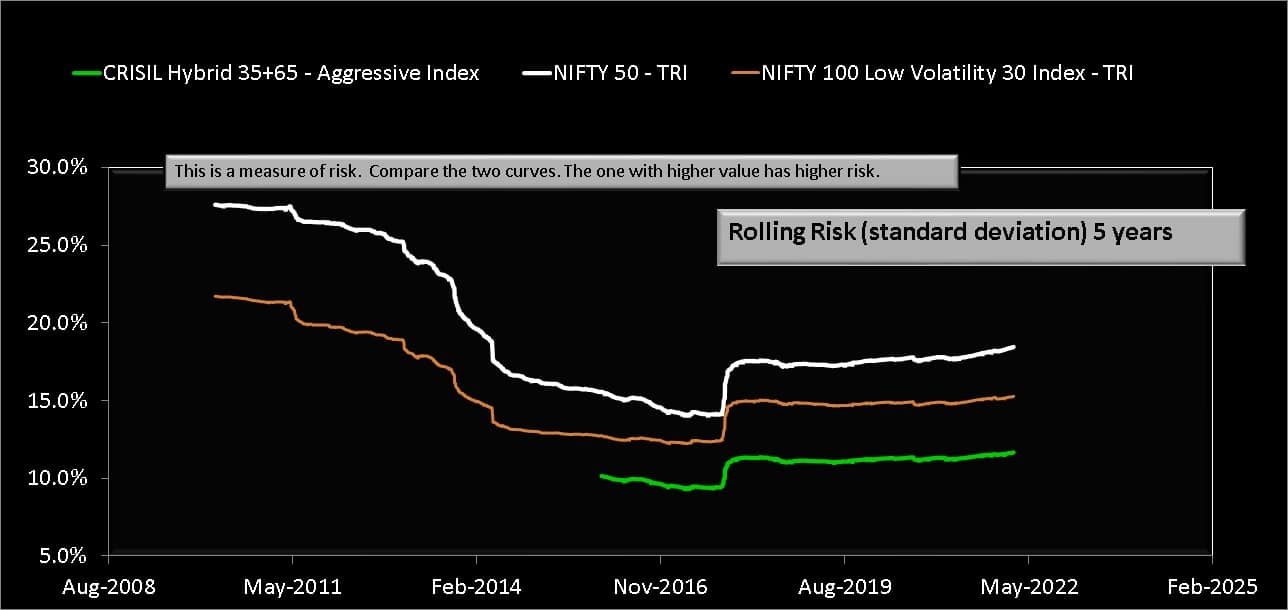
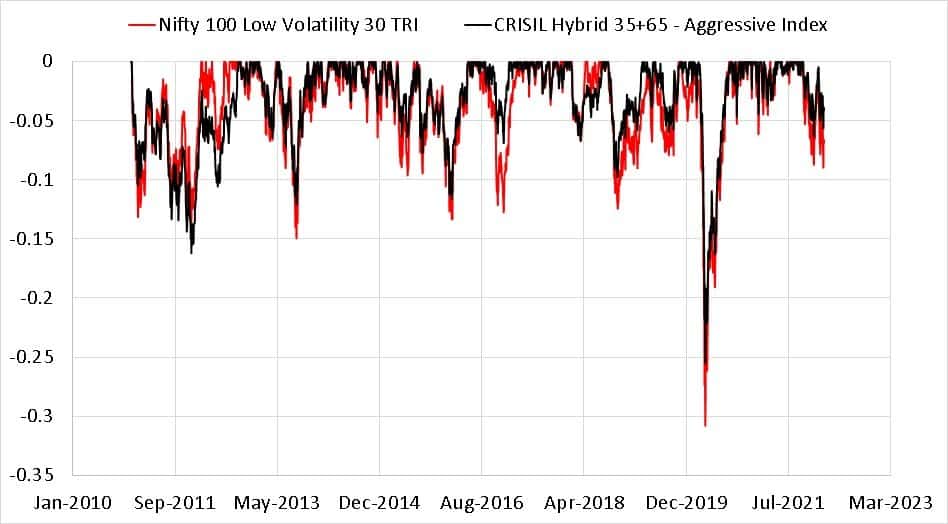
The hybrid index has the lowest volatility as it has only 65% of equity. The low volatility index falls in between the hybrid index and Nifty 50. For the same reason, the drawdown or the fall from a previous maximum is also lower for the hybrid index.
Next, the rolling returns over five years.
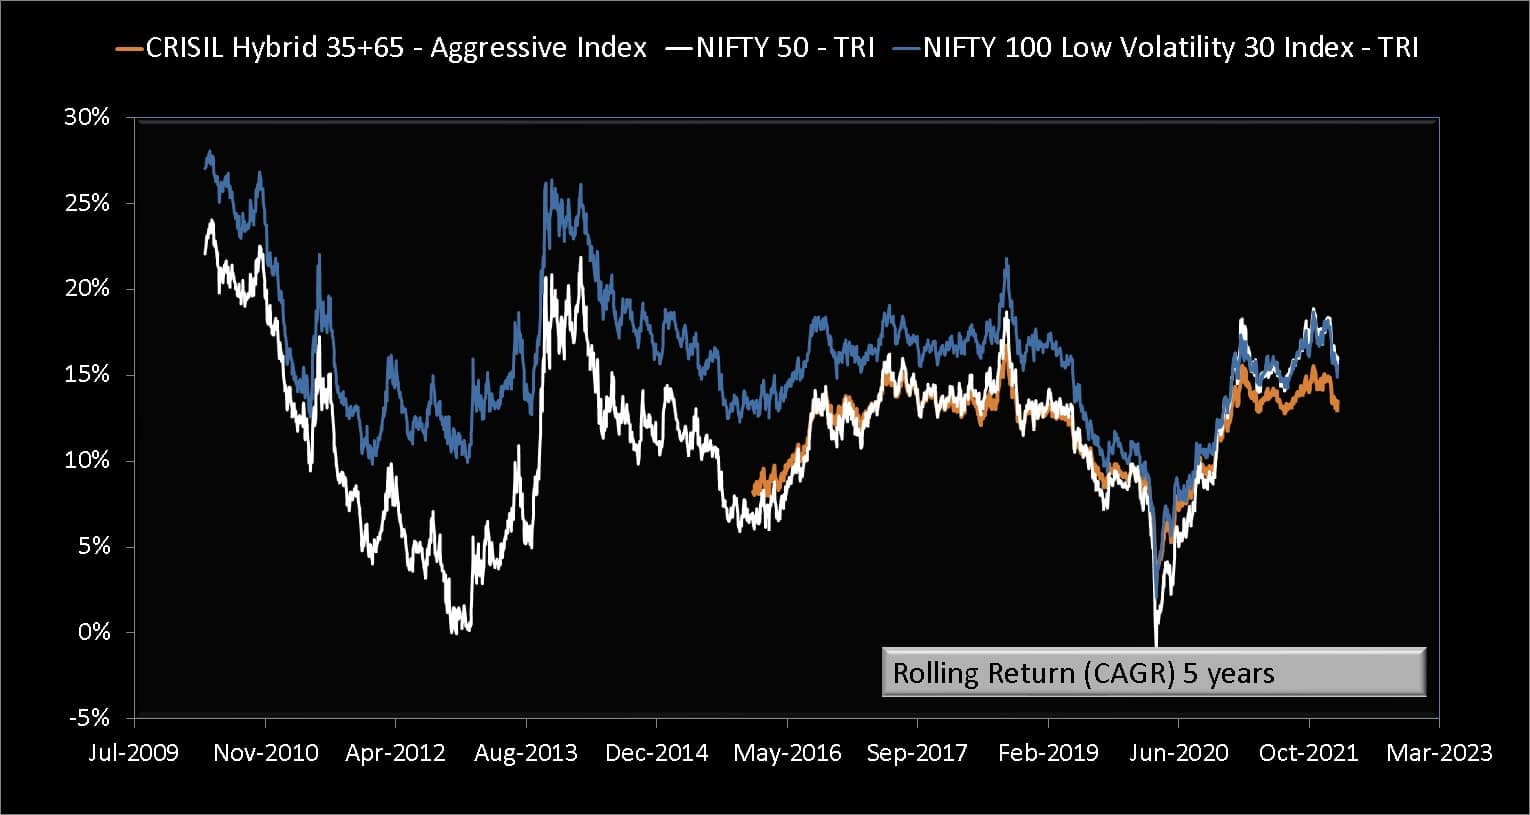
Notice that the hybrid index has a return typically comparable to the NIfty. This is the reason why asset allocation is referred to as a “free lunch”. That is just by substituting 35% of stocks with bonds, we have reduced the risk but not the return (typically). This means asset allocation (or in this case, an aggressive hybrid index) enables us to get a better risk-adjusted return (return obtained per unit risk taken).
The low volatility index has (so far) typically outperformed the Nifty over 5 years (and more) and it does so at a lower risk.
Now the question is, which index offers more reward for the risk taken. We shall compute the alpha wrt Nifty 50 and a risk-free rate of 4% a year.
Alpha = (Fund return – risk-free return) – (Benchmark return – risk-free return) x beta
Beta is the relative volatility wrt Nifty.
Since 31 Dec 2010 (the earliest date for which hybrid index data is available ), the low volatility index has a beta of 0.76. That is its volatility is only 76% of that of the NIfty. The hybrid index has a volatility of 0.63.
Alpha for the low volatility index is 1.69% while that for the hybrid index is 0.99%. Other risk-adjusted return measures are given below. For a simple understanding of these, refer to Visualizing Mutual Fund Volatility Measures and What is a risk-adjusted return?
| Metric | CRISIL Hybrid 35+65 – Aggressive Index | Nifty 100 Low Volatility 30 TRI |
| BETA | 0.63 | 0.76 |
| Sharpe | 4.80% | 5.07% |
| Alpha | 0.99% | 1.69% |
| Sortino | 7.50% | 8.04% |
| Treynor | 5.35% | 6.00% |
So the low volatility (so far) has been able to provide a bit higher reward for the risk taken.
Actively managed aggressive hybrid funds vs Nifty 100 Low Volatility 30 Index
We shall now compare the risk and reward of actively managed aggressive hybrid funds with the hybrid index and low vol index. To do this we shall plot the reduced return vs the reduced standard deviation (x-axis).
Reduced return = fund return minus hybrid index return
Reduced standard deviation = fund std dev minus hybrid index std dev.
The data below is for 3Y and 5Y. In this graph, the origin (x=0, y =0) represents the hybrid index. All other data is relative to this.
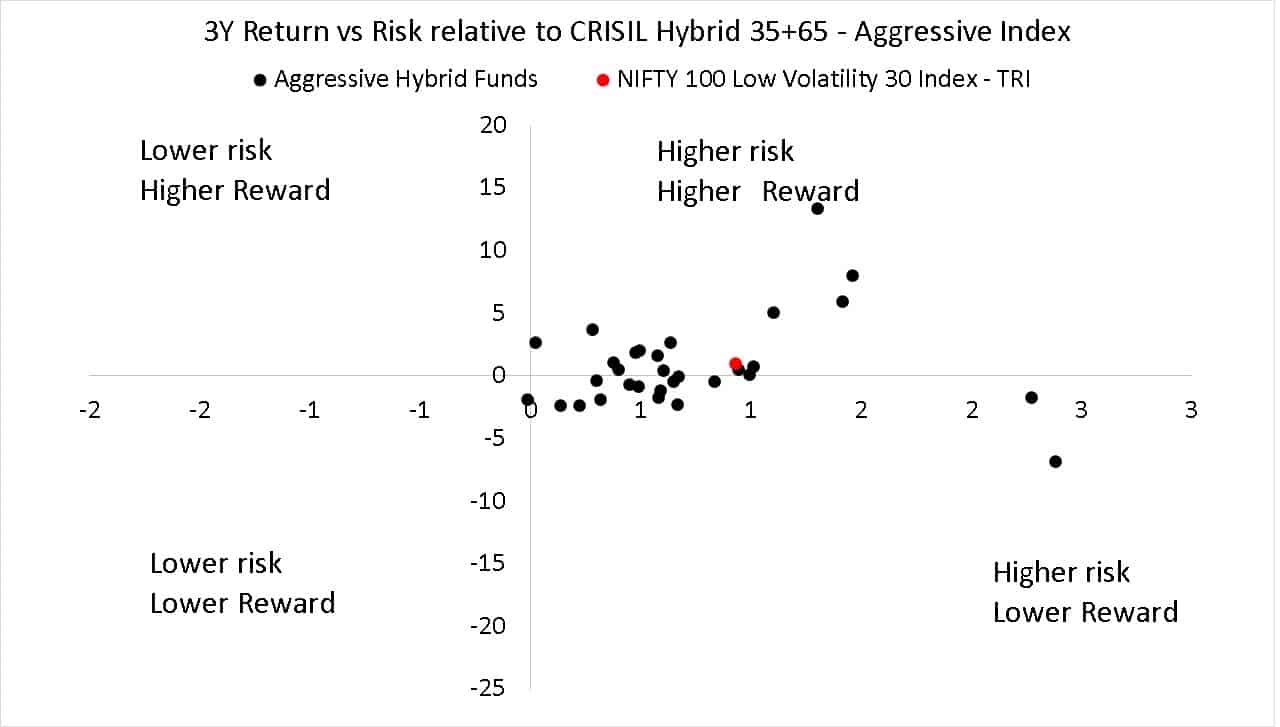
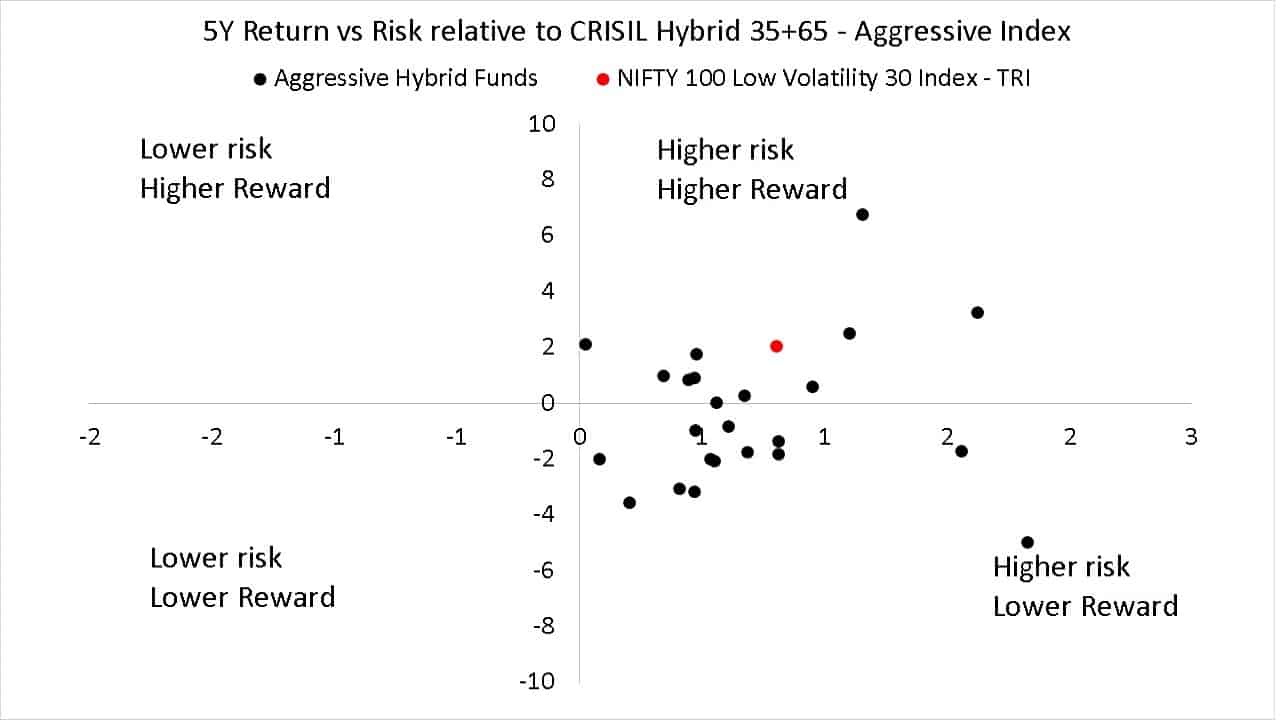
Over the last 3Y and 5Y, the low volatility index has outperformed the hybrid index. Although these graphs give the impression that many agg. hybrid funds have also done the same, caution is necessary.
According to the Equity Mutual Fund Screener Feb 2022, only 6 out 30 agg. hybrid funds have consistently outperformed the hybrid index at least 70% of all possible 3Y and 5Y duration from Jan 2013 to Feb 2022. So finding a “future” agg. hybrid fund performer is not practical.
Let us summarise:
If an aggressive hybrid index fund is launched is it a good replacement for a Nifty index fund? Certainly with usual caveats of expense ratio, tracking error and AUM. If such a fund is launched, I shall certainly consider investing in it.
Assuming we can choose between a hybrid index fund and a low volatility index fund, which is better? As mentioned earlier, a low vol index is a passively managed route to try and beat the market. A hybrid index does not have such a mandate.
So investors who wish to try and get better absolute returns (with better risk-adjusted returns as a min guarantee) can consider a low vol index. Investors who desired only guaranteed better risk-adjusted returns can opt for a hybrid index (when it becomes available) or settle with active agg. hybrid funds.
Is an actively managed aggressive hybrid fund better than UTI low volatility index fund? It is quite easy to choose such agg. hybrid funds based on past performance. However, it is unlikely to sustain in future. Also with the exception of one or two agg. hybrid funds (in search of AUM) many are likely to be at least twice as expensive as the UTI low volatility index fund.
While there is nothing wrong with investing in active agg. hybrid funds, there is no evidence to claim that they are better than a low vol index fund.