Last Updated on December 29, 2021 at 5:30 pm
In ‘The Intelligent Investor’ Benjamin Graham recommended a 50% stocks and 50% bonds allocation for the typical retail investor who cannot spare the time for deeper investigation into security selection and tactical asset allocation. We find out how this strategy has fared for Indian markets.
Most financial advisors (influenced by commissions) and most DIY investors are likely to term this asset allocation as conservative and are expected to bat for a much higher allocation to stocks for “long-term goals”. We have just seen how that well that turned out: 15-year Nifty SIP returns crash to 8% (51% reduction since 2014) and Ten-year SIP Return of Most Equity Mfs is now less than 10%
SEBI registered investment advisor Swapnil Kendhe explains why this 50-50 asset allocation recommended by Graham is prudent for pretty much all investors: Are you a conservative investor? Here is how you can grow your money smartly
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
Using the machinery explained in – This is how buying US stocks will affect your portfolio – we compare the performance of a 50% Sensex + 50% long-term gilts (I-BEX gilt index) with a 100% Sensex portfolio over 10-year investment durations.
Before we proceed readers must appreciate some important considerations. (1) When we mix stocks and bonds to create a portfolio, there is no way an ideal allocation can be determined. You can only draw one straight line between two data points.
If you mix white paint with red paint, you get continuous change from red to white going through different shades of pink. There is no way to tell which shade of pink is better. It is up to individual choices. So there is little point in comparing returns of a 50% stock portfolio with 70% stock portfolio.
With three asset classes – stocks, bonds and gold – it makes sense to hunt for a “sweet spot”. Whether we find it or not is another matter. More on this later.
With 50% stocks and 50% bonds, the portfolio has an appealing balance. It would suffer less during a market crash and long-term bonds could possibly gain and bolster the portfolio
(2) We are looking at a generic long-term portfolio with unchanged 50% stocks 50% bonds portfolio. Realistic individual portfolios will have a deadline (ideally a well-defined goal) and the asset allocation should be tapered down to manage risk. We shall not consider this aspect here. The lectures on goal-based portfolio management are dedicated to this singular cause.
(3) Data is only available from Sep 1996 and the Indian markets are constantly changing. It would be better if investors evaluate the 50-50 portfolio absolutely and not relatively (ie. compare with 70% stock portfolio etc.)
(4) The bond portfolio mentioned in this article refers to a long-term gilt mutual fund which carries significant interest rate risk. Rebalancing is essential to handle this risk.
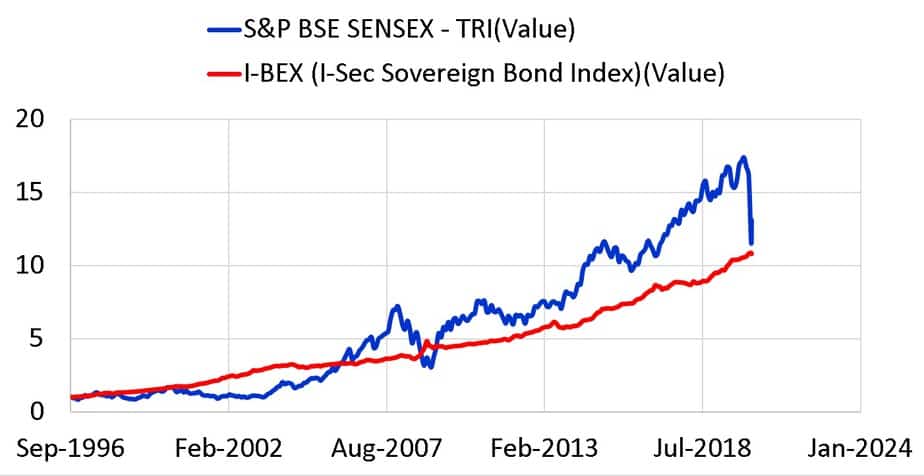
Instead of investing only in the Sensex (only the blue line) if we keep adding more and more of the red line, the volatility (for the above data set) will decrease. Returns will depend on timing luck. That is, it depends on the set of months over which the investment made.
Now consider a 10-year investment period ranging from Sep 1996 to Sep 2006 (1st run).
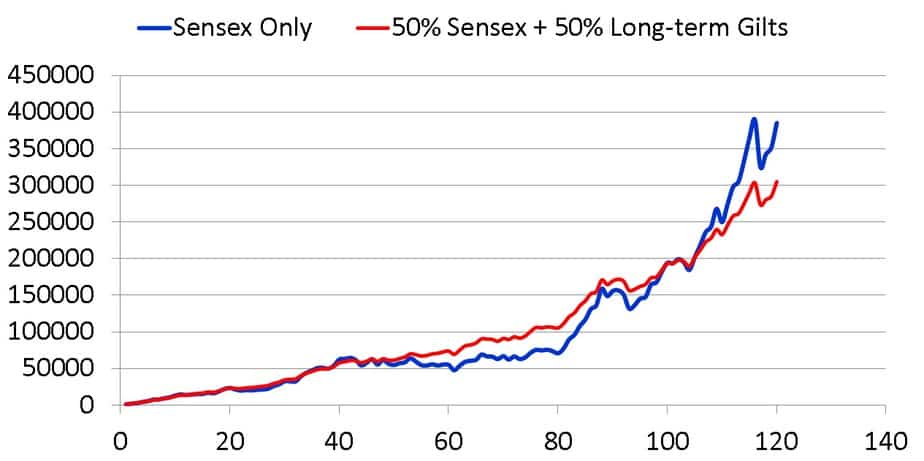
- XIRR 100% Sensex = 22.4% (1st run)
- XIRR 50:50 portfolio = 18% (1st run)
- Return difference: XIRR 100% Sensex – XIRR -50-50 = -4.4% (1st run)
- Beta = 84% (16% lower volatility than 100% Sensex portfolio)
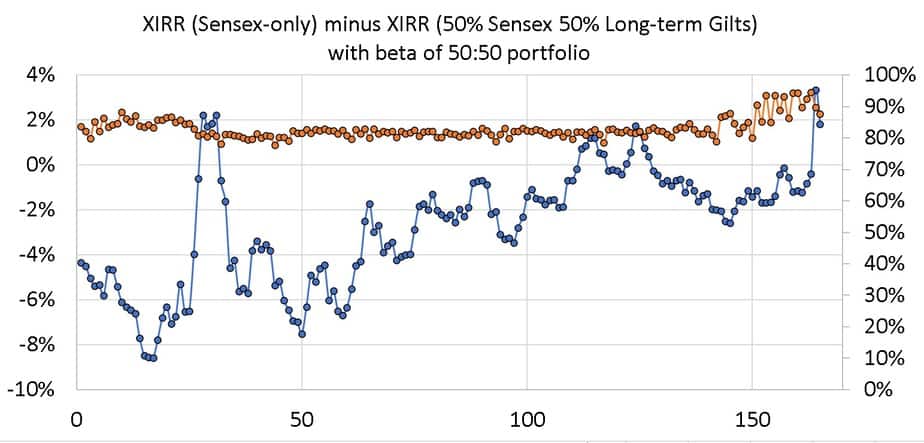
We can simulate 165 10-year runs from Sep 1996 to April 2020. The return difference and beta of each run are plotted below. The beta is fairly constant and therefore an average makes sense: 83%
The efficiency of the 50-50 portfolio is seen when the Sensex is plotted alongside the return difference. Every time the Sense fell, the 50-50 portfolio Did better.
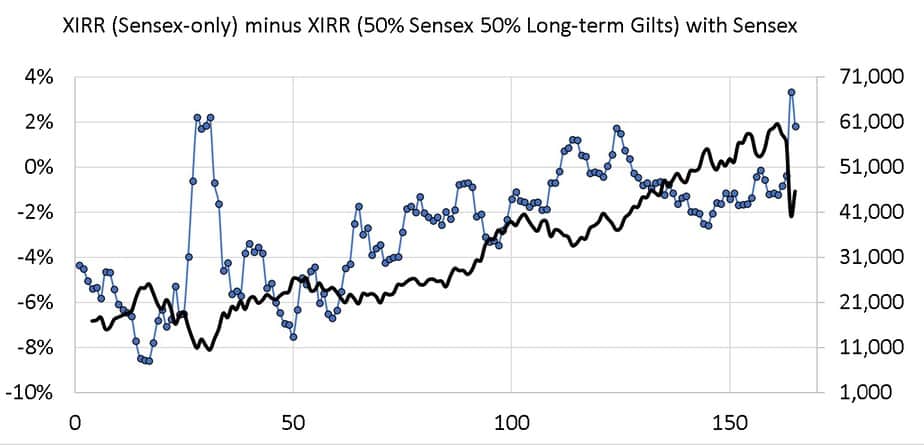
These are the absolute XIRR values.
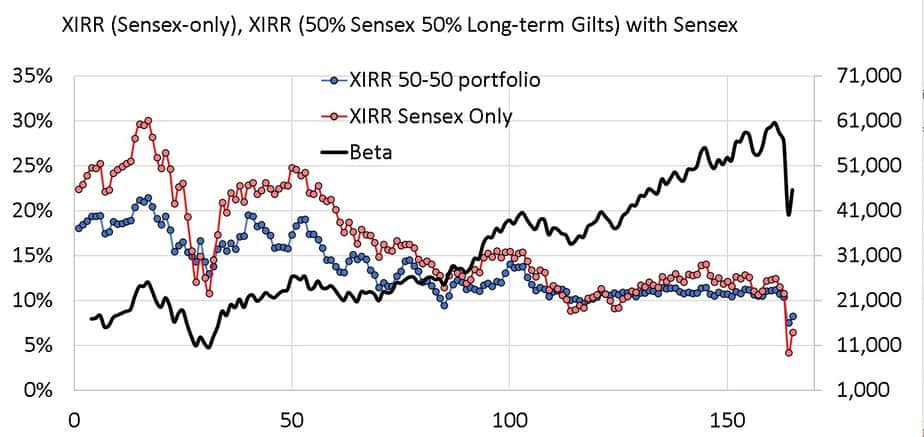
The 50-50 portfolio has given less than 10% returns only four times (out of 165 runs) in the past. While this means nothing for the future, the point of this article is, holding “only” 50% equity does not make you a conservative investor! In fact, it is quite prudent and Ben Graham’s recommendation works like a charm.
Of course, if we increase (or decrease) equity exposure from 50% we can narrow (or widen) the gap between the blue and pink dots in the above picture. With two asset classes, it becomes a matter of personal choice.
Since no can afford the investment necessary to beat inflation with a 100% fixed income portfolio, equity is necessary. The above results show that 50% of equity is good enough to strike a reasonable balance between what one can invest and the risk one can bear. HIgher equity allocations are not necessary.