Last Updated on March 3, 2019 at 10:23 pm
Download a free early retirement calculator for India with a checklist to retire early in India. You can also down a free e-book to plan early retirement. When I earlier asked “Is it possible to retire early in India?“, many readers assumed that I meant early retirement is not possible in India. All I wanted to convey was that excessive portfolio volatility is not the answer to combat the high inflation in India.
I followed that post with a friendlier illustration on “How much do I need to retire early in India?“. The message was still the same: when it comes to retirement, safety first! However, this was perceived more positively.
Now I would like to discuss a simple checklist which might help readers assess their preparedness for early retirement. The calculator is based on the above illustration.
What is early retirement?
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
It simply refers to cessation of regular employment. The person could still earn from consultancy (part-time or full-time) or by other means, but that income is considered temporary and is not included in the retirement plan. That is, we are financially in a position to work if and when we please.
Retirement planning is counterintuitive! Very few realise that earlier we retire, lower our retirement corpus! So planning for early retirement with a ‘low’ corpus could well be easier than planning for normal retirement with a ‘low’ corpus (more on this later).
Before we look at the checklist, some dont’s:
- Get rid of the notion of a “safe withdrawal rate”. If you must use the idea of a withdrawal rate, replace ‘safe’ by ‘initial’. Use this calculator to see why I say so: What Should Be Your Retirement Withdrawal Rate?
- Recognise the importance of “sequence of returns”. A few bad years in the stock market can destroy a retirement portfolio. I have the had the privilege of studying some robust early retirement portfolios and the equity component has never exceeded 50%.
- Even after you retire (early), you need to review the portfolio each year and determine if you can afford to stay retired.
If you wish to retire early, here are some tools that might help
Understand the corpus accumulation process:
Step 1: The low-stress retirement calculator (hopefully!)
Step 2: The even lower stress retirement calculator!
Step 3: Low-stress retirement calculator with flexible asset allocation (advanced version of step 1. If you want me to add this feature to step 2, leave a comment)
Step 4: Stress Test Your Retirement Plan
Understand the corpus management process:
Step 1: Generating an inflation-protected income with a lump sum
Step 2: Illustration: Generating inflation-protected post-retirement income
Step 3: Inflation-protected Income Simulator
Step 4: Try out the game: Retirement ‘Bucket Strategy’ Simulator
A checklist for early retirement in India
(perhaps anywhere!)
- Do I have an emergency fund which is at least equal to 12 months expenses, preferably 24 months? A part of it should be liquid and a part of it should grow in perhaps a ultra-short term debt fund for future use. The health of this fund should be reviewed each year.
- Do I have a health insurance cover for all my family members, be they dependents or not. Preferably an individual health cover for each.
- Do I need to continue my term life insurance cover after I retire? I think early retirees should continue and let the policy run its course, especially if it is an online policy.
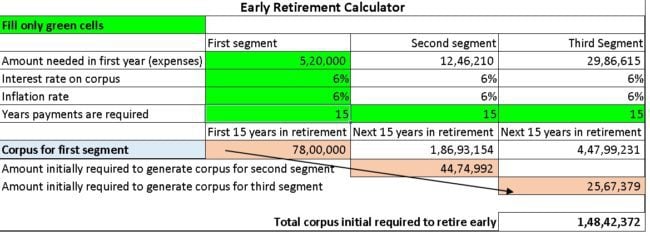
- Do I have enough money (call this C1) to allocate to fixed income assets so that I can receive an inflation-protected income for at least the first 15 years of retirement (years 1-15: called the first segment in the calculator).
- Do I have enough money (call this C2) to invest in a reasonably aggressive portfolio (not 100% equity) so as to generate a corpus with which I can receive inflation-protected income for the next 15 years of retirement (years 16-30: called the second segment in the calculator)
- Do I have enough money (call this C3) to invest in a reasonably aggressive portfolio so as to generate a corpus with which I can receive inflation-protected income for the last 15 years of retirement (years 31-45: called the third segment in the calculator)
- Total corpus required for early retirement = C1 + C2+ C3. Use the calculator (link below) to play around with this. I have used 10% as the portfolio return for the growth of C2 and C3. This is not offered an input, but you can change it yourself easily.
- This is just an illustration. An alternative but similar illustration can be found here: “How much do I need to retire early in India?“
- Have I used reasonable inputs for expenses, inflation and return in the calculator?
- Do I know what I am going to do after quitting my regular job?
- Do I know how I am going to use any part time income that I might generate?
- If I am going to travel or use funds for expensive hobbies, do I have a budget and a separate corpus or source for the same?
- Does my early retirement plan depend on my frugality? Do I understand that frugality is a luxury?! We may want to be frugal, but life should let us.
- Do I understand that life is uncertain, will not pan out like it does on an Excel sheet and that the best plans can go awry in an instant?
What do you think? Have I missed out anything?
Early retirement calculator
Here is a screenshot.
Download the early retirement calculator
Updated: Thanks to feedback from Atul.