Last Updated on July 14, 2026 at 10:18 am
Here is an analysis of a mutual fund SIP investment in which purchases are systematically ‘timed’ using an index PE.
I made this analysis following the suggestion of ET Wealth analyst/columnist Dr. Narendra Nathan (@drnarendranET) after (or amidst!) some fierce discussion over the usefulness of the SIP.
The SIP is a useful way to invest (something I have been doing for close to 8 years and intend to continue). However, we must recognise that there is a conflict of interest when a salesman says ‘do not stop your SIPs’ and ‘do not time the market’! For the AMC and the distributor, the SIP is a way to obtain constant income.
Dr. Narendra Narthan’s point is that the investor could do better if the Index PE is used as a guideline to ‘time’ investing. I had earlier written about this: Are Mutual Fund SIPs Suitable for Disciplined Long-Term Investors? where I refer to systematic PE based investing as SI-PE.
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
I write this post with a huge amount of trepidation. Running a backtest is quite easy. All it requires is interest and some Excel skills. Is it however, responsible? I am inclined to say no, especially because I tend to get emails that go,’you wrote XYZ on abc date and I started to invest like that‘. I do not have the health to emotionally handle that!
That said, it is also incorrect to not publish an analysis and present it as an ‘alternative’ with an open mind. That is all the following is.
THIS POST IS NOT A RECOMMENDATION TO STOP YOUR SIPS. I will not be held responsible if your investing habits are influenced by it.
Index PE based Mutual Fund SIP Investing
While the debate on SIPs was unfolding on twitter (my handle is @freefincal), Balaji Swaminathan was conducting an independent analysis on the Sensex PE. Therefore, I used his insights for the following study:
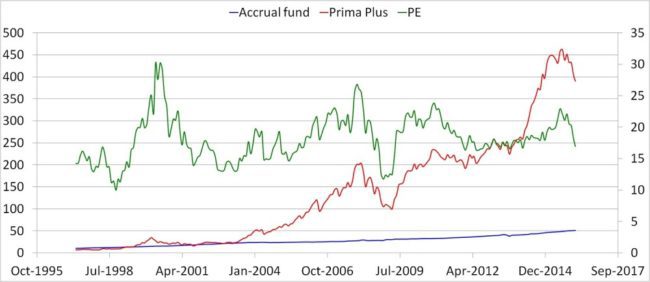
Franklin Prima Plus fund was chosen as the example of a diversified equity fund (across caps and sectors).
Franklin Dynamic Accrual fund was chosen as an example of a diversified debt fund (it has recently become more of a credit opportunities fund with only corporate bonds)
Analysis period: April 1997 to Feb 2016.
Monthly investment: Rs. 1000
Sensex PE rules:
PE >20, invest 100% in debt fund
PE <15, invest 100% in equity fund
15<PE<20, invest as per asset allocation (60% in equity fund and 40% in debt fund).
No fund switching or rebalancing was considered to avoid tax and exit load issues.
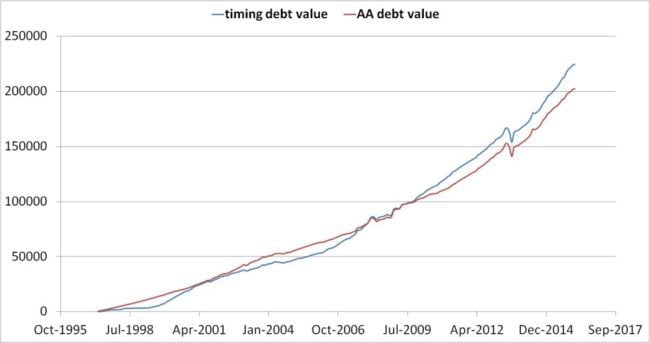
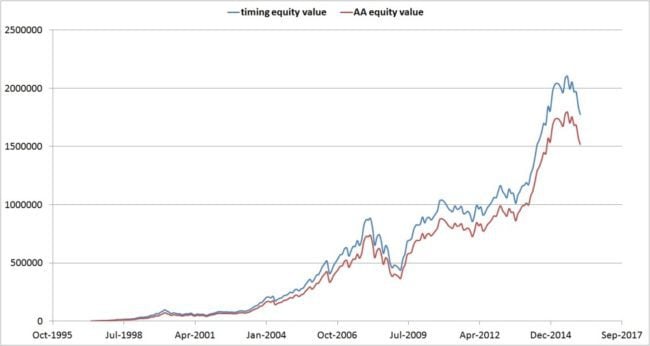
Here the ‘timing value’ represents the results of SI-PE and ‘AA value’ represents SIP with asset allocation: AA-SIP
It is not surprising that SI-PE has resulted in a larger corpus
SI-PE (Equity corpus): 17.76 Lakhs XIRR: 23.1%
AA-PE (Equity corpus): 15.2 Lakhs XIRR: 22.1%
Considering the amount invested, that is a significant different in corpus.
SI-PE (Debt corpus): 2.24Lakhs XIRR: (cannot be calculated*)
AA-PE (Debt corpus): 2.02 Lakhs XIRR: 7.93% (before tax)
If you think that is a big difference so be it. The way I see it, the extra corpus did not come free. You had to work for it. Easy to claim that PE is easy to track etc. but it is still non-zero time and effort.
Therefore, considering the completely automated way of investing, SIP has done quite well.
* XIRR sometimes cannot be calculated! Read more: IRR/XIRR – Excel – Limitations of Calculating Complex Cash Flow Returns
Wait just a minute!
The SIP duration above was 19 years! We don’t have enough data to perform a rolling SIP return analysis. So how about a 10-year SIP.
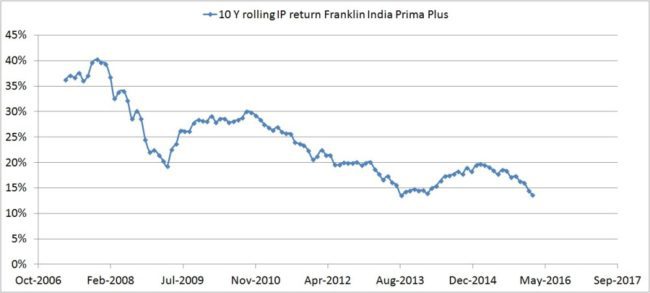
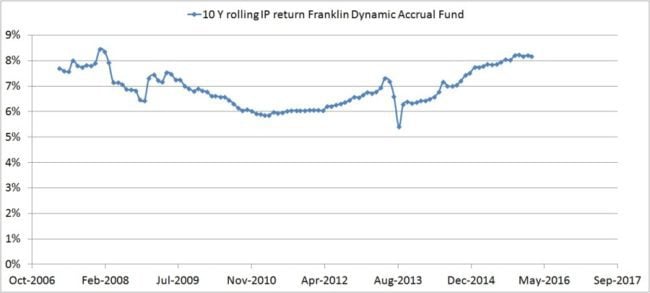
Rolling AA-SIP vs SI-PE analysis (10 years)
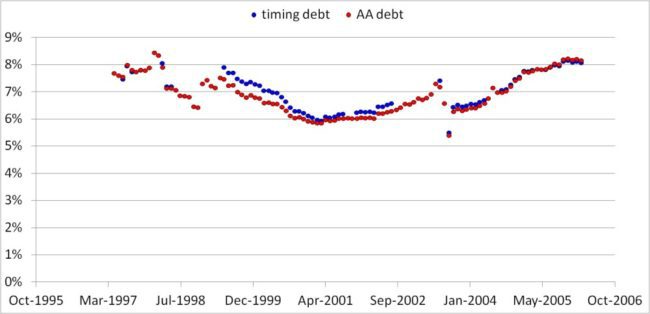
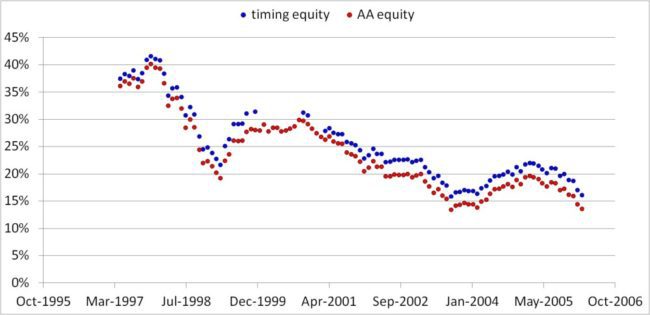
For some intervals, the SI-PE XIRR could not be computed. So clearly SI-PE is superior to AA-SIP. It is worth the effort though?
At least for the assumptions made here, SI-PE returns are as volatile as AA-SIP returns. So timing the market (in this instance) does not reduce rolling SIP volatility.
There is a clear and definite benefit of investing based on the index PE values (you can choose index you like – perhaps BSE or NSE 500 to get a broader market perspective). However, there is also an effort and discipline involved. Quite easy to backtest. Not so easy to implement in real life.
To be fair, the good old SIP does not fair too poorly at all.
Wait a minute, how about
PE >22, invest 100% in debt fund
PE <15, invest 100% in equity fund
15<PE<20, invest as per asset allocation (70% in equity fund and 30% in debt fund).
No fund switching or rebalancing to avoid tax and exit load issues.
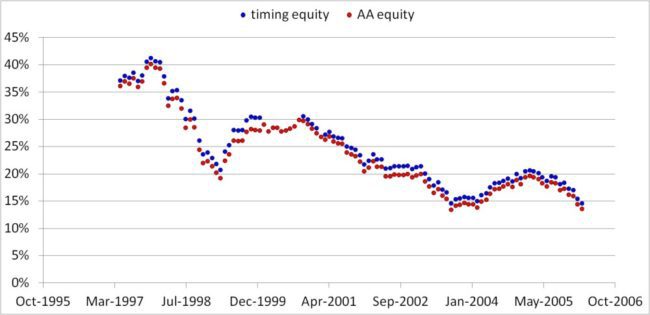
Results are not too different!
We must recognise that these PE limits are based on limited hindsight and we could be wrong.
In this study I changed the asset allocation of the amount invested alone. Perhaps I should have changed the asset allocation of holdings. Perhaps I should not have invested in the debt fund and waited for PE to correct and then invested as a lump sum. Perhaps, perhaps, perhaps ….
Can I make significantly reduce return volatility associated with the SIP by ‘some timing method’? I won’t bet on it.
I still think that a SIP done with asset allocation in mind, with periodic reviews and de-risking prior to a goal will work. ‘Timing’ is likely to provide a higher corpus and better returns, but at a price.
At the end of the day it is ‘personal’ finance. However, it should not be ‘clouded’ by conflict of interest in the name of behavioural finance, if can catch my drift…
My key takeaway: If I want to reduce portfolio volatility, I must change the asset allocation of existing holdings. I want only higher returns but with same volatility, change only asset allocation of future investments, and do not touch existing holdings.