Hi, this is Sahil. This is the way I track my personal finance-related metrics. This should be helpful for DIY investors and should help them to focus on what and how to measure.
About this series: I am grateful to readers for sharing intimate details about their financial lives for the benefit of readers. Some of the previous editions are linked at the bottom of this article. You can also access the full reader story archive.
Opinions published in reader stories need not represent the views of freefincal or its editors. We must appreciate multiple solutions to the money management puzzle and empathise with diverse views. Articles are typically not checked for grammar unless necessary to convey the right meaning to preserve the tone and emotions of the writers.
If you would like to contribute to the DIY community in this manner, send your audits to freefincal AT Gmail dot com. They can be published anonymously if you so desire.
Please note: We welcome such articles from young earners who have just started investing. See, for example, this piece by a 29-year-old: How I track financial goals without worrying about returns.
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
Now over to Sahil. It is quite rate to see someone track their portfolio as meticulously as Sahil does.
How much do you earn, spend and invest?
1. Firstly, every person should know what they earn (post-tax) every month and the monthly salary growth rate. Secondly, how are you spending and/or investing from the salary? Salary can either be 1) Spent on expenses 2) Paid off an EMI, and/or 3) Saved/Invested. Here’s how I track these.
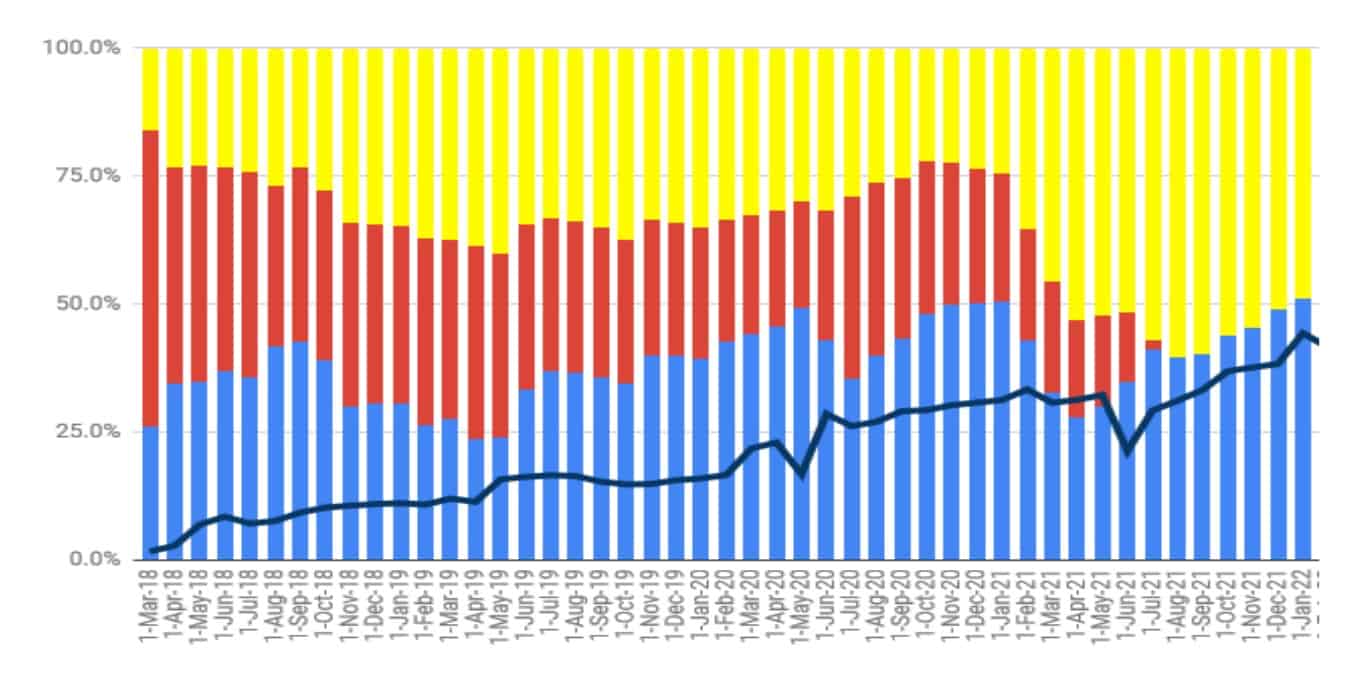
- I am using a dated graph as I don’t want to share the latest numbers.
- The black line shows my 12-month moving average post-tax earning for any respective month (scale on the vertical right axis, redacted to ensure privacy). My salary has grown decently in the last 4-5 years and can be seen here. I take 12 months rolling/moving average to smoothen any spikes.
- The blue portion is the % of earnings that go to investments, red portion is % of earnings gone to EMI payments and the yellow is % spent. Again 12-month moving average. From Apr’17-Mar’18, (See the first bar graph) I spent ~25% on investments, ~60% on EMIs and the remaining ~15% on expenses. Now, given EMIs are over, I can save/invest more than I spend.
- Ideally one should expect continued growth in the black line, an increase in the blue bar height meaning you are saving a bigger chunk of your salary, and thirdly, <35% spent on expenses.
2. In extension to the above, I also track the 3-year CAGR for your moving/rolling average salary, expenses, and investments. It gives you further evidence of how you are doing both earning and spending-wise. An increase in the height of the yellow bar as above might indicate that you have a lifestyle creep and your expenses CAGR is higher than your salary CAGR. This happened with me in FY22, primarily due to one-time events. My expenses CAGR is back to being lower than my salary CAGR in FY23.
- 3-year rolling Salary CAGR (FY23): X% (redacted for privacy)
- 3-year rolling Savings CAGR (FY23): X%+13%
- 3-year rolling Expenses CAGR (FY23): X%-15%
3. I also started tracking expenses in various buckets. But it is too tedious and doesn’t seem to give many insights. I think whenever I’m closer to my FIRE, I’ll start tracking this again to pinpoint expenses during FIRE better.
Asset Allocation and Where to Invest?
Next part- Asset Allocation or where do I save or invest? I don’t maintain a separate emergency fund and have a unified portfolio. It is easier for me to calibrate and measure. I added REIT and Gold (SGB) last year, so not sure where I will take it. REIT taxation changes have made it more complicated. Overall, my target is to reach 50-55% in equity, 10-15% in REIT and 30-40% in Debt. Once I reach ~50% in equity, I’ll decide if I want to change my target asset allocation. My asset allocation as of today is as follows:
- Savings and FD:~10%
- Debt MFs: ~20%
- Debt Illiquid (PPF + EPF + NPS-C/G): ~30%
- Equity (MFs+ Stocks+ NPS-E):~36%
- Gold (SGB): ~4%
- REIT: ~5%
2. Here is a bit more information on the instruments used:
- Debt MFs are a mix of short-term (liquid/arbitrage/UST/Savings) and some medium-term/TMF Debt MFs. Short-term Debt MFs double up as emergency funds and rebalancing/ switching to equity, while medium-term/TMF were for locking the yields at the end of FY23. Given the change in tax structure in Debt MFs. I will likely rethink before adding more to it in FY24.
- I ensure that the illiquid part of the portfolio, i.e. EPF, PPF, NPS, doesn’t become too large (>30-35%) because what use is the money if we can’t take it out during times of need? This used to be higher earlier and is going down now.
- I have NPS Tier-1. Currently, NPS is at 75% equity, and I intend to maintain it until I hit my target equity allocation. After that, it would be a nice tool to move between equity and debt in NPS to change asset allocation without paying any taxes.
- The equity portfolio is majorly driven by MFs (80%+), NPS-E and some Indian direct equity.
- The target amongst the equity portfolio is to have ~65% India and ~35% US weight. I’m at ~15% US weight currently. A mix of PPFAS flexi cap and Motilal S&P 500 makes up the US weight. Given the change in tax rules, I will again rethink this and stop new investments in S&P 500
- Target in the India portfolio is to have ~10-15% small cap, ~20-25% mid cap and remaining large/giant cap. I track it through value research. I have a 5% small cap and a 25% mid cap, so broadly inline.
- MFs- PPFAS Flexi cap, Motilal S&P 500, SBI small cap, One mid cap, Edelweiss Balanced advantage. Though I also have some N50 and NN50, I will not go fully passive.
- Stocks: 10 stocks. Likes of ITC, HDFC Bank and a few new-age companies
- Gold exposure via SGB and REIT exposure via three listed REITs
I measure the standard deviation and rolling returns of each equity MF as a basket. I try to remove MFs which are not beating the indices in either return or risk.
- Here’s the two rolling 12 months average return of my equity MF against N50 TRI and NN50 TRI for several months. Just for clarity and explanation on how to read the below table: My Equity MF portfolio gave a 29.3% return from Jan-Dec’21 against ~26.2% return for NN50 TRI.
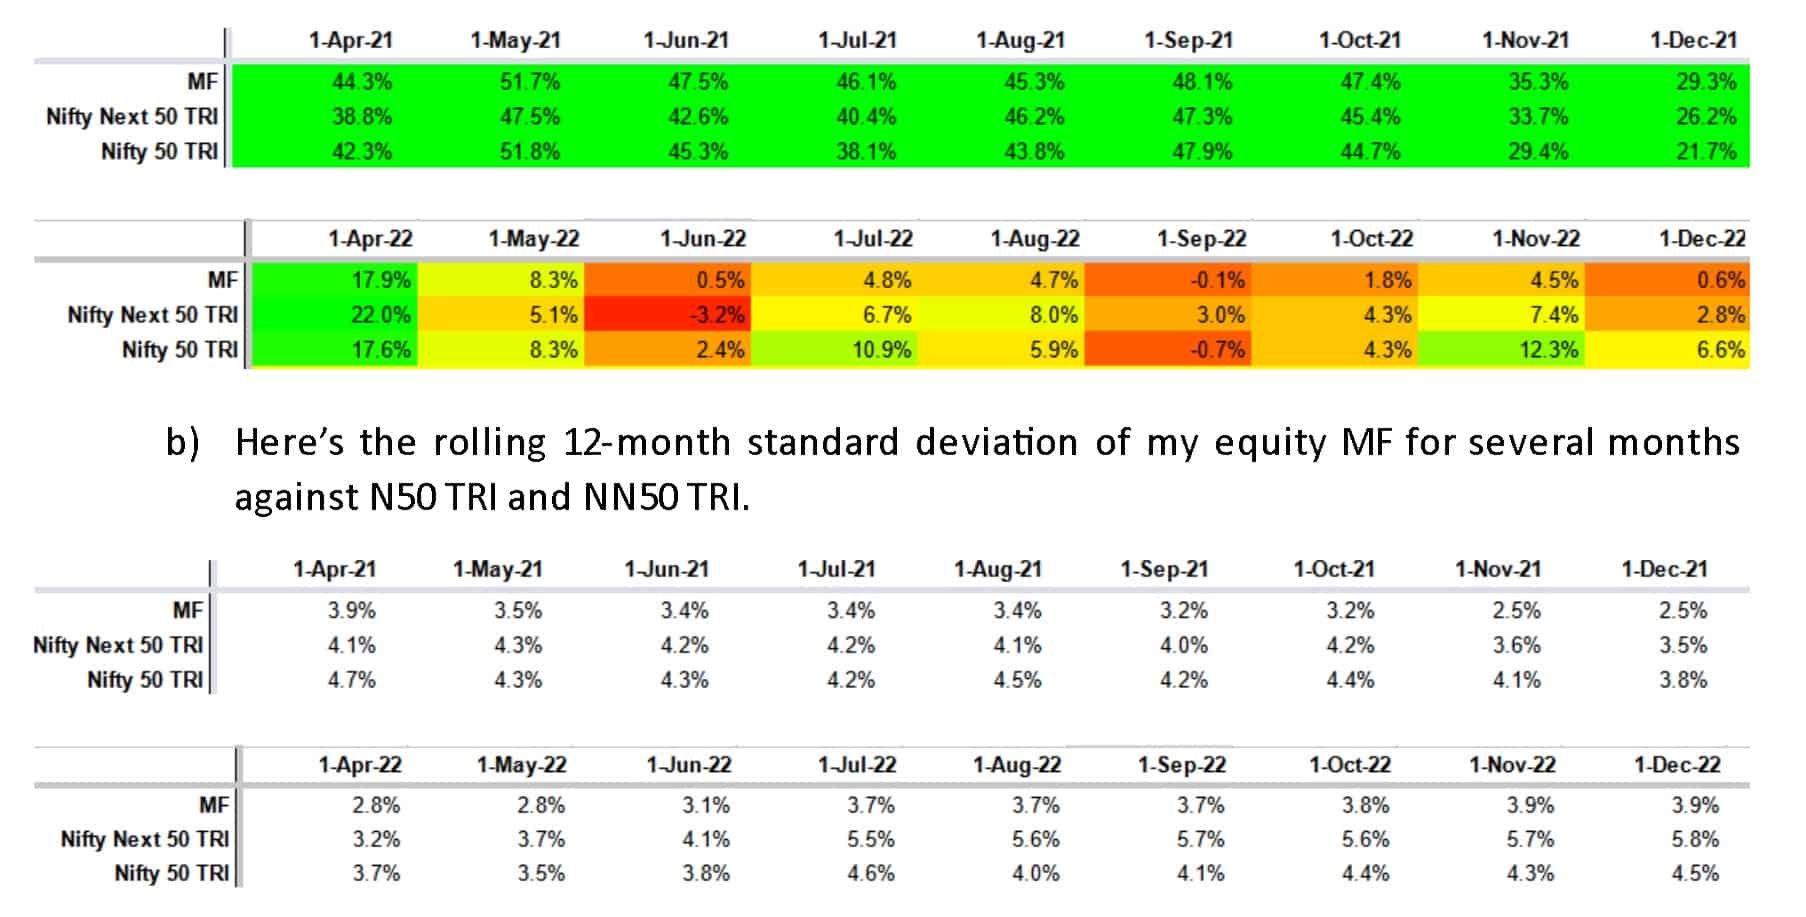
I have been able to beat the indices both in return and volatility in FY22 but in FY23 only in volatility. I am fine with this result as I am happy with ~10% lower risk than Nifty50. Mind you, this is tough and not attributed to me but to the performance of chosen MFs
1. XIRR
- Equity MF: ~13.0% (Since 2014, Major investment since 2018)
- Debt MF: ~6.0% (Since 2017)
- NPS: ~11.5% (Since 2019)
- SGB: ~17% (Since 2020)
- REITs: (~3%) (Since 2021)
- PF: ~8%
- PPF: ~7.5% (Since 2015)
Money saved: No FnO, No trading, No LIC endowment/ULIP plan
Net worth (NW) and its measurement
1. All this saving, investment, asset allocation and fund selection is fine, but how do you bring it together?
- An example: NW on 1-Nov-21: 100; Nov-21 salary: 10 and expenses: 6; NW on 1-Dec-21: 105. Now, NW has increased by 5 units in 1 month; 4 units (80%) can be attributed to salary savings, and the remaining 1 unit (20%) can be attributed to asset increase.
- In last 1 year, my NW has increased by 40%+ and about 90% growth came through salary savings and the remaining only 10% through asset returns (capital gain + interest etc.). As we become older, majority growth should come from asset returns. Do note, in a year of negative/zero equity returns like FY23, asset returns could be negative as well, which has happened with me twice.
- Overall, till date, ~87% of my net worth is from human capital (salary-expenses) and only ~13% if from financial/asset returns.
2. I’m at 5-10 times (I don’t want to share the exact number) of annual expenses wrt the FIRE goal. I want to reach 30-40x in the next ten years.
Reader stories published earlier:
As regular readers may know, we publish a personal financial audit each December – this is the 2020 edition: How my retirement portfolio performed in 2020. We asked regular readers to share how they review their investments and track financial goals.
- First audit: How Suhas tracks his MF investments and reviews financial goals.
- Second audit: How Avadhoot Joshi evaluates his investment portfolio.
- Third audit: How a single mom is on track to financial freedom
- Fourth audit: How Gowtham started goal-based investing & took control of his money
- Fifth audit: Why my financial independence & early retirement plans were postponed by four years
- Sixth audit: How Abhisek funded his marriage & is on track to financial freedom.
- Seventh audit: How Rohit’s early struggles defined his investment journey
- Eighth audit: Why my investments are still on track despite job loss and lower-income
- Ninth audit: How a retirement planning calculation scared me to take action
- Tenth audit: I made several investment mistakes but have turned my life around.
- Eleventh audit: My net worth doubled in the last financial year, thanks to patient investing!
- Update: How I achieved investing nirvana.
- Twelveth audit: My financial journey: from novice to goal-based investor.
- Thirteenth audit: My journey: from a negative net worth to goal-based investing.
- Fourteenth audit: From Fixed Deposits to Goal-based investing in MFs.
- Fifteenth audit: My 10-year financial journey – mistakes made and lessons learnt.
- Sixteenth audit (part 1): How I achieved financial independence without mutual funds or stocks.
- Sixteenth audit (part 2): Lessons from my financial independence journey and future investment plans.
- Seventeenth audit: How I plan to achieve financial independence and move to my native place
- Eighteenth audit: I used the current bull run to reduce my mutual funds from 14 to 4!
- Nineteenth audit: How a conservative investor created his financial plan
- Twentieth audit: I plan to achieve financial independence by 46; this is my master plan
- Twenty-first audit: I have made many investment mistakes but am on course to financial independence by 45.
- Twenty-second audit: I felt worthless six years ago but have achieved financial stability today
- Twenty-third audit: My financial journey was directionless until age 40: this is how I made up for lost time
- Twenty-fourth audit: Why I increased equity MF investments by 275% and reduced PPF contributions.
- Twenty-fifth audit: How I track financial goals without worrying about returns
- Twenty-sixth audit: I am 24 and started investing 1Y ago, but what am I investing for?
- Twenty-seventh audit: How we plan to achieve a retirement corpus 50 times our annual expenses.
- Twenty-eighth audit: I thought equity investing was a gamble, but now I aim to hold 60% equity for retirement
- Twenty-ninth audit: My journey: From 5 lakhs in debt to building a corpus worth six years in retirement
- Thirtieth audit: My investment journey: From random purchases to a goal-based portfolio
- Thirty-first audit: My investment journey: from product-driven to process-driven
- Thirty-second audit: How a young couple is trying to balance travelling and investing
- Thirty-third audit: My journey: From Rs. 30 bank balance to financial independence
- Thirty-fourth audit: Our journey: From scratch to a net worth of 18 times annual expenses.
- Thirty-fifth audit: From a net worth of Rs. 6000 to auto-pilot goal-based investing
- Thirty-sixth audit: How I retired from corporate bondage at 46, two years ago!
- Thirty-seventh audit: How I learnt to keep it simple and build a net worth 19 times my annual expenses
- Thirty-eighth audit: How Abhineeth plans to achieve financial independence and build a house.
These published audits have had a compounding effect on readers. If you would like to contribute to the DIY community in this manner, send your audits to freefincal AT Gmail. They could be published anonymously if you so desire.