Last Updated on December 29, 2021 at 5:59 pm
In the third edition of personal finance audits by readers, a single mom of two kids shares her inspiring journey. Her money story also brings out the importance of working with a SEBI registered fee-only advisor.
As regular readers may be aware, we publish a personal financial audit each December – this is the 2020 edition: How my retirement portfolio performed in 2020. This time, we asked regular readers to share how they review their investments and track financial goals. First audit: How Suhas tracks his MF investments and reviews financial goals. Second audit: How Avadhoot Joshi evaluates his investment portfolio. The third audit is by “EE” as she would like to be called after the Tamil name for a housefly 🙂
I am a single mother of two kids since 2013. I am working in a product MNC. Before 2014, I had invested in ULIPs, share market etc. but withdrew all post-2010. Spent all money towards home loan closure for a 2BHK flat (where we live) and some physical gold other than some medical expenses. We go on multiple family vacations each year, spend good enough to mingle with my circle of friends, do not compromise on lifestyle or passion in the name of frugality. I keep adjusting my goals, based on changing needs.
I track my goals and investments using my own excel sheet with all entries keyed in periodically; file my ITR using the Govt website; offload work to paid workers, wherever it works. I work on people impacting work in addition to my regular job. I donate a little to people in need.
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
Investments
Took expert advice from AIFW and covered my basics first and later started with 1Lakh investment in PPF (April 2014 – did not time it well). After all research, I did goal-based investing in HDFC Top 200, QLTE and Franklin Bluechip. After two years of such DIY investment, I realised that I was unable to understand which fund is performing well or not.
I wondered if markets can even give back the fees paid for a financial planner if I opt for one. After a long thought, I went ahead to hire one. Fortunately, a friend from Facebook group Asan Ideas for Wealth (Melvin Joseph), who I trusted well, agreed to be my Financial planner. I am delighted with this decision to date.
More about Melvin:
- Fee-only Advisor Journey: Melvin Joseph’s determined struggle to the top
- SEBI RIA Melvin Joseph releases free e-book: Health Insurance Simplified
- Kid’s Education and You (KEY) now serves 260 children thanks to you!
Investment strategy
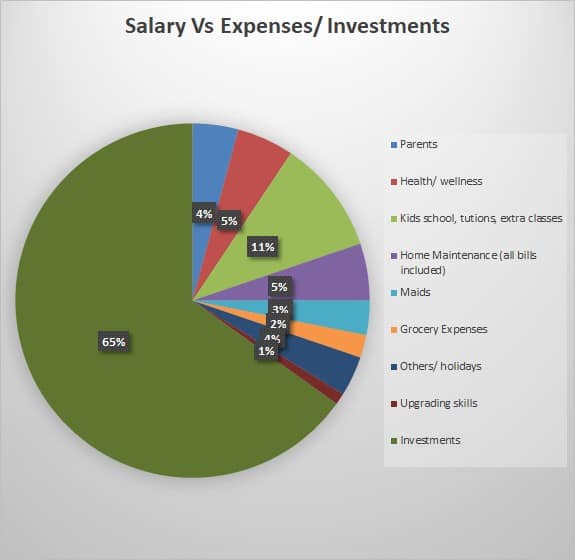
As soon as I get my salary, I allocate money for regular expenses and a little backup for unexpected expenses and invest the rest for my goals. From my previous three funds investments, I have moved to investment in 5 Equity funds by removing the older ones from the list. I also have PF, PPF and my company stocks dedicated to my retirement.
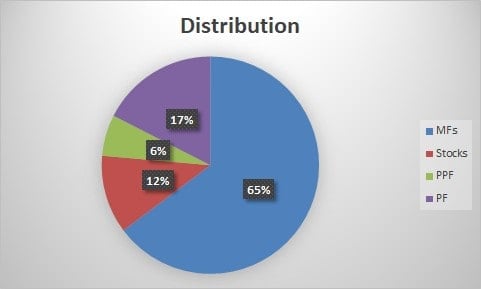
Traditional investments: I haven’t bought any gold in the past nine years and don’t have to buy any further. I inherit half of an independent house in a metro city and own a decent 2BHK flat in another city, where I live.
I am about to buy an independent house in my native metro city, which is unplanned. I wouldn’t be touching any of my future goals’ investments, and by selling a plot I invested a decade ago, I am buying this house. Also, I will continue the current investment amount towards my goals and wouldn’t reduce it due to home loan burden. I am not retiring earlier than planned to buy this house. This is merely due to family sentiments, and it wouldn’t hurt me much, due to the rental income I would get from this house.
Financial Freedom
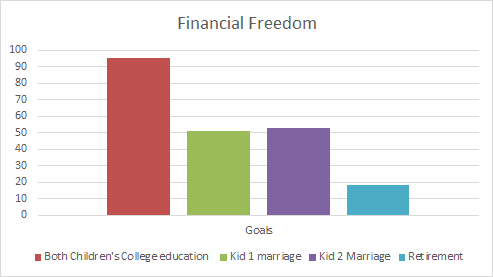
With less than 6 yrs of investments, I am almost close to my financial freedom. I could have retired in a couple of years, if not buying a house now. On any of my MF investments, most days the XIRR is 9-14%. My current salary is 2.3 times of what it was in 2014.
I started with the lowest five digits in 2014 in investments. With six months to go for my 40th birthday, I have saved 40 times my family needs (per annum need) / 57 times my annual need (without kids expense). Frugal living without compromising on upskilling/ passion/ lifestyle, regular investments, and focus on career growth helped me be on the right track.
The Future
My WILL is available for my family’s access, and also the passwords are available to access by my family if the need arises. I want to add super top-up cover for health insurance sooner, and I may or may not add critical illness cover (which I have been avoiding since there is a lot of amount spent on insurance premium alone).
I am yet to gain more confidence towards investing in markets directly (without AMCs) and hence will continue my current investment strategy as is with annual review with my financial advisor.
Will focus more on health and family while I continue my efforts towards my career growth.
Thank you note: My sincere thanks to Melvin sir, Ashalji, Pattu sir, Swapnil and a few more AIFW members who supported me all through this journey.
Resources
If you would like to work with a financial advisor to set your finances on track, you can choose one from the freefincal List of Fee-only Financial Planners in India (SEBI RIAs)
- How I achieved financial freedom and became an Investment Advisor! (part 1)
- Factors that helped me achieve financial freedom (part 2)
- Fee-only Advisor Abhishek Kumar’s tap dancing to financial freedom
- Why we need to forget about pension after retirement and focus on financial freedom Paisa Vaisa Podcast Part 1
- How to create your financial freedom plan – Paisa Vaisa Podcast Part 2
- Paisa Vaisa Podcast Part 3
- I achieved financial independence at 35: My journey and lessons
- Early Retirement at the 40s in India with financial independence: An Interview
Want a free guide to start your journey towards FIRE? Early Retirement in India -How to Retire Early Safely: Free E-book