Last Updated on December 29, 2021 at 6:28 pm
In this edition of the reader story, we meet Mr Sailor (real name withheld on request) who, despite several mistakes (judged in the comfort of hindsight, to be fair), is on course to achieve financial independence by age 45. His journey teaches us to not wallow in regret, move forward and be consistent.
About this series: I am grateful to readers for sharing intimate details about their financial lives for the benefit of readers. This is the 21st such reader audit. Previous editions are linked at the bottom of this article.
Opinions published in reader stories need not represent the views of freefincal or its editors. We must appreciate multiple solutions to the money management puzzle and be empathetic to diverse views.
If you would like to contribute to the DIY community in this manner, send your audits to freefincal AT Gmail. They can be published anonymously (such as this account) if you so desire.
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
Please note: We welcome such articles from young earners who have just started their investing journey (this edition is a good example. Also see, for example, audits by Suhas and Avadhoot linked below).
I am a typical IT guy who did engineering in some other branch before joining IT. My investment journey is full of mistakes – big and small and hopefully, someone else will learn from it. I joined IT in 2003 and made a couple of short trips to the US, and I thought I had saved enough money when I returned from the US in 2008.
I did whatever any normal guy would do – redeemed all my USD to Rupees at 36 Rs to a $ (before the 2008 crash, fearing that Rs will appreciate even further 😊) and then bought a home on loan using the money as a significant down payment in 2008 (after the crash, to be exact, I booked my apartment in the first week of Oct 2008 – yup, the same week when the Stock market was at the absolute bottom).
It wasn’t that I hadn’t heard about stocks – but I thought the downtrend would go on for years, and so real estate would be my saviour. Just FYI, the apartment has just about doubled in the last 13 years.
I started paying my EMI in 2009, blessed with a kid towards the end of that year, and my family became a single-income home after my wife decided that she had to take up the home mantle fully. 2010 came and went, and I was getting worried about finances & a few things on the personal front.
I realized that money is not going to grow with the way how things are currently set up. I was never a spendthrift but never knew what to do with money. I started reading a lot online – there was a guy called Subra who was sarcastic, caustic but posting interesting stuff on personal finance online.
There was also a guy called Manish who was posting insightful articles on personal finance on his blog every day. Those were golden days, and I was reading a ton of it. Manish’s blog also had an engaging forum that had many user questions, mostly answered by a very helpful guy named Aslanshu (I hope my memory serves right!) – he now goes by the name – Ashal Jauhari.
2011 came, and I realized that I can’t commute in Bangalore with a kid on pothole-ridden roads on a bike and so had to buy a car. But I had saved enough to buy a car without a loan and I had money sitting in liquid funds for the entire car price (which was my parked money till I understood more about Mutual funds).
By mid-2011, I was armed with knowledge from all the gurus, and I decided that Mutual funds were the only way to grow, and I had to invest heavily there. I started my first SIP in August 2011 in the beloved QLTEF at the age of 30. At the end of the year, I had reached about 0.5X in my investment journey and a home loan to payout.
I invested close to 30-40% of my take home, and the needle wasn’t moving. 2012 made me realize that there needs to be a bump in the kitty to plan FIRE or even a decent retirement. So started scouting for onsite opportunities, which came in 2013.
Before I boarded my flight in 2013, I decided on the return date to the month and year when I would return, and this brought clarity on how much time I got. It also took out the question of settling down in A foreign land. The next three years had a 2-pronged goal –Enjoying the time in a foreign land and saving for retirement. Also, the family grew from 3 to 4, which changed the goals a bit.
Through the journey, I had at the max 4 SIPs on which I invested and nothing more. The funds kept switching, but the motto was the same. Invest for a long time, and don’t worry about intermediate results. I don’t follow individual goal level asset allocation but a single portfolio level asset allocation.
When I started investment, I believed I was an aggressive investor and almost all my money needs to be in equity. But time brought a bit of maturity. I realized I was comfortable with an asset allocation of 50% debt and 50% equity.
I used a SEBI registered fee-only financial planner once I returned to India, who helped to sort out my insurance needs. And now, I believe my family is adequately covered. But I am still DIY mostly and I used FOI advice as a checkpoint in my journey.
Over the years, my SIP amount has grown by bounds – it is now about 10 times my original SIP amount. I still made a lot of mistakes along the journey – missed opportunities, not being more aggressive, a bit of churning of funds. But the investment never stopped. Now active funds have given way to index funds (though not completely). I do a rebalancing about once a year depending on when I think the allocation is skewed. I used March 2020 to bump up my equity (though I feel it could have been better).
Here is a quick glimpse of my corpus growth over the years:
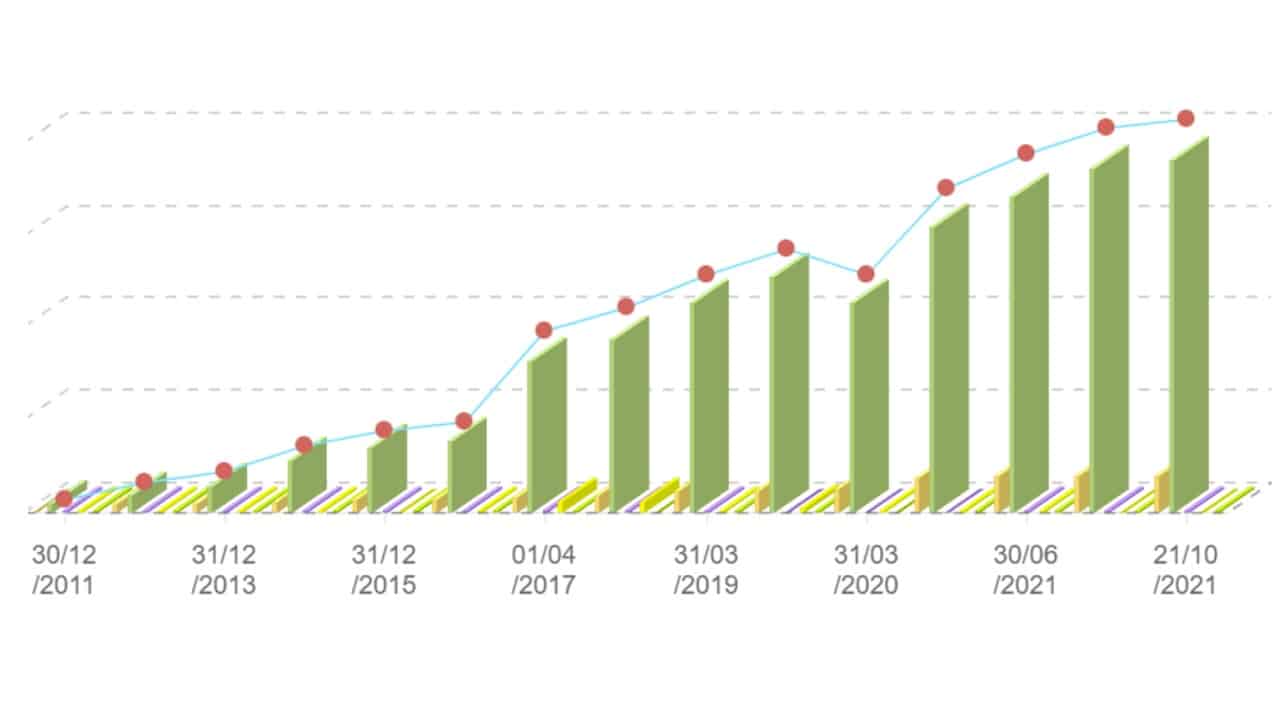
Just a couple of months ago, I completed my 10-year milestone at the age of 40. Over time, my investment corpus has grown to 36X (remember, it is a consolidated fund and not just retirement). I believe I can reach my goal of FIRE in another five years. I also have a fully paid out home (but cannot stay in it for personal reasons now).
I might get a small amount from an inheritance, but I also need to care for my parents, so I effectively discount that. The corpus growth has helped me slowly diverge into equity (it is still just 1.5X of my overall portfolio) and become more adventurous in my job (I am still conservative here, still in the same org from the beginning, salary is way below industry benchmark). I believe consistency is the key – you will make mistakes along the way but keep ploughing ahead. Things will pan out.
Reader stories published earlier
As regular readers may know, we publish a personal financial audit each December – this is the 2020 edition: How my retirement portfolio performed in 2020. We asked regular readers to share how they review their investments and track financial goals.
- First audit: How Suhas tracks his MF investments and reviews financial goals.
- Second audit: How Avadhoot Joshi evaluates his investment portfolio.
- Third audit: How a single mom is on track to financial freedom
- Fourth audit: How Gowtham started goal-based investing & took control of his money
- Fifth audit: Why my financial independence & early retirement plans were postponed by four years
- Sixth audit: How Abhisek funded his marriage & is on track to financial freedom.
- Seventh audit: How Rohit’s early struggles defined his investment journey
- Eighth audit: Why my investments are still on track despite job loss and lower-income
- Ninth audit: How a retirement planning calculation scared me to take action
- Tenth audit: I made several investment mistakes but have turned my life around.
- Eleventh audit: My net worth doubled in the last financial year thanks to patient investing!
- Twelveth audit: My financial journey: from novice to goal-based investor.
- Thirteenth audit: My journey: from a negative net worth to goal-based investing.
- Fourteenth audit: From Fixed Deposits to Goal-based investing in MFs.
- Fifteenth audit: My 10-year financial journey – mistakes made and lessons learnt.
- Sixteenth audit (part 1): How I achieved financial independence without mutual funds or stocks.
- Sixteenth audit (part 2): Lessons from my financial independence journey and future investment plans.
- Seventeenth audit: How I plan to achieve financial independence and move to my native place
- Eighteenth audit: I used the current bull run to reduce my mutual funds from 14 to 4!
- Nineteenth audit: How a conservative investor created his own financial plan
- Twentieth audit: I plan to achieve financial independence by 46; this is my master plan
These published audits have had a compounding effect on readers. If you would like to contribute to the DIY community in this manner, send your audits to freefincal AT Gmail. They could be published anonymously if you so desire.