As regular readers may know, we publish an annual personal finance audit every December – our 2022 audit was posted a few weeks ago. Since 2020 regular readers have been sharing their investment journey and portfolio reviews. Suhas was among the first to do this. He has graciously agreed to share the 3rd update on his finances with us. The first two editions are linked below.
About this series: I am grateful to readers for sharing intimate details about their financial lives for the benefit of readers. Some of the previous editions are linked at the bottom of this article. You can also access the full reader story archive.
Opinions published in reader stories need not represent the views of freefincal or its editors. We must appreciate multiple solutions to the money management puzzle and empathise with diverse views. Articles are typically not checked for grammar unless necessary to convey the right meaning to preserve the tone and emotions of the writers.
If you would like to contribute to the DIY community in this manner, send your audits to freefincal AT Gmail dot com. They can be published anonymously if you so desire.
Please note: We welcome such articles from young earners who have just started investing. See, for example, this piece by a 29-year-old: How I track financial goals without worrying about returns. Now over to Suhas.
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
Hello all, Happy new year to everyone, I hope you all are doing fine.
I cannot believe that this is my third post on freefincal. Thank you, Pattu sir, for the opportunity.
2020 and 2021 were eventful years; compared to those years, 2022 was a pretty quiet and smooth year, so this will be a very quick update.
Also, this year I completed ten years of mutual fund investing; 2012 was the year where I made my first equity/debt mutual fund purchase. There was a lot of learning over these years, and I wrote a post about it on my blog, do give it a read.
I try to write and update every quarter with more details on my blog DudduKaasu, do follow if you are interested.
As always, the big picture comes first, the networth and its progress.
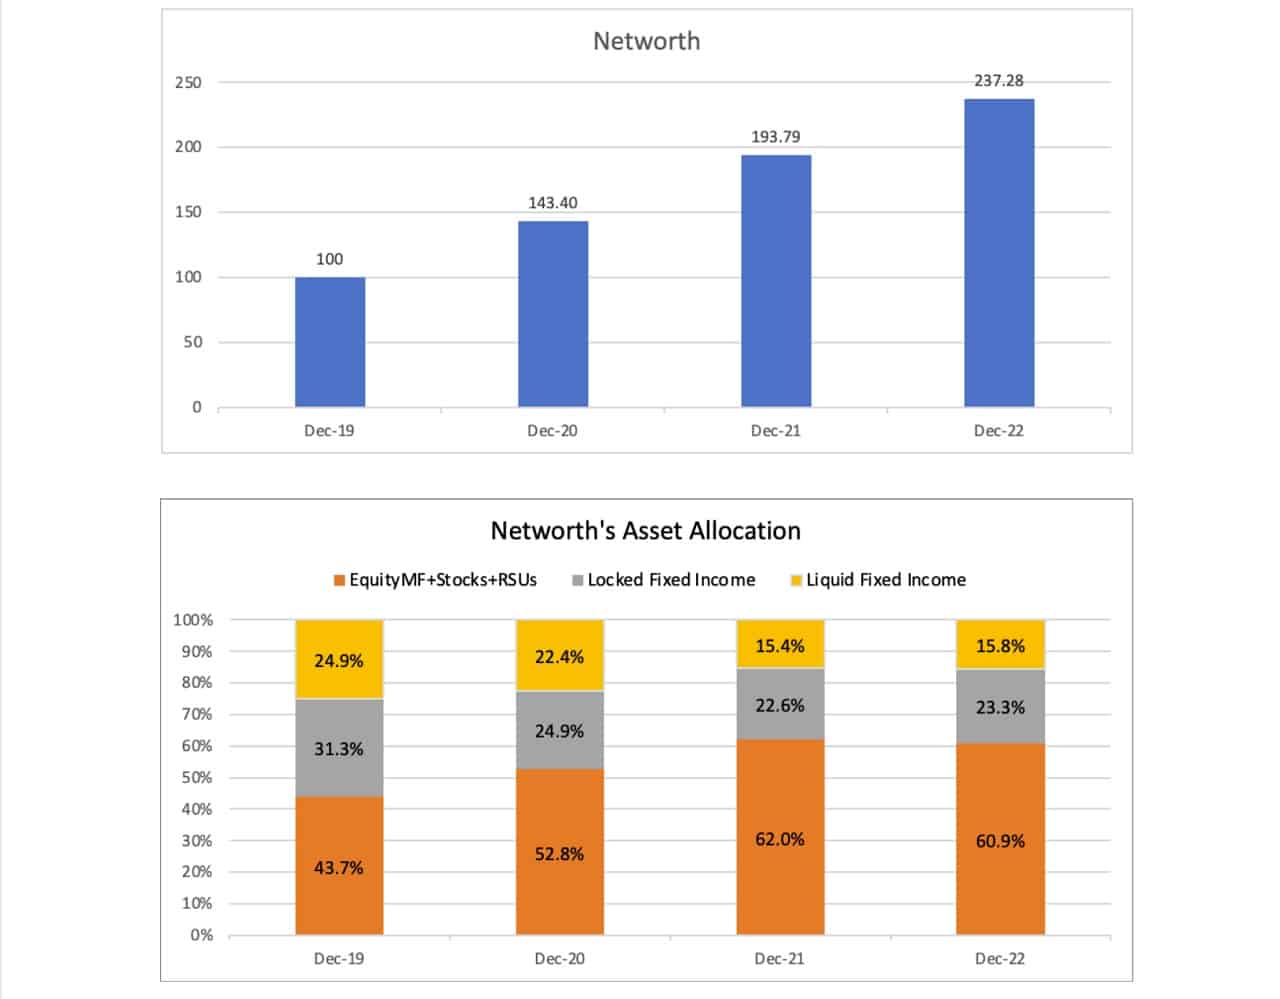
- Equity consists of equity mutual funds, direct equity and RSUs.
- Locked Fixed Income is debt with long-term lock-in. It consists of EPF and PPF.
- Liquid Fixed Income is debt without lock-in. It consists of liquid funds, arbitrage funds, bank accounts and debt mutual funds.
Emergency Corpus
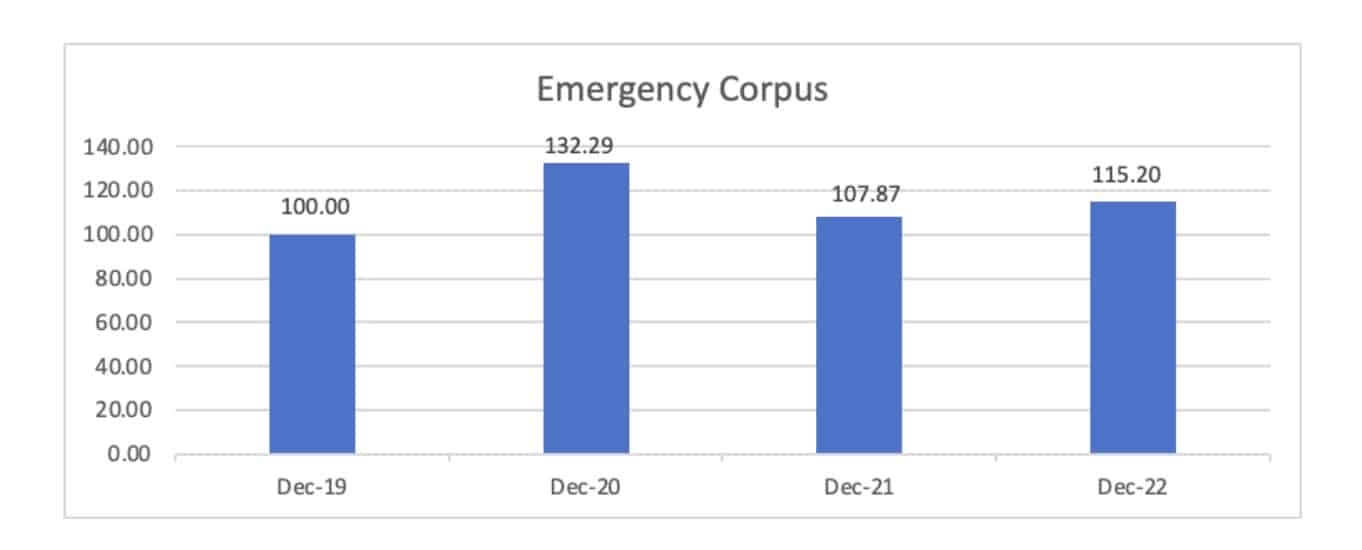
Made a small change here compared to last year, and moved around 25% of my emergency fund to a conservative hybrid fund.
I will obviously never recommend this to anyone, but since my emergency fund is fairly robust with around 1y of take-home salary, I felt keeping 55% in a liquid fund is a touch too much and hence decided to add a conservative hybrid fund, this will be the last fund that will be touched in case of an emergency.
Current allocations towards the emergency fund are 30% liquid fund, 40% equity arbitrage fund, 25% conservative hybrid, and the rest in bank
Kid’s Education Corpus
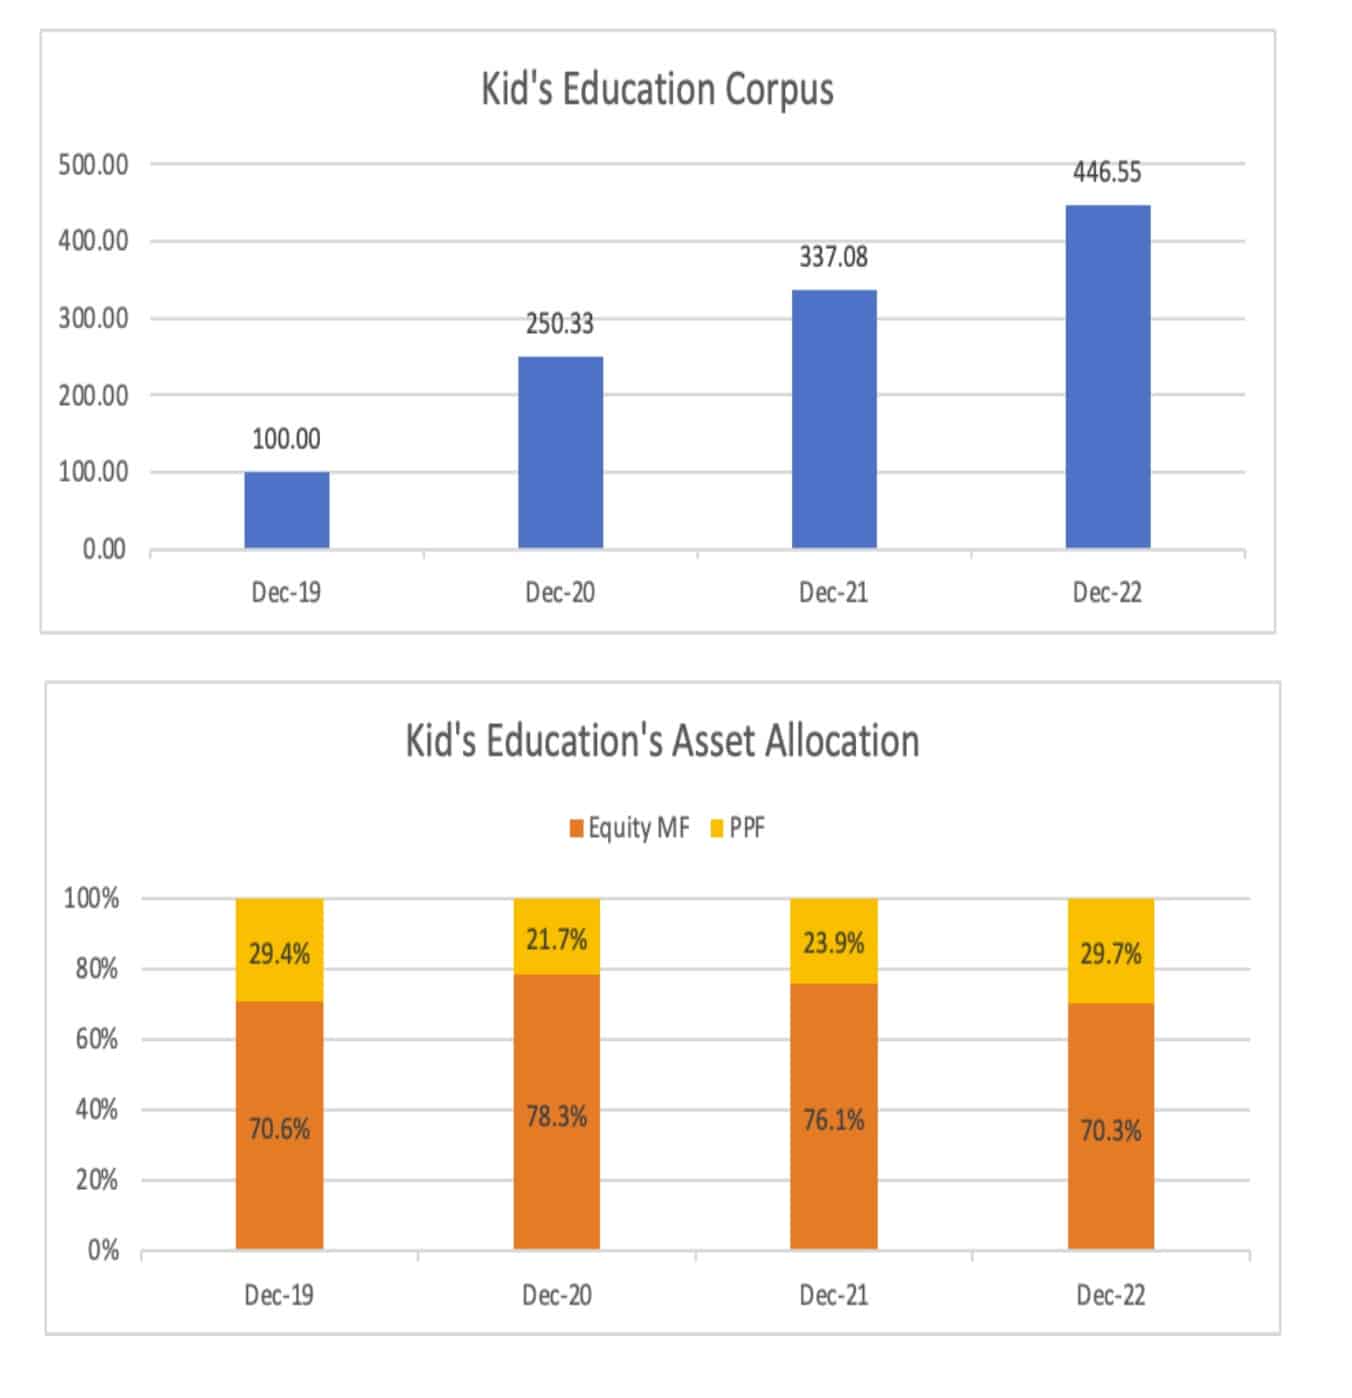
As said last year, I was contemplating on adding a debt fund towards this goal, but instead I added one more PPF account, which should mature when my child turns 19. On the equity side there is no change, it still has only a single fund and on the debt side, it now has 2 PPF accounts.
Why a PPF account and not a debt fund? This goal is another 13-15 years away means that PPF could be an ideal choice now. I know that PPF rates will eventually go down, but as I near the goal, more money needs to be pushed into the debt portfolio and 2 PPF accounts may not suffice, so somewhere down the line a debt fund will come into play, hence it was better to open a PPF account now and open a debt fund at a later stage.
What is the kid’s fund worth today? As said before, as of today, it should comfortably cover college fees.
Retirement Corpus
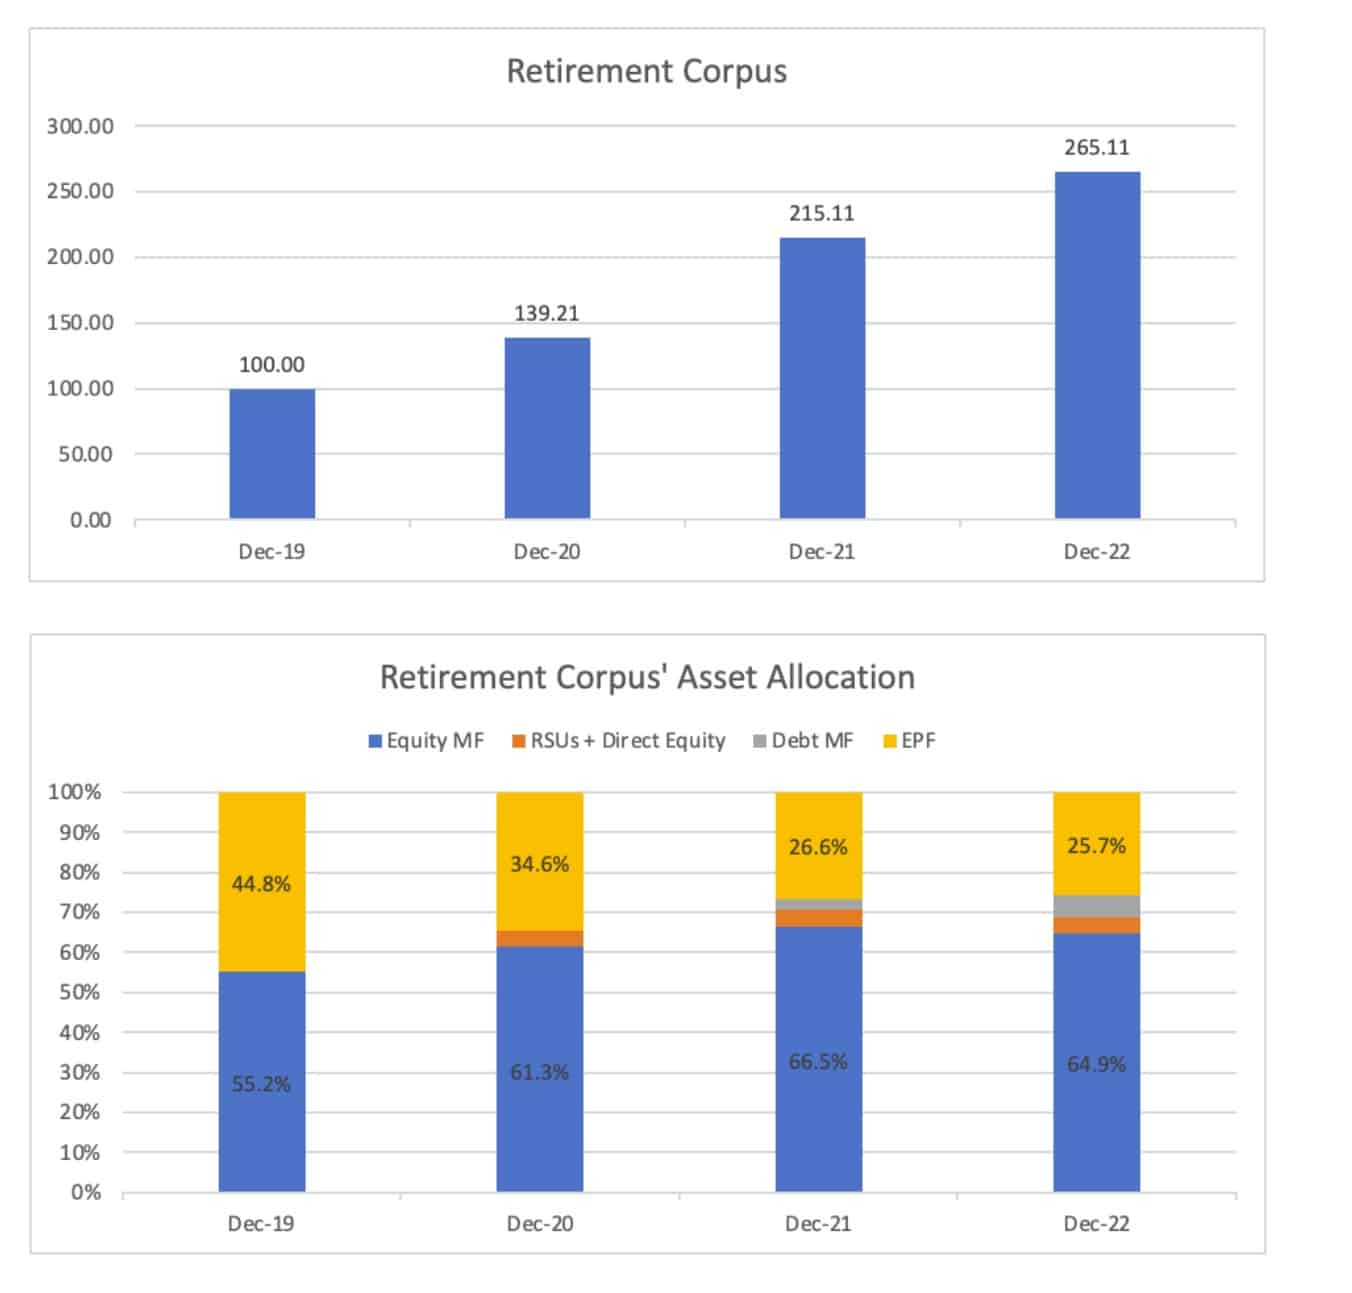
No change in the strategy here; we continued to add to the gilt fund purchased last year.
Equity MF constitutes 64.9%, RSUs + direct equity constitutes 3.9%, Gilt fund constitutes 5.6% and EPF constitutes 25.7%
What is the retirement corpus worth today? The current corpus is around 17 times my current annual expenses.
Note: In my last post, I had put the Dec 2021 value at 154.5 when it was 215.11. 154.5 was June 2021 value. Sorry for that wrong info on the graph in the previous post
As told before, I try to write and update every quarter with more details on my blog DudduKaasu, do follow if you are interested. Thank you.
Reader stories published earlier
As regular readers may know, we publish a personal financial audit each December – this is the 2020 edition: How my retirement portfolio performed in 2020. We asked regular readers to share how they review their investments and track financial goals.
- First audit: How Suhas tracks his MF investments and reviews financial goals.
- Update 1: Why I hiked my retirement corpus target though my networth doubled since Dec 2019.
- Update 2: After ten years of MF investing, Suhas is on track to achieve his financial goals
- Second audit: How Avadhoot Joshi evaluates his investment portfolio.
- Third audit: How a single mom is on track to financial freedom
- Fourth audit: How Gowtham started goal-based investing & took control of his money
- Fifth audit: Why my financial independence & early retirement plans were postponed by four years
- Sixth audit: How Abhisek funded his marriage & is on track to financial freedom.
- Seventh audit: How Rohit’s early struggles defined his investment journey
- Eighth audit: Why my investments are still on track despite job loss and lower-income
- Ninth audit: How a retirement planning calculation scared me to take action
- Tenth audit: I made several investment mistakes but have turned my life around.
- Eleventh audit: My net worth doubled in the last financial year, thanks to patient investing!
- Update: How I achieved investing nirvana.
- Twelveth audit: My financial journey: from novice to goal-based investor.
- Thirteenth audit: My journey: from a negative net worth to goal-based investing.
- Fourteenth audit: From Fixed Deposits to Goal-based investing in MFs.
- Fifteenth audit: My 10-year financial journey – mistakes made and lessons learnt.
- Sixteenth audit (part 1): How I achieved financial independence without mutual funds or stocks.
- Sixteenth audit (part 2): Lessons from my financial independence journey and future investment plans.
- Seventeenth audit: How I plan to achieve financial independence and move to my native place
- Eighteenth audit: I used the current bull run to reduce my mutual funds from 14 to 4!
- Nineteenth audit: How a conservative investor created his financial plan
- Twentieth audit: I plan to achieve financial independence by 46; this is my master plan
- Twenty-first audit: I have made many investment mistakes but am on course to financial independence by 45.
- Twenty-second audit: I felt worthless six years ago but have achieved financial stability today
- Twenty-third audit: My financial journey was directionless until age 40: this is how I made up for lost time
- Twenty-fourth audit: Why I increased equity MF investments by 275% and reduced PPF contributions.
- Twenty-fifth audit: How I track financial goals without worrying about returns
- Twenty-sixth audit: I am 24 and started investing 1Y ago, but what am I investing for?
- Twenty-seventh audit: How we plan to achieve a retirement corpus 50 times our annual expenses.
- Twenty-eighth audit: I thought equity investing was a gamble, but now I aim to hold 60% equity for retirement
- Twenty-ninth audit: My journey: From 5 lakhs in debt to building a corpus worth six years in retirement
- Thirtieth audit: My investment journey: From random purchases to a goal-based portfolio
- Thirty-first audit: My investment journey: from product-driven to process-driven
- Thirty-second audit: How a young couple is trying to balance travelling and investing
- Thirty-third audit: My journey: From Rs. 30 bank balance to financial independence
- Thirty-fourth audit: Our journey: From scratch to a net worth of 18 times annual expenses.
- Thirty-fifth audit: From a net worth of Rs. 6000 to auto-pilot goal-based investing
- Thirty-sixth audit: How I retired from corporate bondage at 46, two years ago!
These published audits have had a compounding effect on readers. If you would like to contribute to the DIY community in this manner, send your audits to freefincal AT Gmail. They could be published anonymously if you so desire.