Last Updated on December 29, 2021 at 6:12 pm
In this article, we provide a step-by-step guide to choose a gilt mutual fund. Gilt mutual funds are those that invest a minimum of 80% of their portfolio in government securities (Gsecs or gilts).
We have already discussed the basics of gilt mutual funds and when to invest in a two-part FAQ. We recommend newbie investors first cover these two articles and then head back to this one. Part 1: FAQ on gilt mutual funds: essentials investors should know. Part 2: If equity MF returns are negative, will gilt MF returns be positive? These two articles explain the kind of risks an investor has to face while investing in gilt funds. There are two types of gilt mutual funds.
1. Gilt Funds: These can invest in Gsec of all maturities (bond tenures can vary from a few days to 40 years!!). These should be used for goals 10 years or more away. The fund manager can tactically/dynamically change the duration of the bonds as per “market conditions”. Simultaneously, the benefit of this is (in principle) lower losses when the rates go up and higher gains when the rates fall. The fund manager could get this wrong.
2. Gilt Fund with 10-year constant maturity: They invest in Gsecs with a maturity period equal to or close to 10 years. These should be used for goals well above 10 years away. This resembles an open-ended index fund (with TER like an active fund). The risk of active fund calls is nearly absent here, but these funds could fall the most when the rates increase.
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
Gilt mutual funds should only be used by those who can withstand volatility in the NAV, can review investments at the portfolio level, regularly rebalance to exploit the NAV volatility (of both gilts and equity). If you do not know how to do this, stay away from gilt funds.
If you want to choose gilt mutual funds, you must be ready to study past fund factsheets. You must also occasionally keep an eye on the factsheets after you start investing. If you are not ready to do this, this guide is not for you; gilt funds or any debt fund is not for you.
Gilt fund selection checklist
- Never look at trailing returns (last 1,3,5,10 years etc.). If these are high, then the future returns could be less (or negative, and do not assume the vice versa will happen!)
- Never look at star ratings. They mean little.
- Do not look at the Yield to Maturity of the fund as a return measure. It is a risk measure. Higher the value, the longer the duration of the bonds in the gilt fund in normal circumstances (unless the yield curve is inverted). This means more volatility.
- For most investors with a proper asset allocation and strategy, monthly investment into a gilt fund is the simplest and most convenient strategy. See: Can we invest via SIP in gilt mutual funds for the long term? And, PPF vs Gilt mutual funds: Which has done better over 15 years?
- In principle, tactical entry and exit is possible but not for everyone and will not work the way we think and not all the time. See: Can we get better returns by timing entry & exit from gilt mutual funds?
- If you wish to choose the 10Y constant duration funds, then there only four choices: SBI, ICICI, IDFC and DSP. The SBI fund has 819 Crores (much of it from a previous avatar before SEBI recategorization). If I am not wrong, the same is true of the ICICI fund (326 Crores). It is pretty much an inky-pinky-ponky decision. Don’t worry too much about low TERs that bait to increase AUM.
- If you wish to choose normal gilts funds, then you need to some work. There are 21 funds, so you will have to create a shortlist with AMCs you are comfortable with.
- We shall look at funds from ICICI, SBI and HDFC (the big three in this category in term of AUM, March 2021)
- We shall only use a simple metric. The average portfolio maturity. If the portfolio has three bonds with maturities, 1Y, 5Y and 15Y, and weights, 10%, 30%, 60%, the average portfolio maturity is (10%x 1) + (30% x 5) + (60% x 15)
ICICI Gilt Fund vs SBI Gilt Fund vs HDFC Gilt Fund
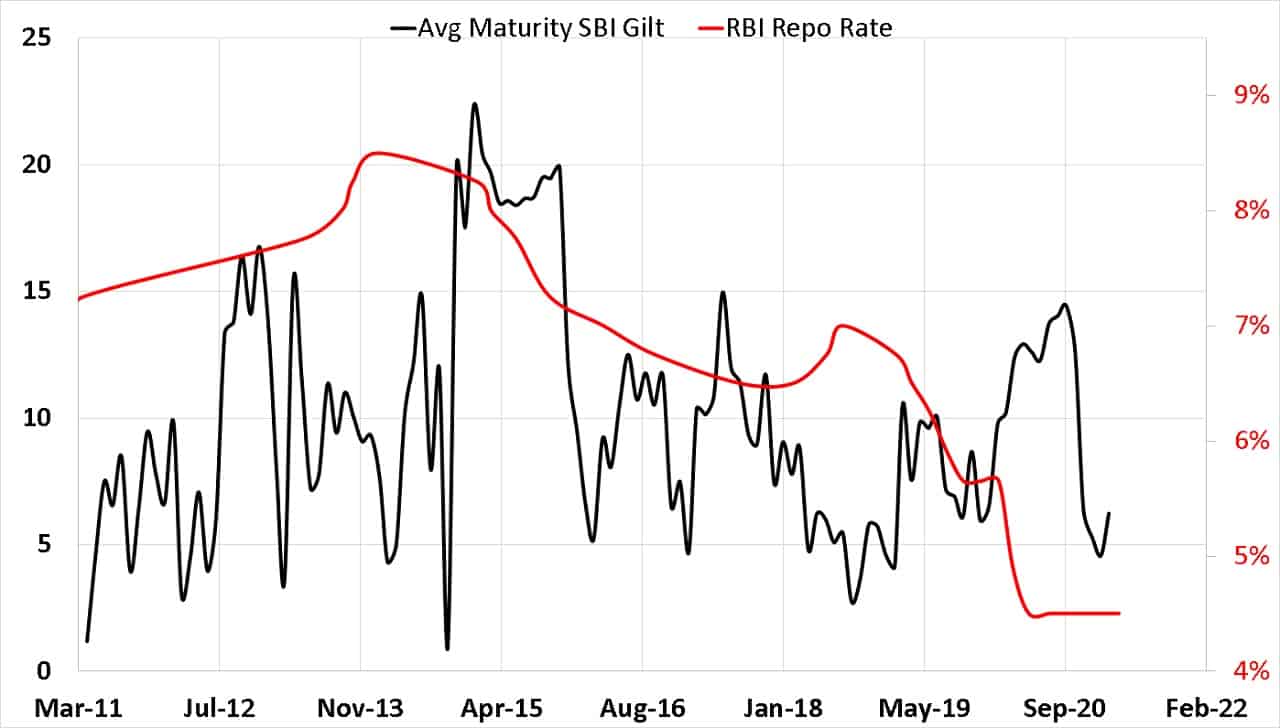
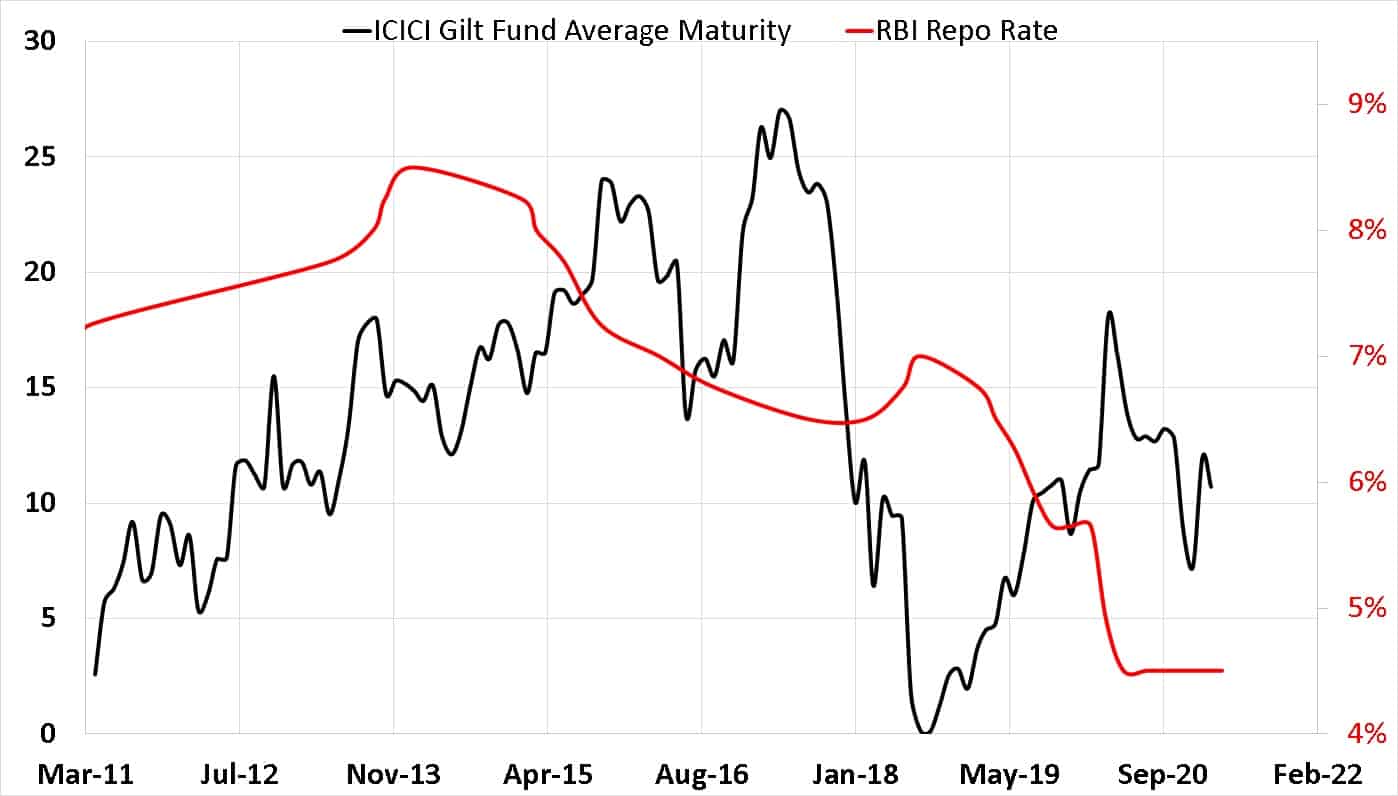
We compare the average portfolio maturity of these three gilts funds with the RBI Repo rate. It must be understood that the repo rate only indirectly influences long-term bonds. When the repo rate increases, the demand for existing long-term bonds will decrease in anticipation of fresh long term bonds with higher rates.
A one-to-one correspondence between a fund’s average portfolio maturity and the repo rate or any other macro-economic indicator is impossible. We can only make some simple inferences. Also, fund factsheet data is 2-4 weeks old. So there would be a lag between the repo rate and the published average maturity. The lag could be in either direction (in the past or future). We only compare the two quantities to get a flavour of what the fund is trying to do (and how often). Please do not use these graphs to praise or criticise the fund manager.
General thumbrule: When interest rates keep increasing, the fund manager will buy longer duration bonds (average portfolio maturity increases). These will provide more interest and also more capital gain if the rates fall. When interest rates start falling, the average portfolio maturity decreases. This will reduce losses if the rates increase.
Please do not get overwhelmed by the following graphs. I am not suggesting that you draw such graphs before investing (I did not before I put my money in ICICI gilt fund). Use these to get an idea of how much active management is involved in these funds. Do study a few factsheets to see how much the average maturity can vary.
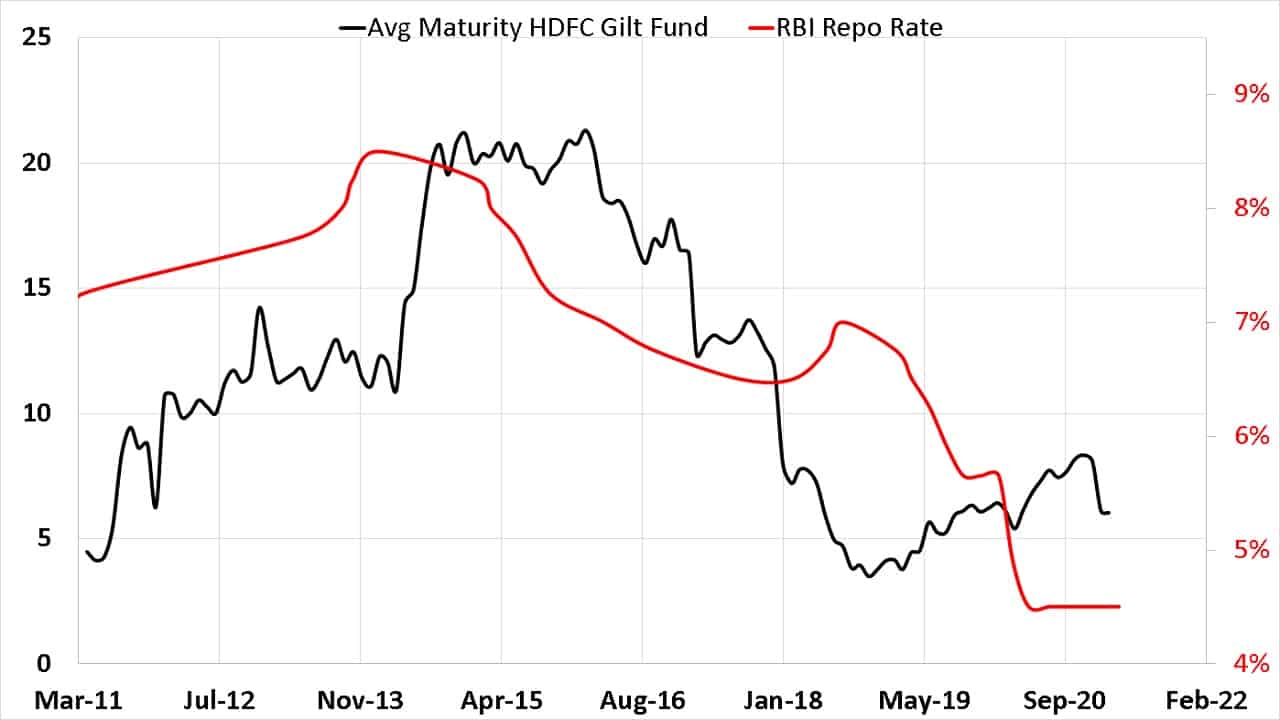
HDFC Gilt fund brochure says it invests “based on interest rate outlook; Global & Local macroeconomic variables such as growth, inflation, currency & Liquidity are evaluated to arrive at an interest rate outlook & position the portfolio accordingly” You can see from the above graph that this claim roughly falls in place.
Now SBI Gilt fund says it will actively manage interest risk. And it is pretty active!
As discussed earlier – Why I partially switched from ICICI Multi-Asset Fund to ICICI Gilt Fund – ICIC Gilt fund uses a debt valuation index (results published each month in their factsheet) to change average maturity dynamically.
According to the April 2017 factsheet
Debt Valuation Index considers WPI and CPI over G-Sec Yield, Current Account Balance and Crude Oil Movement for calculation. Equal weights are assigned to each of these parameters for calculating the index
According to March 2018 factsheet
Debt Valuation Index considers WPI, CPI, Sensex year on year returns, Gold year on year returns and Real estate year on year returns over G-Sec
yield, Current Account Balance and Crude Oil Movement for calculation.
Did these add Sensex, Gold and RE parameters later on or were they always present? This is the fund manager risk I mentioned above!
The HDFC fund does not churn much; SBI churns the most. The actual method is unknown in all case is unknown. However, all of them are trying to keep in step with interest perception: hold short duration bonds when rates are low and switch to longer duration bonds as the rates go up.
This isn’t very clear. What should I do? If you have patient enough to come this far, some of you might be feeling this way. So let us summarise.
How to select a gilt fund?
- Understand risks
- Be clear about your duration (preferably above 10 years)
- Be mentally prepared to rebalance (equity to debt if not only gilt) and from gilt to equity or other debt.
- Create a shortlist of comfortable AMCs
- Study average maturity from past factsheets. The idea here is not to do any deep analysis. Just get a few data points to appreciate how much the average maturity and, therefore, volatility can vary.
- Choose a fund that you are comfortable with. Regardless of the method used to vary bond durations, returns may not differ much!
- Do not expect the fund manager to make perfect calls. Double-digit gains are possible in gilt funds. This means they will suffer losses. How well we exploit this is up to us.