Last Updated on October 8, 2023 at 1:40 pm
There were reports yesterday regarding SEBI thinking about asking fund houses to use benchmark indices where the dividends are assumed to be reinvested. Such total return benchmark indices (TRI) offer anywhere between 1-2% higher return each year over the normally used price indices (for large cap stocks) which do not consider dividends. While this is a welcome move, I discuss why bigger issues remain and they need to be tackled first for TRIs to make an impact.
If you wish to know how a total returns index is calculated or how much it can be influential, check out:
The magic of reinvested stock dividends!
Sensex Total Returns Index as a Mutual Fund Benchmark
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
Just because SEBI wants funds to use Nifty TRI instead of Nifty will not mean the fund managers will start sweating. Yes, the total returns indices are a bit tougher to beat after expenses. However, this is the situation as on Dec. 201th 2016:
Active Large Cap funds vs Nifty 50 TRI
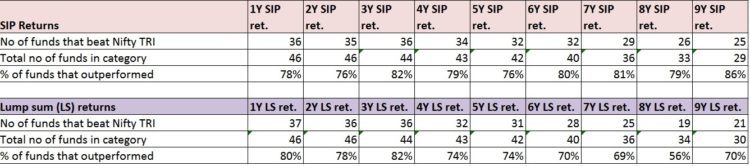
I would say that is pretty good. Sure the outperformance will be a touch lower if just the Nifty was used, but the more important question is, what is the source of the outperformance? Many large cap funds hold a good amount (25% or less) of mid-cap and even small cap stocks. Also, very few fund houses label funds as large-cap mid-cap etc. It is only the rating portals that do the classification.
So the first step would be to force fund houses or AMFI to clearly define market-cap based compartments and then let them classify funds with a guarantee not to stray from the bin without intimation to customers. This will make fund selection much easier.
I have no problem with a fund holding 20% of mid-caps, but they should be labelled appropriately and a suitable benchmark should be used. If most of the outperformance is from the mid-caps does it matter if I used Nifty or the Nifty TRI?
For example, Quantum Long Term Equity (QLTE) takes pride in using Sensex TRI as the benchmark. However, it can pick stocks from the BSE 200 universe. So the right benchmark should be BSE 200 TRI. QLTE has little trouble beating BSE 200 TRI but is a matter of better clarity to the investor. The benchmark should tell me where the fund can invest in. This is not the case today and so price or TRI is a secondary concern.
As an investor, I must be able to distinguish funds based on investing style: a pure large-cap fund, a multi-cap fund with large-cap tilt, a multi-cap fund with mid-cap tilt, pure mid-cap etc. This is important because market-cap is a proxy for volatility. Lower the market cap, higher the volatility.
As a second step, the broad sector-wise strategy should be indicated. It is hard to find funds which hold very little financial stocks.
With these two filters (cap-tilt and then sector-tilt if any) in place and suitable benchmarks identified, we can then discuss using price or TRI. Before that, I believe it will not make an impact.
Finding a fund with a well-defined investment strategy is hard, even if I bother to read the scheme document. And even if I find one, there is no guarantee that it will not stray. These are bigger and more important problems.
Another issue is with regard to the accessibility of benchmarks. NSE only offers Nifty TRI. I need to go to the S&P website to get BSE TRI indices and that too only for the last 10Y. Almost all hybrid funds and debt funds use CRISIL indices. Each CRISIL index costs 10-12 Lakh per index, per year!! I had to create my own hybrid index : A new and accessible benchmark for balanced mutual funds
A benchmark should not only be appropriate, it should also be accessible. This is not the case for many indices too (esp TRI). So SEBI should insist that funds use accessible benchmark. AMFI can easily maintain these indices. They have the funds to do this.
It is silly to talk about how passive investing is superior unless I can gauge which index to pick as an investor. As an investor, I can ‘actively’ choose a passive index only if I have the data (eg. TRIs of strategic indices) available. How I wish we had index funds (not ETFs) based on smart-beta or strategic indices (quant-based and not cap-based). Here is an example.
Active Large Cap funds vs Nifty Low Volatility
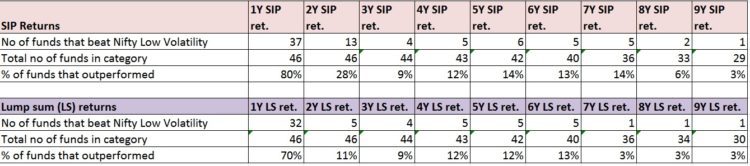
Nifty Low Volatility: A portfolio of 50 stocks that has the least volatility among all the stocks listed on the NSE. This is referred to as a smart beta strategy. Read more: Nifty Low Volatility 50: A Benchmark Index to watch out for. Only the price index is considered here
More results are here: Active vs Passive Investing: Large Cap Equity Mutual Funds.
and Active vs Passive Investing: Mid Cap Equity Mutual Funds
Fund houses know which indices are easy to beat (be it price or TRI)! So a TRI mandate will not make it tougher for them! As always, we need to be better informed and not blindly buy into their outperformance reports.
SEBI has to take steps to ensure investing style purity, proper categorization of schemes and reduce the number of existing schemes.
Your Thoughts?
References:
http://www.moneycontrol.com/news/business/sebi-working-on-guidelines-to-review-mutual-fund-benchmarks-2243299.html
http://smartinvestor.business-standard.com/market/story-447792-storydet-Sebi_wants_MFs_to_adopt_tougher_benchmarks.htm
New Delhi DIY Investor Workshop April 23rd 2017
Register for the New Delhi DIY Investor Workshop April 23rd 2017
You Can Be Rich Too With Goal-Based Investing
Happy to announce that my book with PV Subramanyam has been selected as part of Amazon Best Reads Mar 2017. Thank you for your support and trust. If you have not yet got the book, check out the reviews below and use the links to buy.
Reader Quotes:
this isn’t a book that is written in complex financial terms but in common man terms and easily understandable flow
It gives an excellent unbiased overview of investing.
I would classify this as a must have for everyone irrespective if you are a first time investor or seasoned investor
The best book ever on Financial Freedom Planning. Go get it now!
Your first investment should be buying this book
The (nine online) calculators are really awesome and will give you all possible insights
Thank you, readers, for your generous support and patronage.
Amazon Hardcover Rs. 274. 31% off
Kindle at Amazon.in (Rs. 307)
Google Play Store (for mobile/desktop) (Rs. 307)
Infibeam Now just Rs. 307 24% OFF.
If you use a mobikwik wallet, and purchase via infibeam, you can get up to 100% cashback!!
Bookadda Rs. 344. Flipkart Rs. 359
Amazon.com ($ 3.70 or Rs. 267)
Google Play Store (Rs. 244.30)
- Ask the right questions about money
- get simple solutions
- Define your goals clearly with worksheets
- Calculate the correct asset allocation for each goal.
- Find out how much insurance cover you need, and how much you need to invest with nine online calculator modules
- Learn to choose mutual funds qualitatively and quantitatively.
More information is available here: A Beginner’s Guide To Make Your Money Dreams Come True!
What Readers Say