Last Updated on December 14, 2025 at 3:09 pm
I evaluate my retirement portfolio’s performance and my son’s future portfolio each year in a personal finance audit. This is the tenth edition. Published from 2013 onwards, these audits provide a sense of accountability and ensure I do not fall prey to fear of missing out, preventing bad investment decisions. They also point out the fruits of systematic goal based investing.
I am proud and delighted that several readers have also published their audits at freefincal inspiring the next generation of DIY investors. We now have more than 40 such articles from readers. The full list is available at the end of this article: From a net worth of Rs. 6000 to auto-pilot goal-based investing.
Archive: This is the archive of personal finance audits published before: 2013 audit, 2014 audit, 2015 audit, 2016 audit, 2017 audit, 2018 audit, 2019 audit, 2020 audit and 2021 audit.
Disclaimer: This is a personalised financial audit. No part of this audit should be considered investment advice. My current portfolio is the residue of past mistakes, and my asset allocation reflects my changing goal-based risk appetite.
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
Overview: If the crash and recovery dominated 2020, 2021 was all about consolidation. As readers may recall, I rebalanced my long-term portfolios (retirement and my son’s future) twice. See, I rebalanced my retirement portfolio twice this year, thanks to the bull market. It turned out to be a good decision, as the market started moving aimlessly since Oct 2021.
So 2022 was a pretty quiet year, focusing solely on systematic investing and systematic increases in investments. See: Why increasing investments each year is crucial for financial freedom.
This year’s biggest change was the shift from Excel to the freefincal Google Sheets stock and mutual fund portfolio tracker. Earlier I used to spend time analysing portfolio growth. Now, it is fully automated, and one can compare it at any time with identical investments in any benchmark or even passive fund (see graphs below).
The asset allocation for both long term goals has been within limits this year, and a rebalance was unnecessary.
Retirement
- Asset Allocation: Equity: 60.74%; Fixed income: 39.26%
- Equity comprises 83% of mutual Funds, and the rest is direct equity.
- Analysis of the stock portfolio is available each month. This is the latest edition: Stock Portfolio Analysis: December 2022
- Fixed income with weights (wrt to total fixed income)
- NPS 61.03%
- PPF Wife 9.55%
- PPF Pattu 5.40%
- Cash 4.82% (ICICI Arbitrage + Quantum Liquid)
- ICICI Gilt 18.85% Xirr: 4.27%
- Parag Parikh CHF 0.35% Xirr: 9.34% (This is a recent addition. So don’t get excited)
- Note: The NPS has 15% equity + long-term gilts (majority). The reader, particularly those with the default govt NPS allocation, is cautioned that long-term gilts are extremely volatile. My NPS corpus returns dropped almost half after the July 2013 bond crash. See, After 12 years of investing in the NPS, my return is 8.9%
- The current NPS XIRR (market-linked since March 2010, 8% fixed before that) is 8.9%.
- Equity mutual funds
- Overall XIRR since June 2008: 14.64% (last year, it was 19.57%). This should not be taken too seriously: On March 23rd 2020, after the biggest intraday fall, my retirement equity MF portfolio return was 2.75%. If, after 12 years, the returns could crash to that level, we must learn to evaluate our portfolio by different metrics. This is why goal-based investing is crucial. You cannot buy groceries or college education with impressive XIRR data!
- Parag Parikh FlexiCap Weight: 54% Xirr: 17.79%
- HDFC Hybrid Balanced Weight: 25% Xirr: 14.75%
- Quantum Long Term Equity Weight 16% Xirr: 11.58%
- UTI Low Volatility Weight 5% Xirr 20.70% (This is a recent investment, so don’t get too excited!)
- Financial independence status: If I retire now, I would be able to live off my corpus for the rest of my insipid life and draw an income that increases with inflation at a rate equal to the rate of the portfolio return (zero real return).
- My current initial withdrawal rate is below 2%. For an explanation, see: I plan to retire in 25 years; what should be my safe withdrawal rate?
- Those interested in planning for early retirement can consult this free e-book: Early Retirement in India -How to Retire Early Safely.
This is the normalized evolution of my MF retirement portfolio since its inception (Jun 2008), along with an equivalent investment in Nifty 50 TRI. This was plotted with the freefincal portfolio tracker.
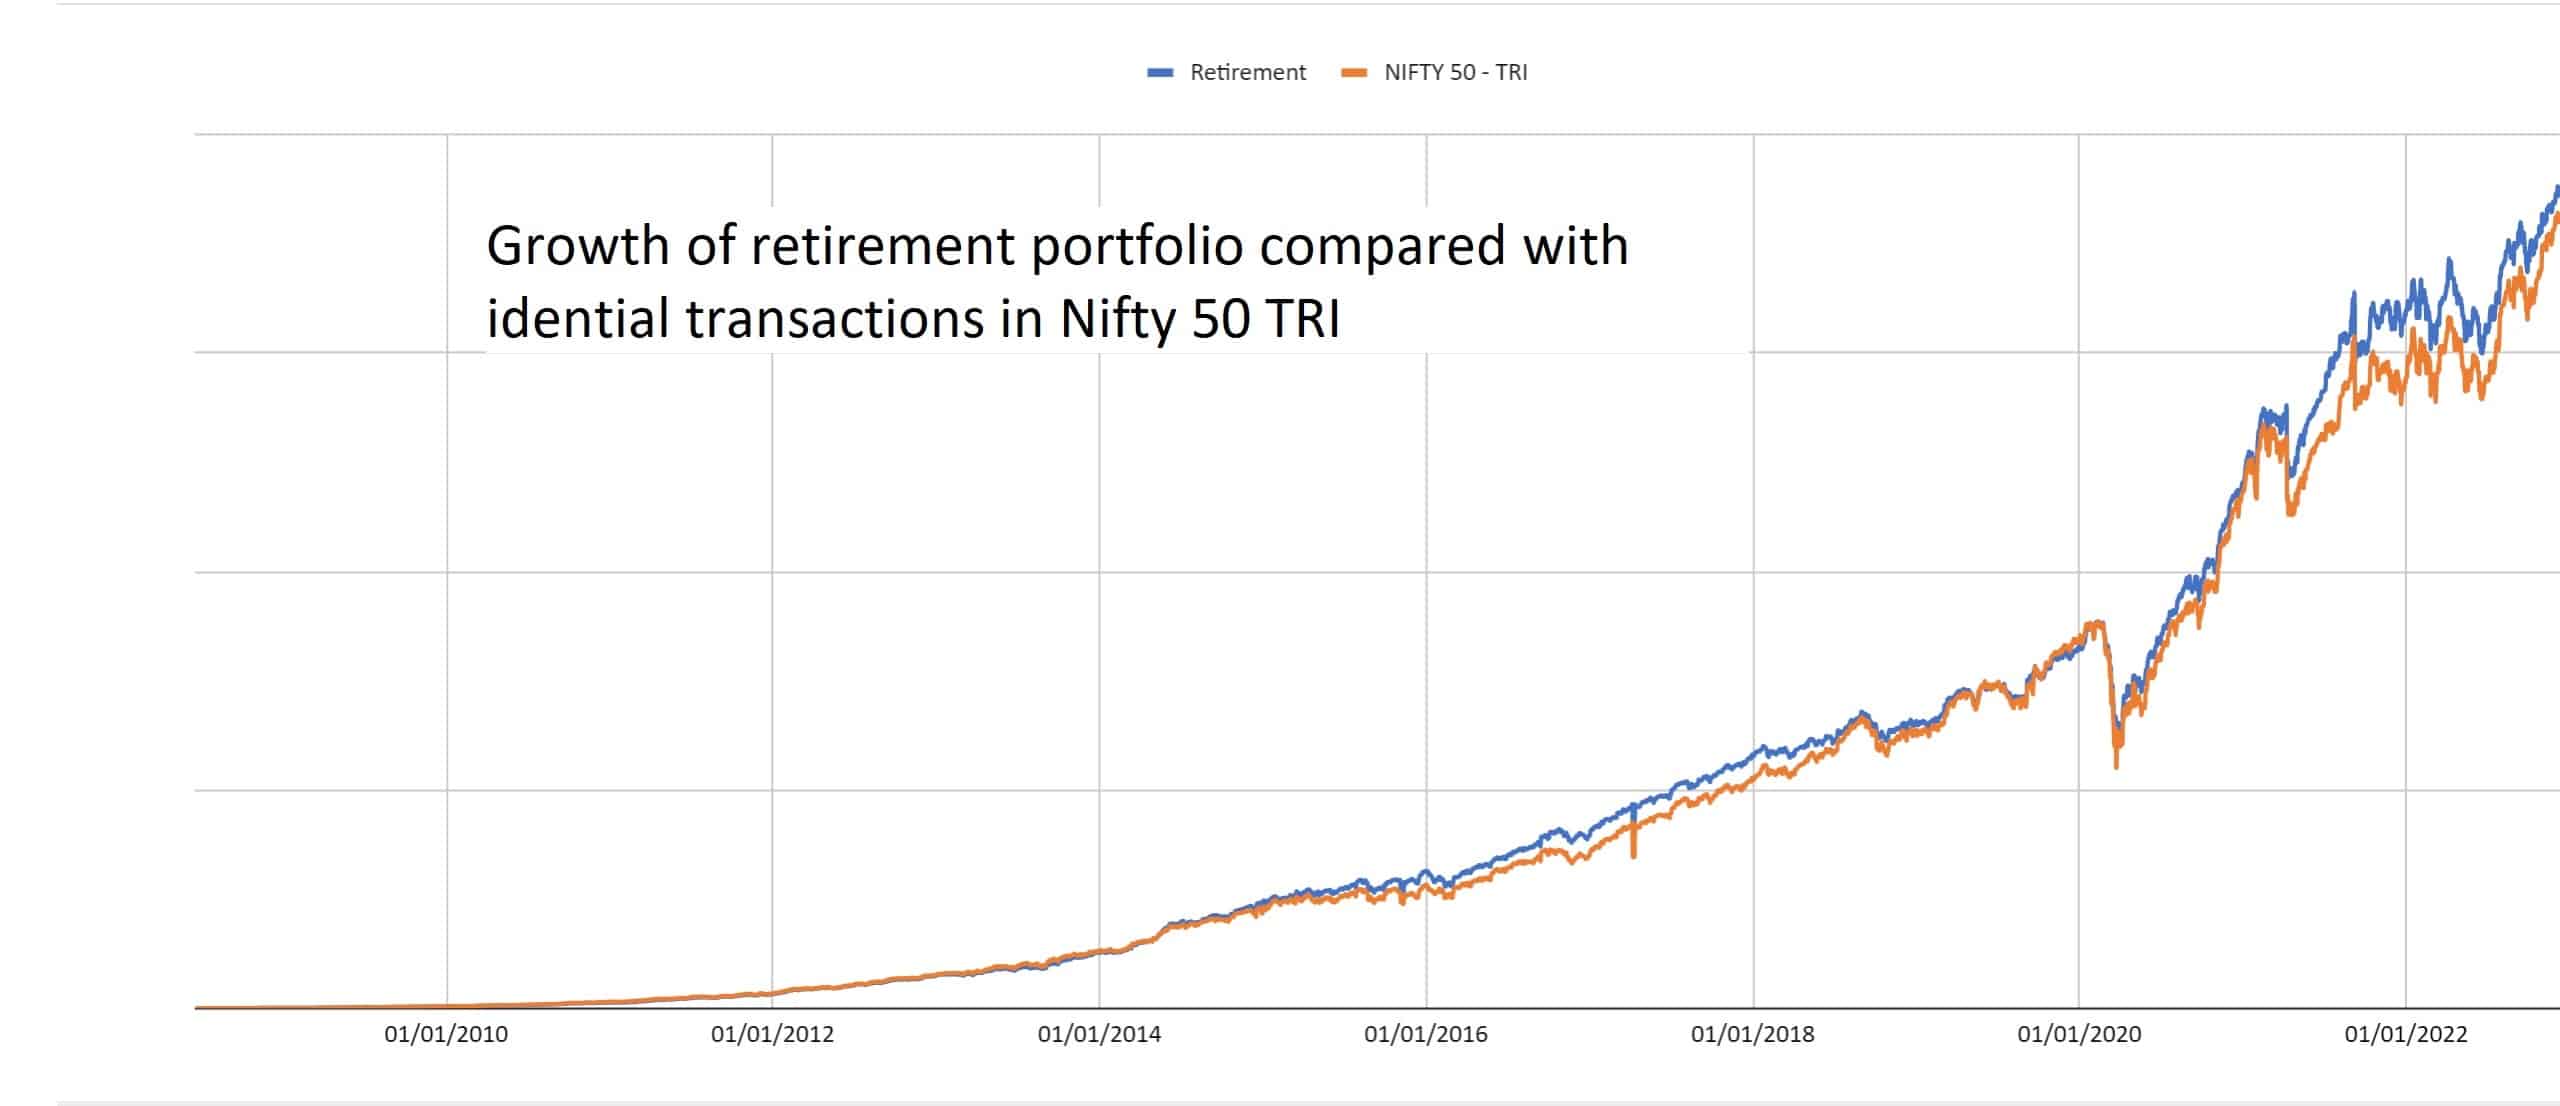
Please do not read too much into my portfolio outperforming Nifty 50 TRI. Sometimes it has, and sometimes it has not. It depends on when you look.
Child’s Education
I have been investing for my son’s future since December 2009 (a month before his birth). Then it was an 18-year-old goal, and now it has become a 5-year-old goal. In 2020 I reduced the equity allocation from 67% to 55%. It is currently 56.7% (after rebalancing twice this year!).
I have not bothered reducing the equity allocation because there are enough fixed-income funds to fund his UG and even PG degree at current costs.
Asset allocation
- Equity: Asset allocation 56.7%. Overall portfolio return: 15.37%
- HDFCBalAdv Weight 29% Xirr 17.25%
- ICICI Multi-asset Weight 45% Xirr 16.76%
- Mirae Largecap Weight 27% Xirr 14.91%
- Fixed income Asset allocation 43.27%
- ICICI Arbitrage Weight 28.3% Xirr 5.04%
- ICICI Gilt Weight 21.5% Xirr 4.16%
- Parag Parikh CHF Weight 4.9% Xirr 9.34% (again a recent investment)
- PPF Weight 45.2%
This is the normalized portfolio evolution since its inception (Jan 2010), along with an equivalent investment in Nifty 50 TRI. This was plotted with the freefincal portfolio tracker.
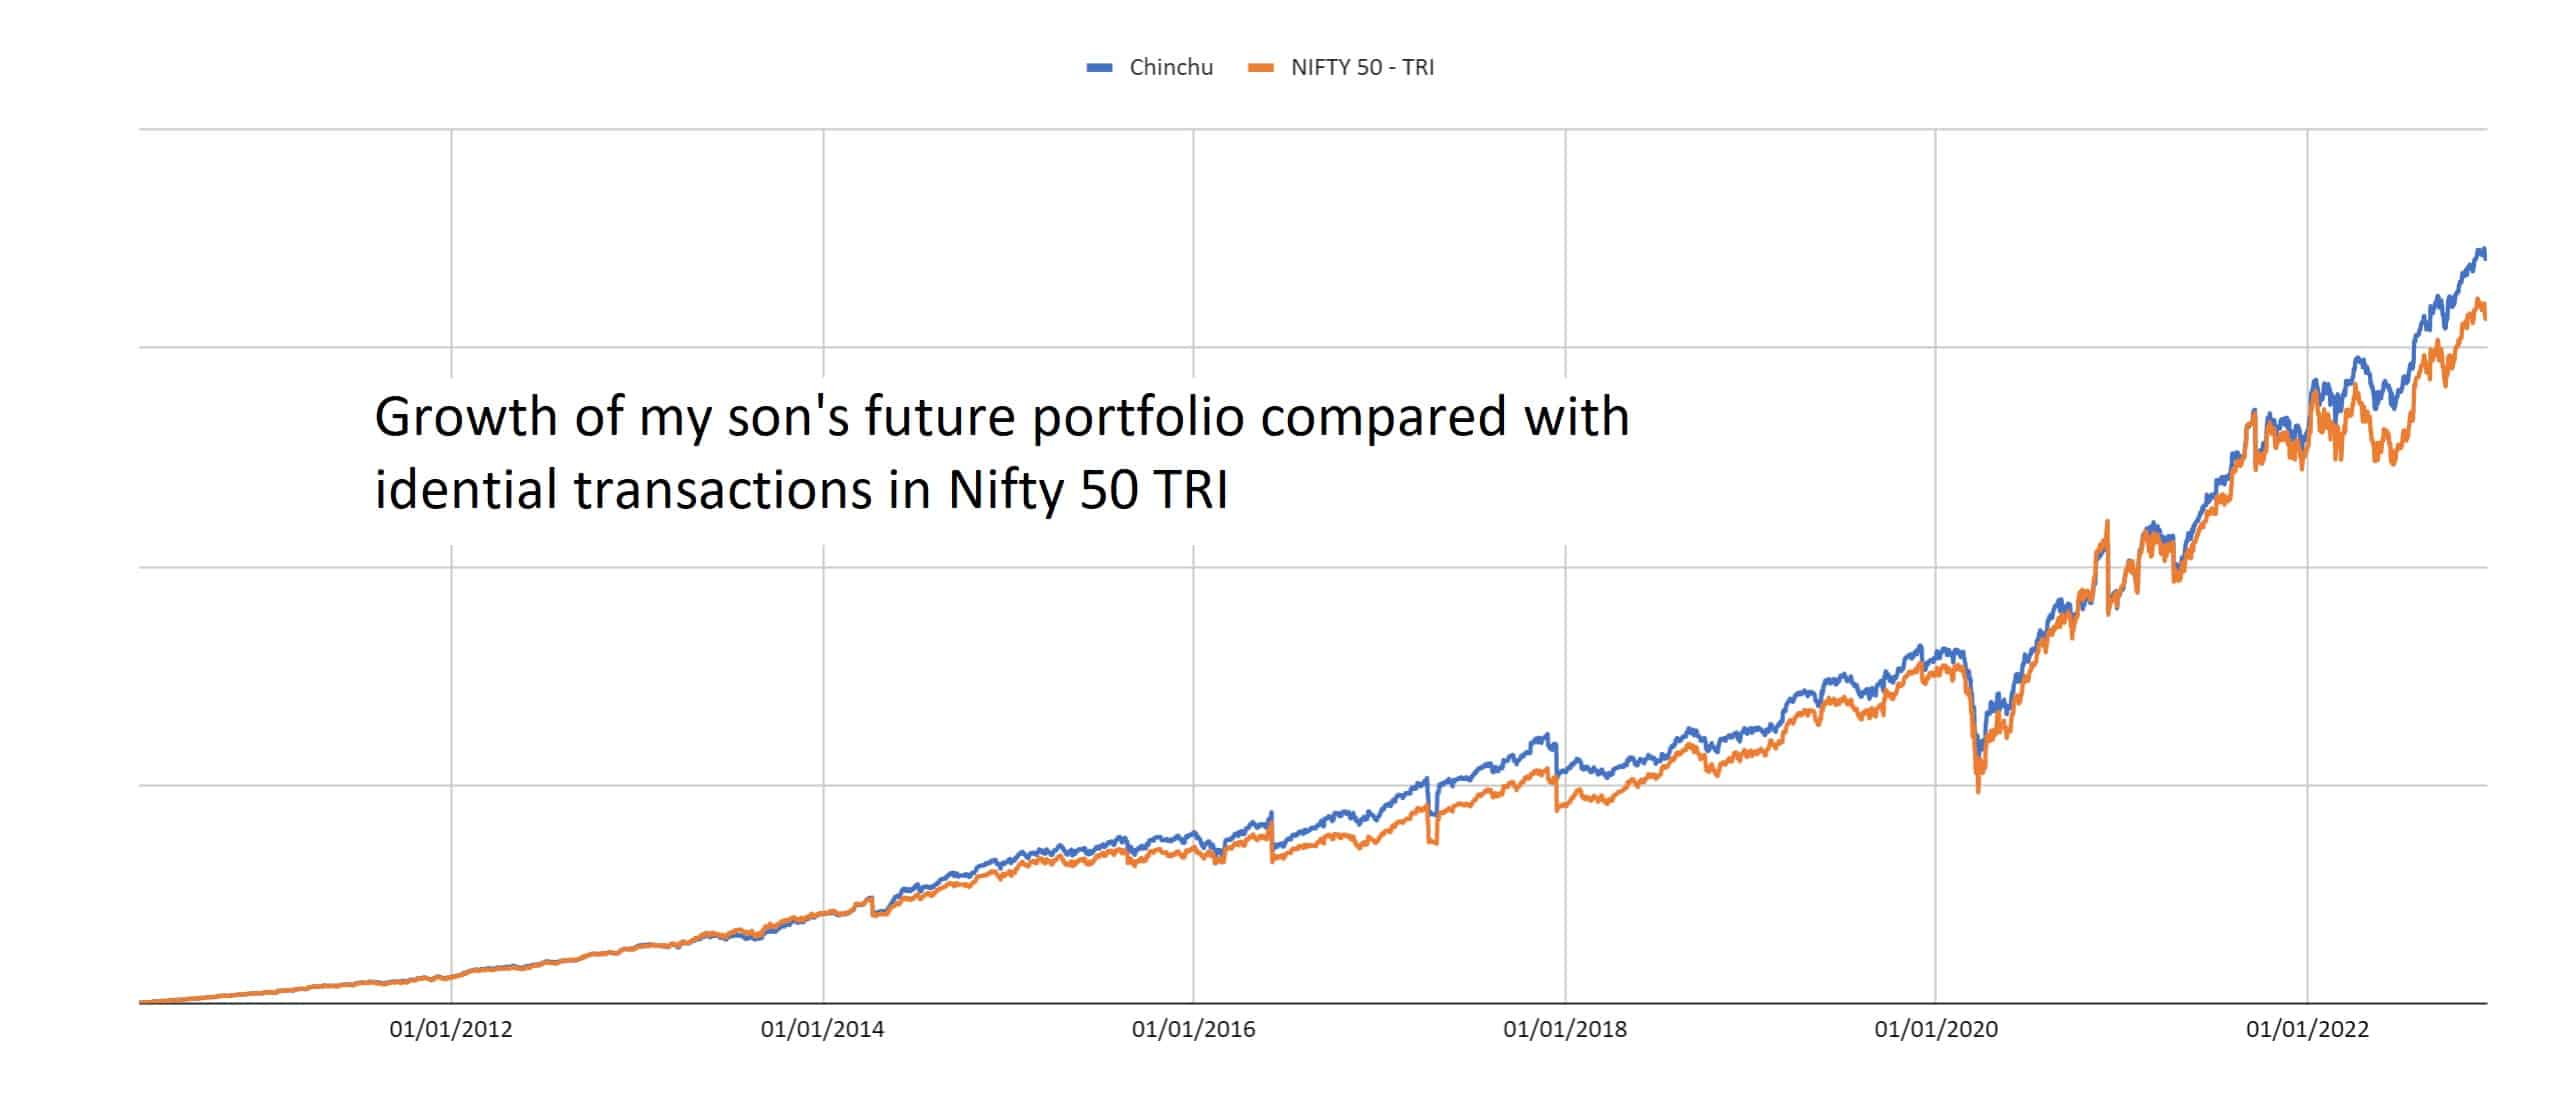
Again the outperformance should not be taken too seriously.
Outlook & Summary
The key advantages I have had is time (starting early) and starting on a clean slate. Time allows you the luxury of handling market downturns, and it also changes your risk outlook.
Ten years ago, I would have said 60% equity at age 47 is a bit much. However, I am comfortable with it today and wonder what I should do to leave it at 50-60% even after retirement. Remember, it is all about what the remaining 50-40% in fixed income is worth and building a diversified retirement portfolio. See: How to build the ideal retirement portfolio. So time changes the way we view market risk. Not starting early can be a severe handicap regarding how much risk we can take and how we handle it later.
If there is one takeaway I will urge you to consider from my journey: Invest like a machine regularly as much as you can without worrying about market movements. If you have the time and mental strength to wait* for two bull runs, your life can change, provided you keep investing regularly as much as possible. * Wait here means wait with the right asset allocation and regular goal-based risk management.
The rate I have increased my investments is higher than its XIRR. See: Why increasing investments each year is crucial for financial freedom. A lavish lifestyle or servicing too much debt can hamper our ability to pay for future goals or maintain our lifestyle in future. Finding a balance is crucial. I am still trying to find mine.
I urge readers to take advantage of the holiday season and vacation (if applicable) to evaluate how much they need to invest for their goals, tag their existing investments to different goals and plan their 2023 investment schedules. You are welcome to share this exercise as an article with freefincal readers. Here are some examples.
Reader audits published
- First audit: How Suhas tracks his MF investments and reviews financial goals.
- Second audit: How Avadhoot Joshi evaluates his investment portfolio.
- Third audit: How a single mom is on track to financial freedom
- Fourth audit: How Gowtham started goal-based investing & took control of his money
- Fifth audit: Why my financial independence & early retirement plans were postponed by four years
- Sixth audit: How Abhisek funded his marriage & is on track to financial freedom.
- Seventh audit: How Rohit’s early struggles defined his investment journey
- Eighth audit: Why my investments are still on track despite job loss and lower-income
- Ninth audit: How a retirement planning calculation scared me to take action
- Tenth audit: I made several investment mistakes but have turned my life around.
- Eleventh audit: My net worth doubled in the last financial year, thanks to patient investing!
- Update: How I achieved investing nirvana.
- Twelveth audit: My financial journey: from novice to goal-based investor.
- Thirteenth audit: My journey: from a negative net worth to goal-based investing.
- Fourteenth audit: From Fixed Deposits to Goal-based investing in MFs.
- Fifteenth audit: My 10-year financial journey – mistakes made and lessons learnt.
- Sixteenth audit (part 1): How I achieved financial independence without mutual funds or stocks.
- Sixteenth audit (part 2): Lessons from my financial independence journey and future investment plans.
- Seventeenth audit: How I plan to achieve financial independence and move to my native place
- Eighteenth audit: I used the current bull run to reduce my mutual funds from 14 to 4!
- Nineteenth audit: How a conservative investor created his financial plan
- Twentieth audit: I plan to achieve financial independence by 46; this is my master plan
- Twenty-first audit: I have made many investment mistakes but am on course to financial independence by 45.
- Twenty-second audit: I felt worthless six years ago but have achieved financial stability today
- Twenty-third audit: My financial journey was directionless until age 40: this is how I made up for lost time
- Twenty-fourth audit: Why I increased equity MF investments by 275% and reduced PPF contributions.
- Twenty-fifth audit: How I track financial goals without worrying about returns
- Twenty-sixth audit: I am 24 and started investing 1Y ago, but what am I investing for?
- Twenty-seventh audit: How we plan to achieve a retirement corpus 50 times our annual expenses.
- Twenty-eighth audit: I thought equity investing was a gamble, but now I aim to hold 60% equity for retirement
- Twenty-ninth audit: My journey: From 5 lakhs in debt to building a corpus worth six years in retirement
- Thirtieth audit: My investment journey: From random purchases to a goal-based portfolio
- Thirty-first audit: My investment journey: from product-driven to process-driven
- Thirty-second audit: How a young couple is trying to balance travelling and investing
- Thirty-third audit: My journey: From Rs. 30 bank balance to financial independence
These published audits have had a compounding effect on readers. If you would like to contribute to the DIY community in this manner, send your audits to freefincal AT Gmail. They could be published anonymously if you so desire.