In this edition of the reader story, “Two years ago, I made a decision that reshaped my relationship with money, risk, and peace of mind. Last year, I shared how after losing six months’ worth of income in futures and options (F&O) trading, I stepped away from the chaos and adopted systematic investing. It wasn’t an easy shift, but it was necessary. That phase taught me more about how not to invest than any book or course ever could.” This is what happened since then.
Opinions expressed in reader stories do not necessarily represent the views of freefincal or its editors. We must appreciate multiple solutions to the money management puzzle and empathise with diverse views. Articles are typically not checked for grammar unless it is necessary to convey the right meaning and preserve the tone and emotions of the writers.
If you would like to contribute to the DIY community in this manner, send your audits to freefincal AT Gmail dot com. You can publish them anonymously if you wish.
Please note: We welcome such articles from young earners who have just started investing. See, for example, this piece by a 29-year-old: How I track financial goals without worrying about returns. We also have a “mutual fund success stories” series. See, for example, how mutual funds helped me achieve financial independence. Now, over to the reader.
Since then, I’ve stayed away from F&O entirely—except for 2–3 isolated instances where I exited with no profit and no loss. Those moments were driven more by curiosity than conviction, and they quickly reminded me why I chose to walk away in the first place.
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
Lifestyle Evolution and Financial Discipline
Over the past two years, life has become more vibrant—and yes, a bit more expensive. Regular get-togethers, quarterly travel, and frequent badminton sessions have quietly nudged my monthly expenses up by around 10–15% of my in-hand salary. But these are conscious choices—investments in experiences, health, and happiness. Despite this lifestyle inflation, I’ve managed to keep my liabilities at zero, and that’s something I take pride in.
I also received an inheritance of ₹20 lakh, of which I’ve invested ₹7.5 lakh. The rest is being held in liquid form, earmarked for future marriage expenses. Interestingly, my partner-to-be shares a similar investment mindset—and we’re already looking forward to co-authoring the next edition of this journey together.
Insurance & Emergency Preparedness
- Term Insurance: ₹3.25 crore (₹2.5 crore from Max Life + ₹75 lakh from Kotak). I plan to double this post-marriage.
- Health Insurance: ₹8 lakh via my employer. I missed renewing my personal policy this year but plan to enhance coverage after marriage.
- Personal Accident Insurance: Currently not in place.
- Emergency Fund: Still untouched and intact—my financial safety net remains strong.
My Investment Strategy: Balanced, Disciplined, and Evolving
Equity
- I continue to invest in the same 3 stocks via SIP every 15 days, focusing on large and mid-cap companies.
- Minor adjustments were made along the way, but the core remains stable.
Mutual Funds
- Monthly SIPs continue in 4 funds:
- 1 Index Fund
- 1 Technology Fund
- 1 Focused Fund
- 1 ELSS
- I also invest in a Balanced Advantage Fund either quarterly or when its NAV rises by 5%, whichever comes first.
- Recently invested ₹5 lakh in a new Mid Cap Fund.
Sovereign Gold Bonds (SGB)
- Increased holdings from 50 to 75 units.
EPF & VPF
- Employer contributes to EPF.
- I’ve opted for 10% of my basic salary to go into VPF.
ESPP (Employee Stock Purchase Plan)
- Contribute 25% of basic salary monthly, with stock purchases every six months at a 15% discount (US-based stock).
Physical Gold
- No additional purchase. However had purchased earlier a 100g gold bar as a long-term asset.
Fixed Deposits
- Maintained an FD covering 24 months of expenses.
- Discontinued the IndMoney FD pot.
NPS
- Continuing contributions via employer (10% of basic salary).
US Stocks
- Simplified my approach due to geopolitical concerns, IndMoney issues, and 20% TCS/LRS complications.
- Now investing in 1 US stock per month, with dividends reinvested.
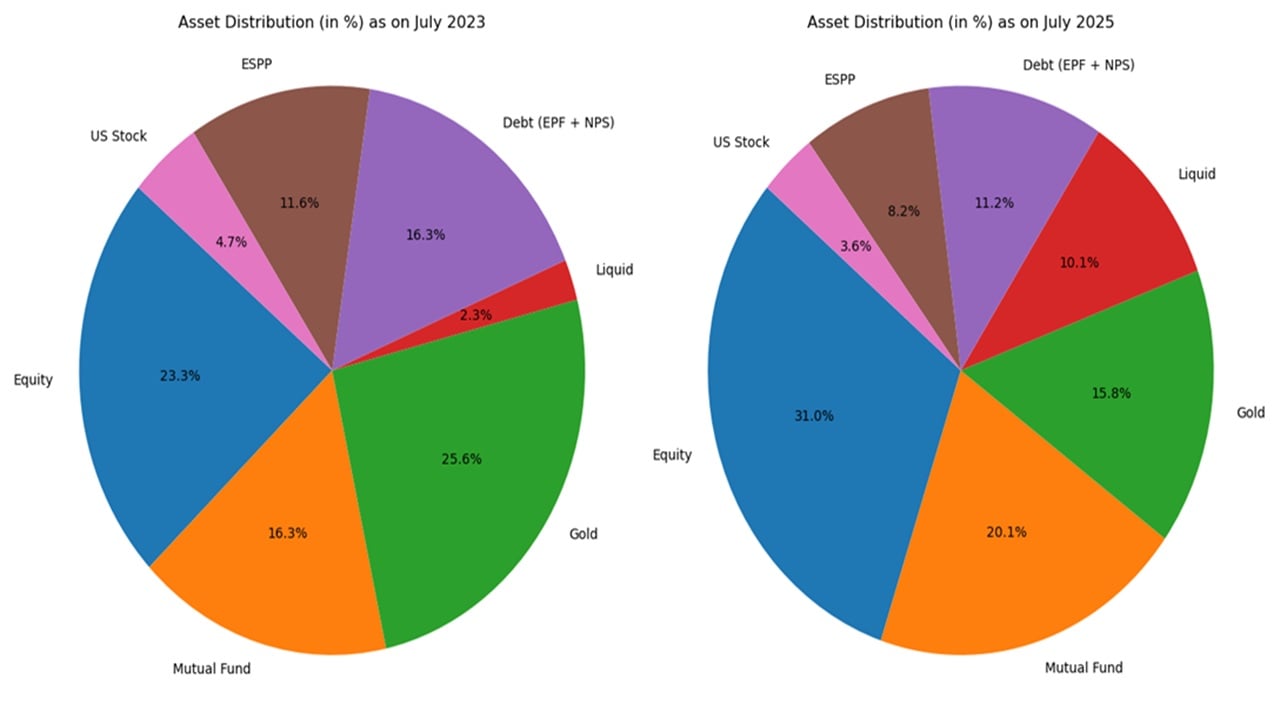
Final Thoughts: The Power of Balance
This journey has taught me that investing isn’t about chasing returns—it’s about building a life of stability, flexibility, and purpose. Balanced investing has allowed me to enjoy life today while preparing for tomorrow. I’m not aiming to beat the market; I’m aiming to stay in the game, calm, consistent, and clear-headed.
See you again in July 2027. Until then, as usual, I’ll leave you with a timeless reminder from Robert Kiyosaki:
It’s not how much money you make, but how much money you keep, how hard it works for you, and how many generations you keep it for.
Reader stories published earlier:
As regular readers may know, we publish a personal financial audit each December – this is the 2024 edition: Portfolio Audit 2024: The Annual Review of My Goal-Based Investments. We asked regular readers to share how they review their investments and track financial goals.
- First audit: How Suhas tracks his MF investments and reviews financial goals.
- Second audit: How Avadhoot Joshi evaluates his investment portfolio.
- Third audit: How a single mom is on track to financial freedom
- Fourth audit: How Gowtham started goal-based investing & took control of his money
- Fifth audit: Why my financial independence & early retirement plans were postponed by four years
- Sixth audit: How Abhisek funded his marriage & is on track to financial freedom.
- Seventh audit: How Rohit’s early struggles defined his investment journey
- Eighth audit: Why my investments are still on track despite job loss and lower income.
- Ninth audit: How a retirement planning calculation scared me to take action
- Tenth audit: I made several investment mistakes but have turned my life around.
- Eleventh audit: My net worth doubled in the last financial year, thanks to patient investing!
- Update: How I achieved investing nirvana.
- Twelveth audit: My financial journey: from novice to goal-based investor.
- Thirteenth audit: My journey: from a negative net worth to goal-based investing.
- Fourteenth audit: From Fixed Deposits to Goal-based investing in MFs.
- Fifteenth audit: My 10-year financial journey – mistakes made and lessons learnt.
- Sixteenth audit (part 1): How I achieved financial independence without mutual funds or stocks.
- Sixteenth audit (part 2): Lessons from my financial independence journey and future investment plans.
- Seventeenth audit: How I plan to achieve financial independence and move to my native place
- Eighteenth audit: I used the current bull run to reduce my mutual funds from 14 to 4!
- Nineteenth audit: How a conservative investor created his financial plan
- Twentieth audit: I plan to achieve financial independence by 46; this is my master plan
- Twenty-first audit: I have made many investment mistakes but am on course to financial independence by 45.
- Twenty-second audit: I felt worthless six years ago but have achieved financial stability today
- Twenty-third audit: My financial journey was directionless until age 40: this is how I made up for lost time
- Twenty-fourth audit: Why I increased equity MF investments by 275% and reduced PPF contributions.
- Twenty-fifth audit: How I track financial goals without worrying about returns
- Twenty-sixth audit: I am 24 and started investing 1Y ago, but what am I investing for?
- Twenty-seventh audit: How we plan to achieve a retirement corpus 50 times our annual expenses.
- Twenty-eighth audit: I thought equity investing was a gamble, but now I aim to hold 60% equity for retirement
- Twenty-ninth audit: My journey: From 5 lakhs in debt to building a corpus worth six years in retirement
- Thirtieth audit: My investment journey: From random purchases to a goal-based portfolio
- Thirty-first audit: My investment journey: from product-driven to process-driven
- Thirty-second audit: How a young couple is trying to balance travelling and investing
- Thirty-third audit: My journey: From Rs. 30 bank balance to financial independence
- Thirty-fourth audit: Our journey: From scratch to a net worth of 18 times annual expenses.
- Thirty-fifth audit: From a net worth of Rs. 6000 to auto-pilot goal-based investing
- Thirty-sixth audit: How I retired from corporate bondage at 46, two years ago!
- Thirty-seventh audit: How I learnt to keep it simple and build a net worth 19 times my annual expenses
- Thirty-eighth audit: How Abhineeth plans to achieve financial independence and build a house.
- Thirty-ninth audit: How Sahil plans to achieve financial independence by efficient tracking
- Fortieth audit: My Journey to a Ten Crore Portfolio
- Forty-first audit: Burdened with debt for several years, I am now aggressively investing in equity
- Forty-second audit: From Engineer to Librarian after Financial Independence and Early Retirement (FIRE)
- Forty-third audit: I lost six months’ income in F&O and ditched it for systematic investing
- Forty-fourth audit: My retirement plan to handle the harsh realities of the IT industry
- Forty-fifth audit: My investment journey: mistakes, 10 years of MF investing and recovery
- Forty-sixth audit: My MF portfolio is worth six crores despite multiple mistakes
- Forty-seventh audit: Saving, Investing, and Running Marathons: My 25-year Journey to Financial Independence
- Forty-eighth audit: Never Too Late to Start: How I Became Financially Savvy at 40
- Forty-ninth audit: My Investment Journey to a net worth 29 times my annual expenses
- Fiftieth audit: How I audit my portfolio without tracking returns
- Fifty-first audit: Financial Lessons Learned During and After a PhD
- Fifty-second audit: Investment & Financial journey of a 23 year old
- Fifty-third audit: The system I use to draw income and spend after retirement securely
- Fifty-fourth audit: From Start-Up Employee to Millionaire: A Success Story of Resilience and Smart Investing
- Fifty-fifth audit: 25-Year-Old Software Engineer’s Investment Journey: From Stocks to Mutual Funds and Beyond
- Fifty-sixth audit: Crossing the Million Mark: Our Journey to the First Crore
- Fifty-seventh audit: Navigating Market Volatility: How an IT Professional Transformed His Investment Approach for Retirement
- Fifty-eighth audit: How Sahil achieved a 10X retirement corpus by efficient portfolio tracking
- FIfty-ninth audit: How I achieved financial freedom by 45 without onsite assignments or ESOPs
- Sixtieth audit: Building Wealth on a Government Salary: Lessons Learned
- Sixty-first audit: Minimalism, Index Funds, and Staying Calm: My Investing Journey at 28
- Sixty-second audit: Building Wealth and Breaking Barriers: How Swati Took Control of Her Financial Future
- Sixty-third audit: My financial journey: How I missed the Compounding Bus!
- Sixty-fourth audit: My MF investment journey: From thematic funds to a 3-fund portfolio
These published audits have had a compounding effect on readers. If you would like to contribute to the DIY community in this manner, send your audits to freefincal AT Gmail. You can also publish them anonymously.