We are back again with our fourth yearly audit of our financial health (the first three parts are linked below). A huge thanks to the numerous yearly audits posted on freefincal – we were also motivated to document ours, at least once a year. Thankfully, we are doing this for the fourth year in a row – and we would like to continue in years to come.
Our previous audits
- How a young couple is trying to balance travelling and investing
- How a young couple tries to balance their personal and financial aspirations
- How a couple reached their desired asset allocation after starting late
Before we begin, a very brief background about us: I (Arka) and my wife (Rupali) got married in 2020 (just before the pandemic). I am currently 37, and we started our financial planning seriously only after our marriage, which was in 2020. I work in IT Consulting, and Rupali is in Tax Consulting. We have surely started late, but we are trying to ramp up the investments to cover it while managing our huge love for travel.
Opinions published in reader stories need not represent the views of freefincal or its editors. We must appreciate multiple solutions to the money management puzzle and empathise with diverse views. Articles are typically not checked for grammar unless it is necessary to convey the right meaning and preserve the tone and emotions of the writers.
If you would like to contribute to the DIY community in this manner, send your audits to freefincal AT Gmail dot com. You can publish them anonymously if you wish.
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
Please note: We welcome such articles from young earners who have just started investing. See, for example, this piece by a 29-year-old: How I track financial goals without worrying about returns. We also have a “mutual fund success stories” series. See, for example, how mutual funds helped me achieve financial independence.
One major update in our financial planning this year was consulting a fee-only financial planner. It was of great help, to say the least. The single-pane-of-glass view he helped us with was something missing from our planning.
Since we were primarily planning for retirement only to date, we realised we have other upcoming goals (house purchase, kids (yet to happen though), etc. ) that need a holistic professional view. It was a great decision to consult him. However, since we finished our consultation only in March 2024, not much of this year’s audit is impacted, but it will be from the next one. Now let’s dive in.
Basics:
First things first, let’s review our basics as of March 2024
Emergency Cash :
4 months of current mandatory expenses (in case where both of us stopped earning) and not to be touched upon (in case the higher earning person stopped earning).
The runway in the scenario of “both of us stopped working” decreased one month compared to last year. Due to increased savings towards house down-payment. However we may plan to increase this a bit or include 6 months home loan EMI to it when we purchase the house
Health Insurance:
- 10L base + 50L Super Top Up (Self and Wife)
- 10L base + 15L Super Top up (Parents)
Both of these are taken outside office health insurance and parents are not added in office health insurance.
Term Plan
- 6 years of current annual income (self)
- 5 years of current annual income (wife)
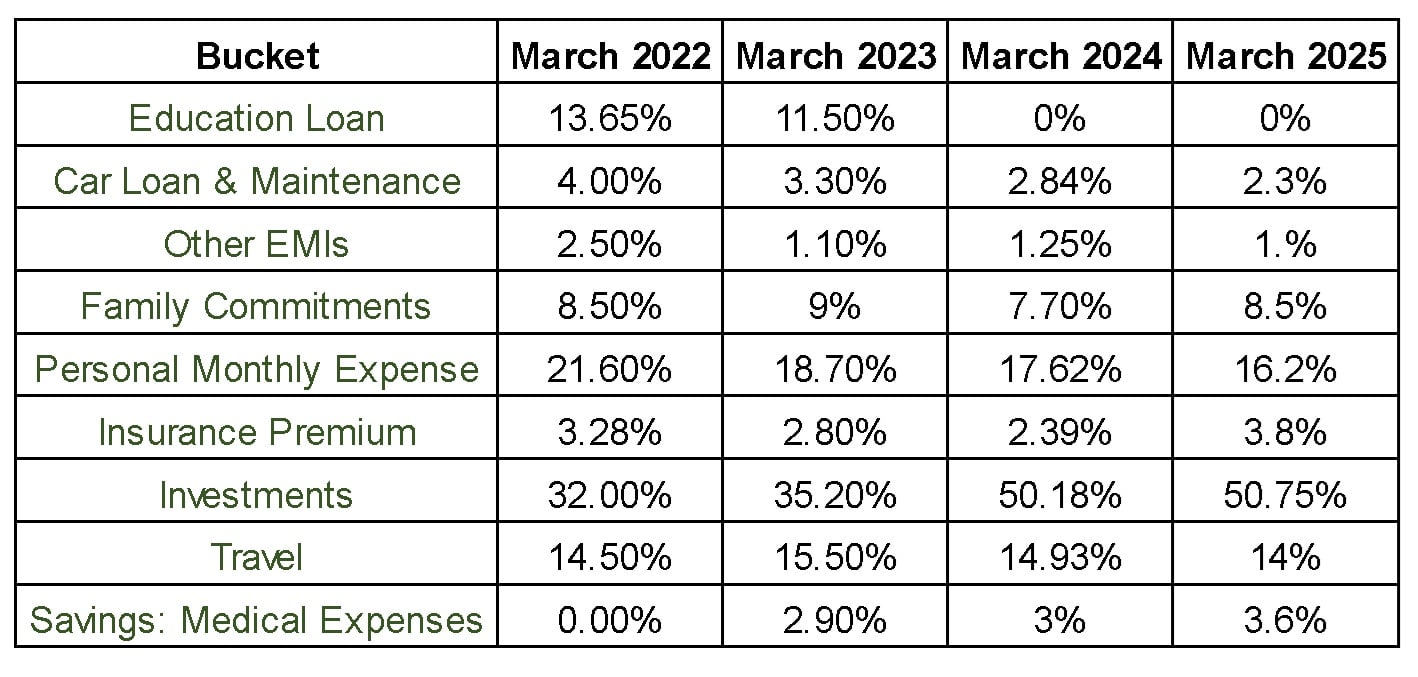
Income distribution: Below is the monthly distribution in different buckets of investments and expenses as a percentage of monthly earnings and how it has changed over the years.
Key observations compared to last year
- Expenses in each bucket more or less remained same – family commitments have increased a bit due to some native house maintenance work
- Insurance premium includes term and medical insurance (both us and parents)
- The extra earning is primarily channelized for investments and house downpayment funds.
- Travel is one of our primary expense buckets, as both of us like to travel, hence keep a significant amount to fulfill our travel dreams. To compensate for that, we minimize discretionary spending like shopping and eating outs throughout the year and consider this travel corpus as our extended emergency bucket. We document our travel in our website and YouTube channel. Would love it if you have a look. Last year we took my father to one of his dream destinations, Masai Mara.
You can read it here : Masai Mara from India under INR 75k
Goal: Coming to the goals we have the following ones as on date
- Retirement Goal (Considering another 18 years away). Don’t mind working till our mid 50s (if possible !!).
However, we will try to achieve financial independence (FI) before that. As of now the target is to reach 40 years of expense as corpus
- Buying a house – Here things have again changed from last year. Until last year our house purchase goal was almost 5-7 years away, but we decided to preponed it. Hence for the last few months jacked up the investments towards the downpayment. We may need to sell some part of our other investments if the downpayment fund doesn’t suffice – thanks to our financial planner, got a great visibility here
- Currently don’t have any kids and will plan as and when the situation changes
Investments:
- For emergency fund, 100% is in savings accounts (including FD)
- For retirement, asset allocation is as follows.
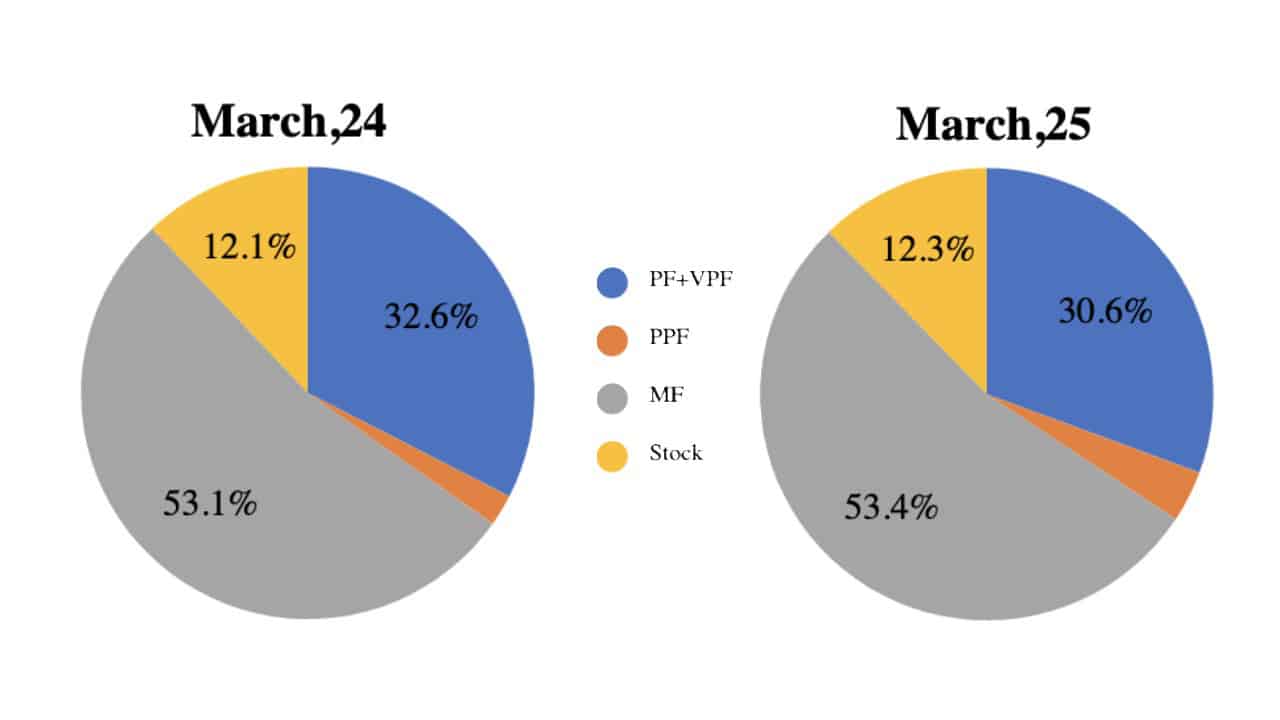
The aggressive investment in equity has increased the equity percentage from 56% in March 2023 to 65% in March 2024 and the it remained same in March 2025 as well.
However from this year onwards – we are adding up more liquid debt investments and wish to maintain the balance between 60 to 65% of equity and rest in debt
As of now below is the portfolio composition of mutual fund (which constitutes 53% of the retirement corpus) and direct equity (which constitutes 12% of the retirement corpus)
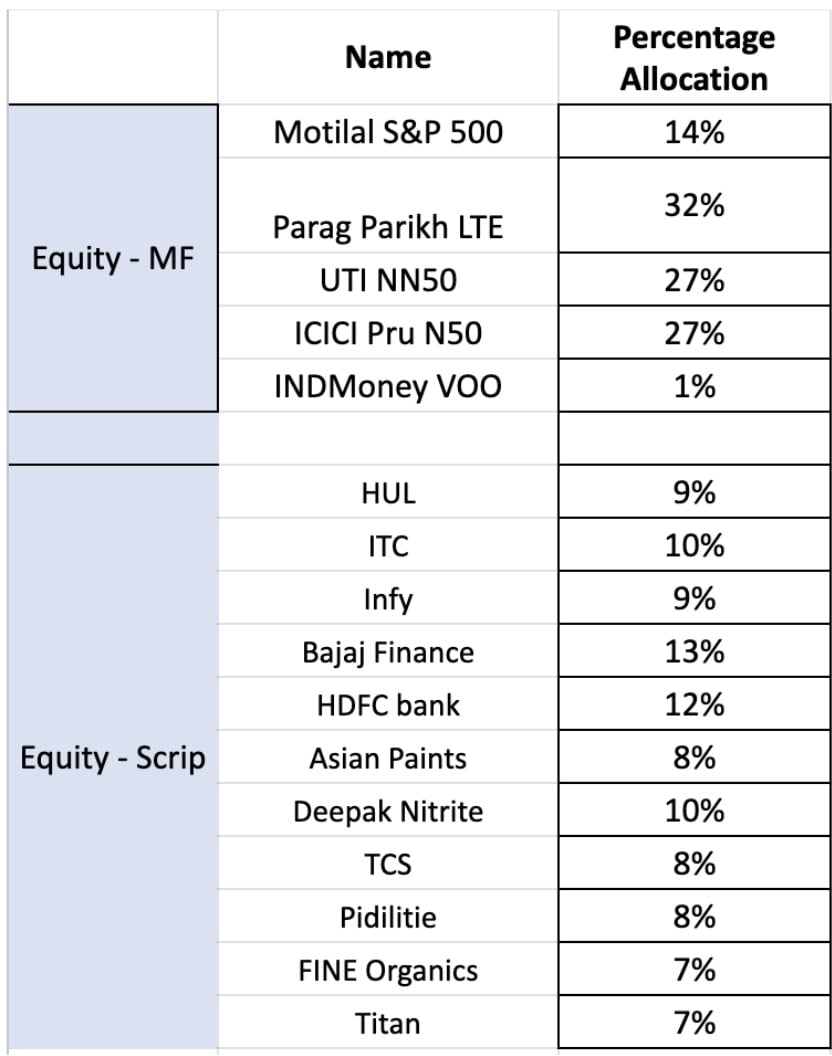
Direct Equity investment has not performed really well this year, hence the percentage in overall corpus remains same. The expectation from direct equity is to create a stable source of dividend income over the years. Currently dividends are getting reinvested.
Performance:
- The first and the most important parameter of the performance is the retirement corpus. As of March 2024 it was close to 5.5 years – it remained kind of same this year also due to underperformance of equity market, extra saving towards house downpayment fund and some recalculation of Retirement expenses
- Below is the XIRR for equity MFs. . The stock portfolio is at a absolute return is close to 10% (way underperforming for now

Plan for 2025-26:
- Planning to close the house downpayment fund and keep it ready for any good house we like. At the same time keep contributing maximum possible for retirement funds and just right for other goals.
- From a personal goals perspective, just trying to remain healthy with less eating out, regular exercise, remaining active and having enough water and sleep.
In the end, I want to thank Pattu sir for the opportunity and the amazing FB group of AIFW – my one stop solution for finance, career related things. Even for a passive member like me, just by reading posts, comments, analysis – it has been immensely fulfilling.
I hope this group grows bigger and wiser !!
Reader stories published earlier:
As regular readers may know, we publish a personal financial audit each December – this is the 2023 edition: Portfolio Audit 2023: The Annual Review of My Goal-Based Investments. We asked regular readers to share how they review their investments and track financial goals.
- First audit: How Suhas tracks his MF investments and reviews financial goals.
- Second audit: How Avadhoot Joshi evaluates his investment portfolio.
- Third audit: How a single mom is on track to financial freedom
- Fourth audit: How Gowtham started goal-based investing & took control of his money
- Fifth audit: Why my financial independence & early retirement plans were postponed by four years
- Sixth audit: How Abhisek funded his marriage & is on track to financial freedom.
- Seventh audit: How Rohit’s early struggles defined his investment journey
- Eighth audit: Why my investments are still on track despite job loss and lower income.
- Ninth audit: How a retirement planning calculation scared me to take action
- Tenth audit: I made several investment mistakes but have turned my life around.
- Eleventh audit: My net worth doubled in the last financial year, thanks to patient investing!
- Update: How I achieved investing nirvana.
- Twelveth audit: My financial journey: from novice to goal-based investor.
- Thirteenth audit: My journey: from a negative net worth to goal-based investing.
- Fourteenth audit: From Fixed Deposits to Goal-based investing in MFs.
- Fifteenth audit: My 10-year financial journey – mistakes made and lessons learnt.
- Sixteenth audit (part 1): How I achieved financial independence without mutual funds or stocks.
- Sixteenth audit (part 2): Lessons from my financial independence journey and future investment plans.
- Seventeenth audit: How I plan to achieve financial independence and move to my native place
- Eighteenth audit: I used the current bull run to reduce my mutual funds from 14 to 4!
- Nineteenth audit: How a conservative investor created his financial plan
- Twentieth audit: I plan to achieve financial independence by 46; this is my master plan
- Twenty-first audit: I have made many investment mistakes but am on course to financial independence by 45.
- Twenty-second audit: I felt worthless six years ago but have achieved financial stability today
- Twenty-third audit: My financial journey was directionless until age 40: this is how I made up for lost time
- Twenty-fourth audit: Why I increased equity MF investments by 275% and reduced PPF contributions.
- Twenty-fifth audit: How I track financial goals without worrying about returns
- Twenty-sixth audit: I am 24 and started investing 1Y ago, but what am I investing for?
- Twenty-seventh audit: How we plan to achieve a retirement corpus 50 times our annual expenses.
- Twenty-eighth audit: I thought equity investing was a gamble, but now I aim to hold 60% equity for retirement
- Twenty-ninth audit: My journey: From 5 lakhs in debt to building a corpus worth six years in retirement
- Thirtieth audit: My investment journey: From random purchases to a goal-based portfolio
- Thirty-first audit: My investment journey: from product-driven to process-driven
- Thirty-second audit: How a young couple is trying to balance travelling and investing
- Thirty-third audit: My journey: From Rs. 30 bank balance to financial independence
- Thirty-fourth audit: Our journey: From scratch to a net worth of 18 times annual expenses.
- Thirty-fifth audit: From a net worth of Rs. 6000 to auto-pilot goal-based investing
- Thirty-sixth audit: How I retired from corporate bondage at 46, two years ago!
- Thirty-seventh audit: How I learnt to keep it simple and build a net worth 19 times my annual expenses
- Thirty-eighth audit: How Abhineeth plans to achieve financial independence and build a house.
- Thirty-ninth audit: How Sahil plans to achieve financial independence by efficient tracking
- Fortieth audit: My Journey to a Ten Crore Portfolio
- Forty-first audit: Burdened with debt for several years, I am now aggressively investing in equity
- Forty-second audit: From Engineer to Librarian after Financial Independence and Early Retirement (FIRE)
- Forty-third audit: I lost six months’ income in F&O and ditched it for systematic investing
- Forty-fourth audit: My retirement plan to handle the harsh realities of the IT industry
- Forty-fifth audit: My investment journey: mistakes, 10 years of MF investing and recovery
- Forty-sixth audit: My MF portfolio is worth six crores despite multiple mistakes
- Forty-seventh audit: Saving, Investing, and Running Marathons: My 25-year Journey to Financial Independence
- Forty-eighth audit: Never Too Late to Start: How I Became Financially Savvy at 40
- Forty-ninth audit: My Investment Journey to a net worth 29 times my annual expenses
- Fiftieth audit: How I audit my portfolio without tracking returns
- Fifty-first audit: Financial Lessons Learned During and After a PhD
- Fifty-second audit: Investment & Financial journey of a 23 year old
- Fifty-third audit: The system I use to draw income and spend after retirement securely
- Fifty-fourth audit: From Start-Up Employee to Millionaire: A Success Story of Resilience and Smart Investing
- Fifty-fifth audit: 25-Year-Old Software Engineer’s Investment Journey: From Stocks to Mutual Funds and Beyond
- Fifty-sixth audit: Crossing the Million Mark: Our Journey to the First Crore
- Fifty-seventh audit: Navigating Market Volatility: How an IT Professional Transformed His Investment Approach for Retirement
- Fifty-eighth audit: How Sahil achieved a 10X retirement corpus by efficient portfolio tracking
- FIfty-ninth audit: How I achieved financial freedom by 45 without onsite assignments or ESOPs
- Sixtieth audit: Building Wealth on a Government Salary: Lessons Learned
- Sixty-first audit: Minimalism, Index Funds, and Staying Calm: My Investing Journey at 28
- Sixty-second audit: Building Wealth and Breaking Barriers: How Swati Took Control of Her Financial Future
- Sixty-third audit: My financial journey: How I missed the Compounding Bus!
- Sixty fourth audit: How I came out of F&O Addiction and depression to build wealth
These published audits have had a compounding effect on readers. If you would like to contribute to the DIY community in this manner, send your audits to freefincal AT Gmail. If you so desire, you can publish them anonymously.