In Aug 2024, we published a reader story about a young earner’s journey to one crore and plans to build further wealth: Crossing the Million Mark: Our Journey to the First Crore. This is an update.
About this series: I am grateful to readers for sharing intimate details about their financial lives, which benefits us all. Some of the previous editions are linked at the bottom of this article. You can also access the full reader story archive.
Opinions expressed in reader stories do not necessarily represent the views of freefincal or its editors. We must appreciate multiple solutions to the money management puzzle and empathise with diverse views. Articles are typically not checked for grammar unless necessary to convey the right meaning and preserve the tone and emotions of the writers.
If you would like to contribute to the DIY community in this manner, send your audits to freefincal AT Gmail dot com. They can be published anonymously if you so desire.
Please note: We welcome such articles from young earners who have just started investing. See, for example, this piece by a 29-year-old: How I track financial goals without worrying about returns. We have also started a new “mutual fund success stories” series. This is the first edition: How mutual funds helped me reach financial independence. Now, over to the reader.
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
First, some background. I come from a Defence background where, to be candid, we often faced financial constraints due to familial responsibilities that my father, as the eldest child, had to manage. My exposure to investing began during my college years. In contrast, my wife hails from a well-established IT background with exposure to investing since childhood. We both completed our B.Tech. degrees, with me graduating in 2018 and my wife in 2019. My parents stretched their resources, even taking a loan, to secure my admission to a Tier-1 Private College in Chennai, while my wife opted for a regular college in Hyderabad.
Both of us started our careers with the same company at the age of 22. We got married during the COVID-19 pandemic, managing to keep expenses under 10 lakhs. Beginning in the IT sector with entry-level salaries, we understood the challenges of being at the bottom of the pay scale. Despite this, we stayed with our first company longer than anticipated before realising our potential for growth and deciding to move on to positions with higher earning potential.
- The past year was challenging, both personally and in the markets.
- Two major life events happened: I left my job at PwC after a year due to burnout, and we sadly experienced a miscarriage after three months.
- FY25 became a year of learning and adapting — the markets tested our patience, and personal events influenced our financial choices.
- Our total pre-tax household active income for FY25 was ₹50 lakh. We also received about ₹30,000 in dividends from our holding companies.
- There was a one-time windfall of ₹25 lakh from a family real estate sale.
- The % growth compared to last year is skewed due to this windfall. Excluding it, the actual income growth comes to around 67%, i.e., ₹50.3 lakh.
| Income Source | FY24 | FY25 | % Change |
|---|---|---|---|
| Salary | ₹30L | ₹50L | 66% |
| Dividends | ₹20k | ₹30k | 50% |
| Rental Income | ₹0 | ₹0 | 0% |
| Side Hustle | ₹0 | ₹0 | 0% |
| Windfall Income | ₹0 | ₹25L | NA |
| Total | ₹30.2L | ₹75.3L | 150% |
Expense Summary
- Our total annual expenses were around ₹24.30 Lakhs.
- Travel continues to be our biggest discretionary expense. Over the past year, we took trips to Singapore, Bali, Meghalaya (with family), Goa, and Andaman (with family). In FY26, we’ve already completed a week-long workation in Kerala, with upcoming trips planned to Goa and Japan.
- As part of family support, we contribute monthly to my parents, even though they are financially independent and still working. Their investments have largely been in debt instruments, making them relatively unfamiliar with equities. To help them gradually build comfort with equity exposure, we’ve opened a mutual fund account in their name, which I fund indirectly. This will allow them to diversify their portfolio as they approach retirement in FY29.
| Expense Category | Amount (₹) | % of Total |
|---|---|---|
| Household | 6 Lakhs | 24.9% |
| Travel | 12 Lakhs | 50% |
| Healthcare | 30,000 | 0.2% |
| Education | Nil | Nil |
| Miscellaneous | 6 Lakhs | 24.9% |
| Total | 24.30 Lakhs | 100% |
- Savings rate = (Income – Expenses) / Income = (75.3L – 24.30L ) / 75.3L = 63%
*The calculation is again skewed by the windfall received during the year. After excluding it, the savings rate stands at 50%, which aligns with our annual target.
Investment Performance
- We track our overall portfolio across four family members — myself, my wife, and my parents — covering Equity, Debt, Gold, and Other investments.
- We exclude real estate from our investment calculations as it is primarily for self-use, has irregular valuations, and lacks liquidity. Real estate will only be factored in if and when an actual sale occurs and proceeds are realized.
- We monitor both absolute returns and percentage growth, while also comparing our portfolio performance against benchmarks such as Nifty, Sensex, and relevant mutual fund indices.
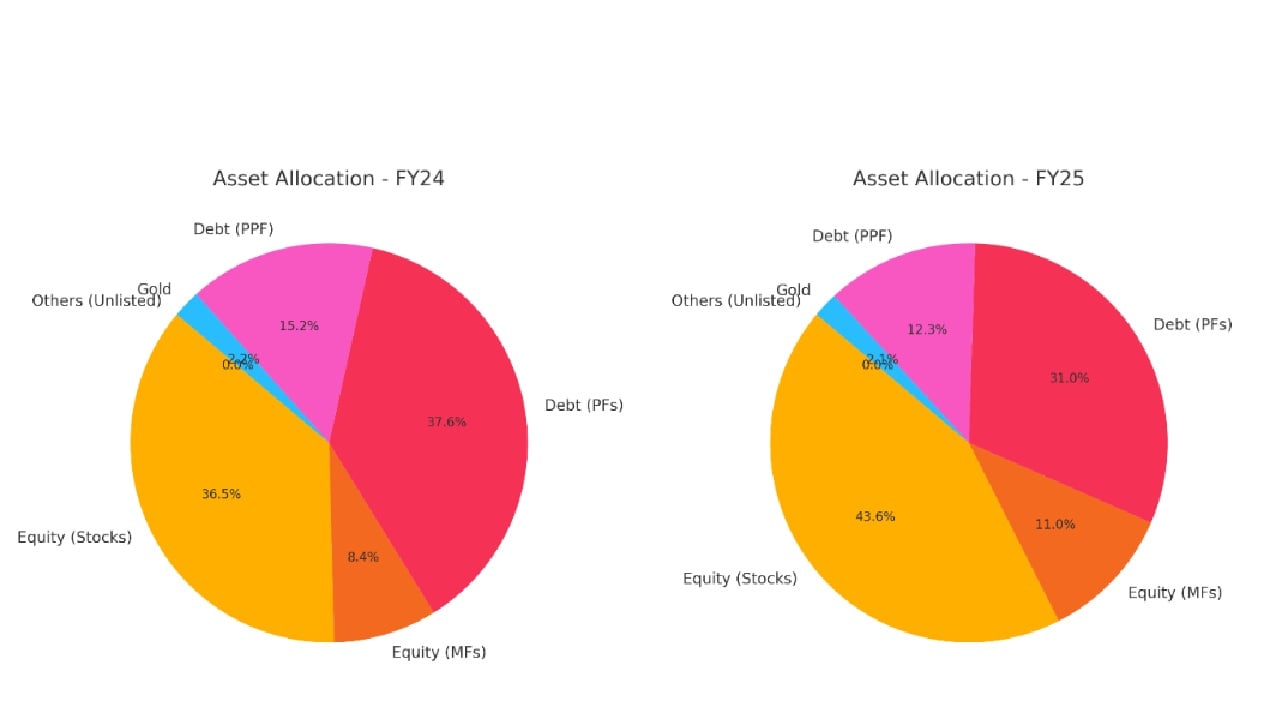
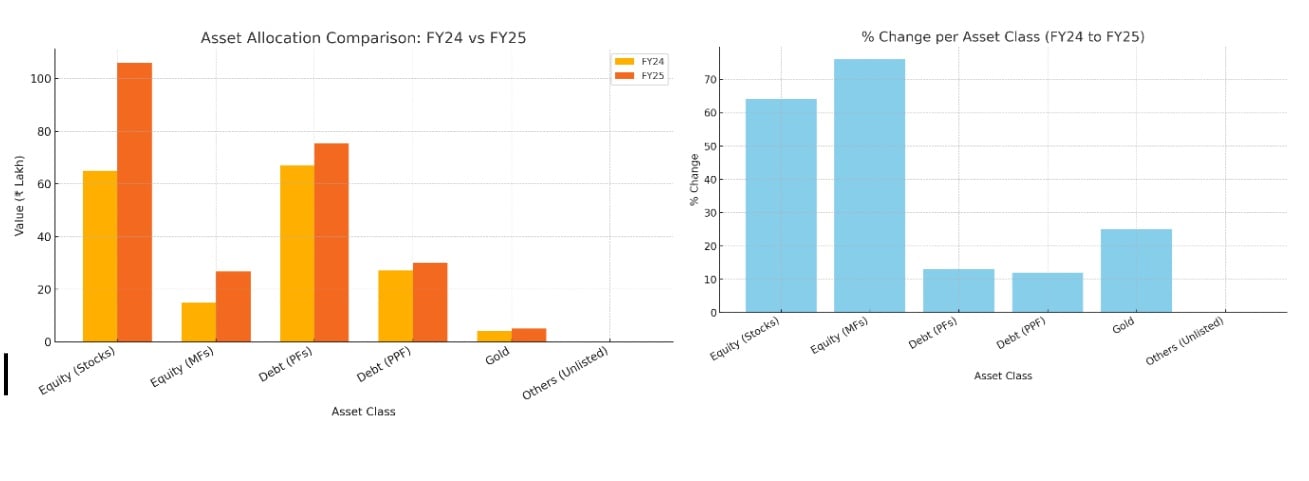
- The returns on stocks and mutual funds have seen a significant rise this year, largely due to deploying a major portion of the windfall directly into the markets. In addition, multiple Systematic Withdrawal Plans (SWPs) have been initiated from a funded arbitrage account.
| Asset Class | Value (FY24) | Value (FY25) | % Change |
|---|---|---|---|
| Equity ( Stocks ) | 65 L | 1.06 Cr | 64% |
| Equity ( MFs ) | 15 L | 26.70 L | 76% |
| Debt ( PFs ) | 67 L | 75.5 L | 13% |
| Debt ( PPF ) | 27 L | 30 L | 12% |
| Gold | 4 L | 5 L | 25% |
| Others (Unlisted) | Nil | Nil | Nil |
| Total | 1.78 Cr | 2.43 Cr |
Net Worth Update
- Opening Net Worth in Mar’2024: 1.78 Cr
- Closing Net Worth April’2025: 2.43 Cr
- 37% change YoY in the NW backed by market recovery from the earlier drop of 30% from PF-all time high.
Key Learnings & Mistakes
- What worked well: Our equity portfolio saw a sharp 30% dip from its all-time high in October but fully recovered over the following six months.
- What didn’t work: We missed the opportunity to add to our equity positions during the downturn. This was mainly because of financial commitments towards a planned family vacation and my ongoing job transition.
- Behavioural observations: Despite the 30% drop, we stayed calm and focused on analysing which stocks presented the best opportunities to add once funds were available. Diversification across the portfolio gave us peace of mind and reduced anxiety about any single holding.
- Market takeaway: Markets reward those who stay invested and avoid turning temporary paper losses into permanent ones.
Changes in Financial Goals
- Our Financial Independence (FI/FU) target is to reach the $1 million mark, which is based on our current projections, should be achievable by FY32 — about 7 years from now.
- The goal for the upcoming year is to grow our combined net worth to ₹3.23 crore, which represents a 33% increase from the current year.
Action Plan for FY26
- We are making better use of credit card rewards to help offset travel expenses, especially for flights and accommodations.
- Our overall asset allocation remains conservative at the family portfolio level, with a 55:45 split between Equity and Debt.
- We’ve started exploring turnaround opportunities, particularly where company insiders are increasing their ownership during market downturns.
- No changes have been made to our budgeting approach, as things are progressing according to plan.
- We post our monthly numbers along with any portfolio changes at direct equity level on Twitter (@FundaInvesting) regularly.
Closing Thoughts
- Some things in life are simply beyond our control. The best we can do is accept them and keep moving forward. Life will always have its share of ups and downs, and no one can ever say with certainty whether “this time it’s different.”.
- Thank you for reading this far. If you have any questions or thoughts, feel free to drop them — I’ll be happy to answer and discuss.
- This is for informational purposes only, not financial advice.
Reader stories published earlier:
As regular readers may know, we publish a personal financial audit each December – this is the 2024 edition: Portfolio Audit 2024: The Annual Review of My Goal-Based Investments. We asked regular readers to share how they review their investments and track financial goals.
- First audit: How Suhas tracks his MF investments and reviews financial goals.
- Second audit: How Avadhoot Joshi evaluates his investment portfolio.
- Third audit: How a single mom is on track to financial freedom
- Fourth audit: How Gowtham started goal-based investing & took control of his money
- Fifth audit: Why my financial independence & early retirement plans were postponed by four years
- Sixth audit: How Abhisek funded his marriage & is on track to financial freedom.
- Seventh audit: How Rohit’s early struggles defined his investment journey
- Eighth audit: Why my investments are still on track despite job loss and lower income.
- Ninth audit: How a retirement planning calculation scared me to take action
- Tenth audit: I made several investment mistakes but have turned my life around.
- Eleventh audit: My net worth doubled in the last financial year, thanks to patient investing!
- Update: How I achieved investing nirvana.
- Twelveth audit: My financial journey: from novice to goal-based investor.
- Thirteenth audit: My journey: from a negative net worth to goal-based investing.
- Fourteenth audit: From Fixed Deposits to Goal-based investing in MFs.
- Fifteenth audit: My 10-year financial journey – mistakes made and lessons learnt.
- Sixteenth audit (part 1): How I achieved financial independence without mutual funds or stocks.
- Sixteenth audit (part 2): Lessons from my financial independence journey and future investment plans.
- Seventeenth audit: How I plan to achieve financial independence and move to my native place
- Eighteenth audit: I used the current bull run to reduce my mutual funds from 14 to 4!
- Nineteenth audit: How a conservative investor created his financial plan
- Twentieth audit: I plan to achieve financial independence by 46; this is my master plan
- Twenty-first audit: I have made many investment mistakes but am on course to financial independence by 45.
- Twenty-second audit: I felt worthless six years ago but have achieved financial stability today
- Twenty-third audit: My financial journey was directionless until age 40: this is how I made up for lost time
- Twenty-fourth audit: Why I increased equity MF investments by 275% and reduced PPF contributions.
- Twenty-fifth audit: How I track financial goals without worrying about returns
- Twenty-sixth audit: I am 24 and started investing 1Y ago, but what am I investing for?
- Twenty-seventh audit: How we plan to achieve a retirement corpus 50 times our annual expenses.
- Twenty-eighth audit: I thought equity investing was a gamble, but now I aim to hold 60% equity for retirement
- Twenty-ninth audit: My journey: From 5 lakhs in debt to building a corpus worth six years in retirement
- Thirtieth audit: My investment journey: From random purchases to a goal-based portfolio
- Thirty-first audit: My investment journey: from product-driven to process-driven
- Thirty-second audit: How a young couple is trying to balance travelling and investing
- Thirty-third audit: My journey: From Rs. 30 bank balance to financial independence
- Thirty-fourth audit: Our journey: From scratch to a net worth of 18 times annual expenses.
- Thirty-fifth audit: From a net worth of Rs. 6000 to auto-pilot goal-based investing
- Thirty-sixth audit: How I retired from corporate bondage at 46, two years ago!
- Thirty-seventh audit: How I learnt to keep it simple and build a net worth 19 times my annual expenses
- Thirty-eighth audit: How Abhineeth plans to achieve financial independence and build a house.
- Thirty-ninth audit: How Sahil plans to achieve financial independence by efficient tracking
- Fortieth audit: My Journey to a Ten Crore Portfolio
- Forty-first audit: Burdened with debt for several years, I am now aggressively investing in equity
- Forty-second audit: From Engineer to Librarian after Financial Independence and Early Retirement (FIRE)
- Forty-third audit: I lost six months’ income in F&O and ditched it for systematic investing
- Forty-fourth audit: My retirement plan to handle the harsh realities of the IT industry
- Forty-fifth audit: My investment journey: mistakes, 10 years of MF investing and recovery
- Forty-sixth audit: My MF portfolio is worth six crores despite multiple mistakes
- Forty-seventh audit: Saving, Investing, and Running Marathons: My 25-year Journey to Financial Independence
- Forty-eighth audit: Never Too Late to Start: How I Became Financially Savvy at 40
- Forty-ninth audit: My Investment Journey to a net worth 29 times my annual expenses
- Fiftieth audit: How I audit my portfolio without tracking returns
- Fifty-first audit: Financial Lessons Learned During and After a PhD
- Fifty-second audit: Investment & Financial journey of a 23 year old
- Fifty-third audit: The system I use to draw income and spend after retirement securely
- Fifty-fourth audit: From Start-Up Employee to Millionaire: A Success Story of Resilience and Smart Investing
- Fifty-fifth audit: 25-Year-Old Software Engineer’s Investment Journey: From Stocks to Mutual Funds and Beyond
- Fifty-sixth audit: Crossing the Million Mark: Our Journey to the First Crore
- Fifty-seventh audit: Navigating Market Volatility: How an IT Professional Transformed His Investment Approach for Retirement
- Fifty-eighth audit: How Sahil achieved a 10X retirement corpus by efficient portfolio tracking
- FIfty-ninth audit: How I achieved financial freedom by 45 without onsite assignments or ESOPs
- Sixtieth audit: Building Wealth on a Government Salary: Lessons Learned
- Sixty-first audit: Minimalism, Index Funds, and Staying Calm: My Investing Journey at 28
- Sixty-second audit: Building Wealth and Breaking Barriers: How Swati Took Control of Her Financial Future
- Sixty-third audit: My financial journey: How I missed the Compounding Bus!
- Sixty-fourth audit: My MF investment journey: From thematic funds to a 3-fund portfolio
- Sixty-fifth audit: How I learnt that investing is about finding the balance and not chasing returns
These published audits have had a compounding effect on readers. If you would like to contribute to the DIY community in this manner, send your audits to freefincal AT Gmail. You can also publish them anonymously.