Last Updated on March 4, 2025 at 9:49 am
In this edition of the reader story, we meet a software professional and certified table tennis coach from Coimbatore.
I am a 40-year-old software professional/ITTF-certified Table Tennis coach based out of Coimbatore. My wife is a homemaker, and I have a daughter who is 3.5 years old. I started working in 2006. Until December 2019, I didn’t know any principles of investing/financial planning and why it is needed. The only investment amount I had was in the EPF and savings account.
Financial mistakes made so far.
- Took a home loan for a 2BHK for 30L in 2009 and paid EMI of 27k until the end of 2020.
- Didn’t have term insurance until mid-2021.
- In 2021, I took the term plan with few riders. Didn’t have a personal health plan for the family until 2017.
- Equity allocation till Jan 2020 was 0%
I was forced to take a money-back policy from SBI while my dad applied for a home loan at my native place.
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
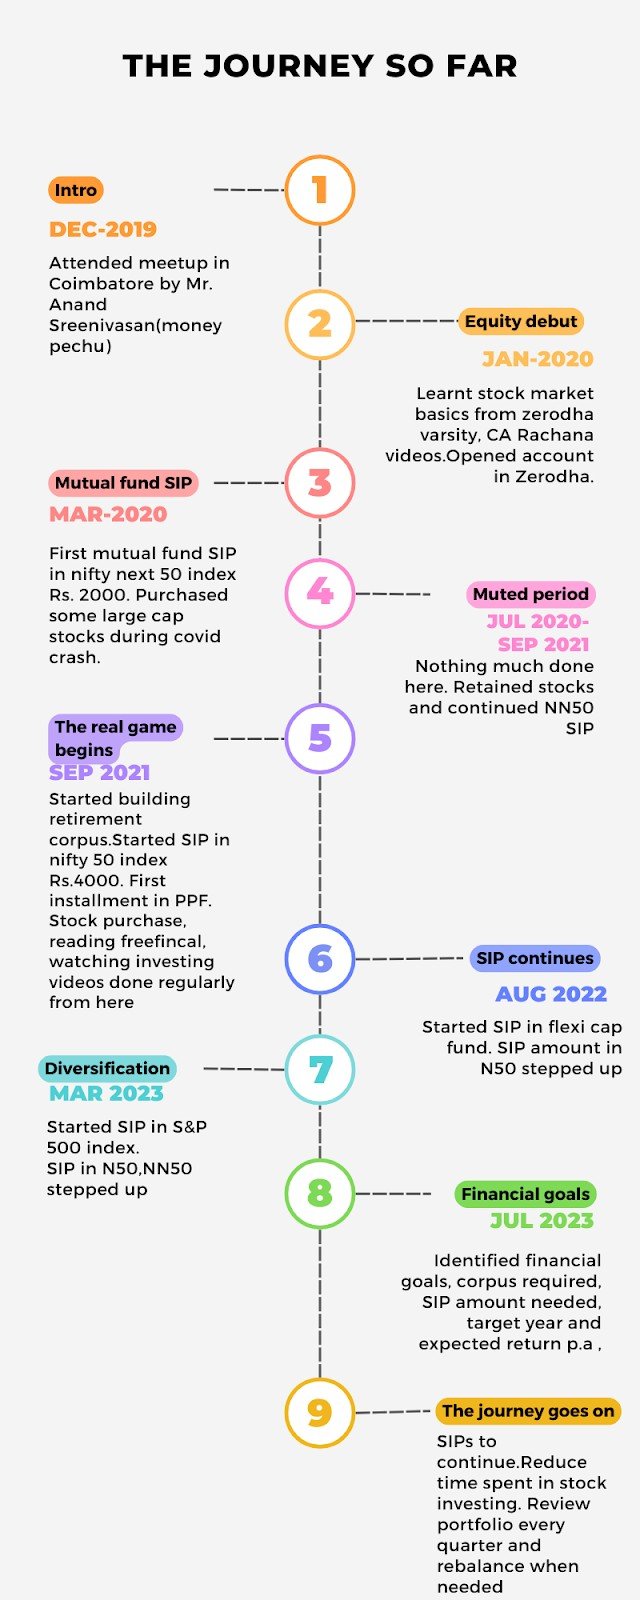
Investment journey timeline:
Current scenario
- Living in an independent home(owned by my dad) with my family & parents.
- I rented out the apartment I purchased.
- No debt. No EMIs.
- No stress if I lose my primary IT job. I have a minimum 1-year financial buffer before I can find a new opportunity.
- Working remotely since 2017. Daily commute time to the office is saved, and there is no travel stress.
- I have been passionate about sports since childhood. I run and coach at a table tennis academy with around 50 kids. This also serves as a passive income.
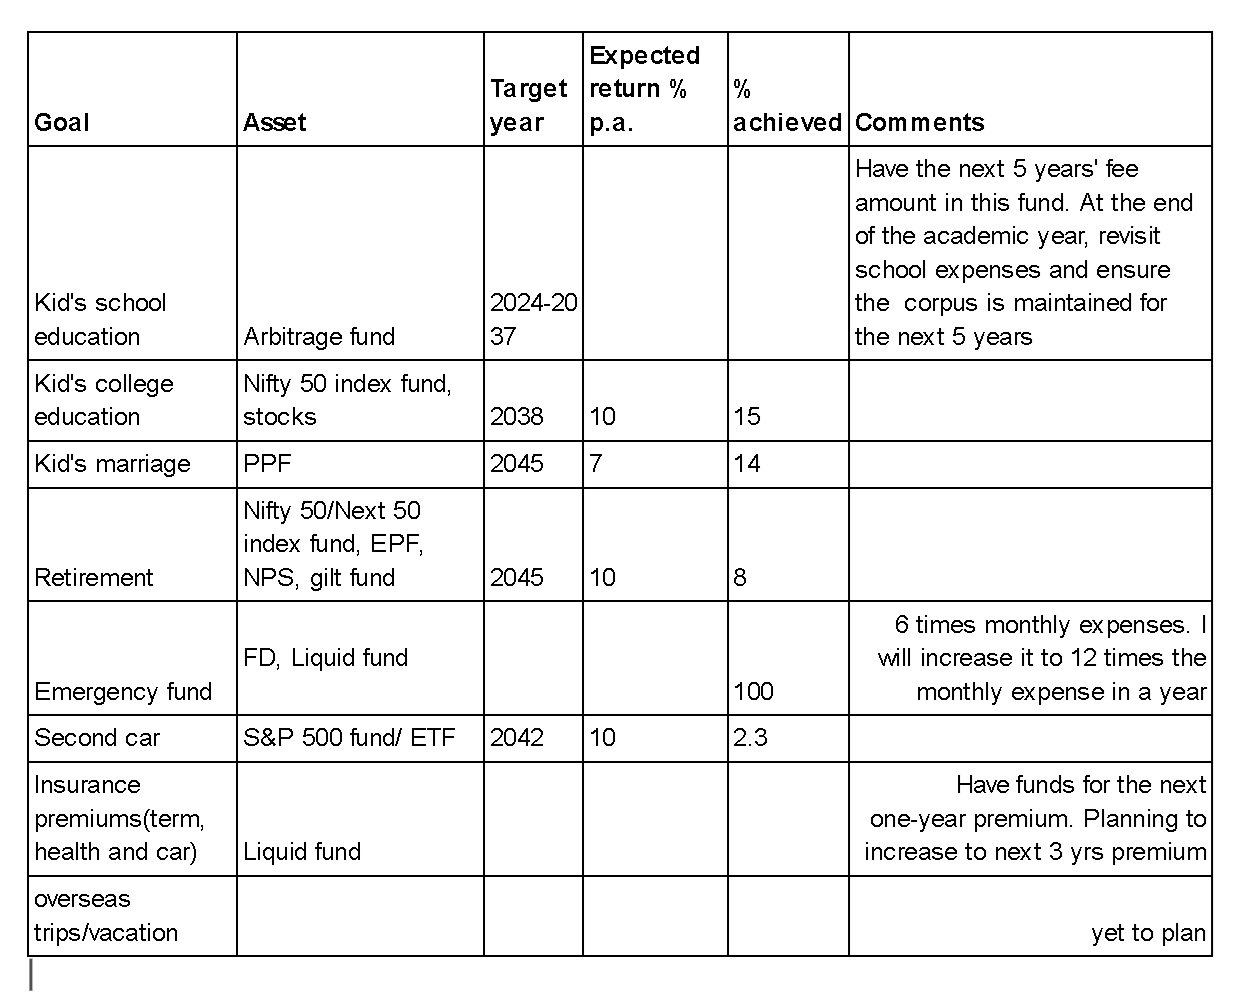
Major financial goals:
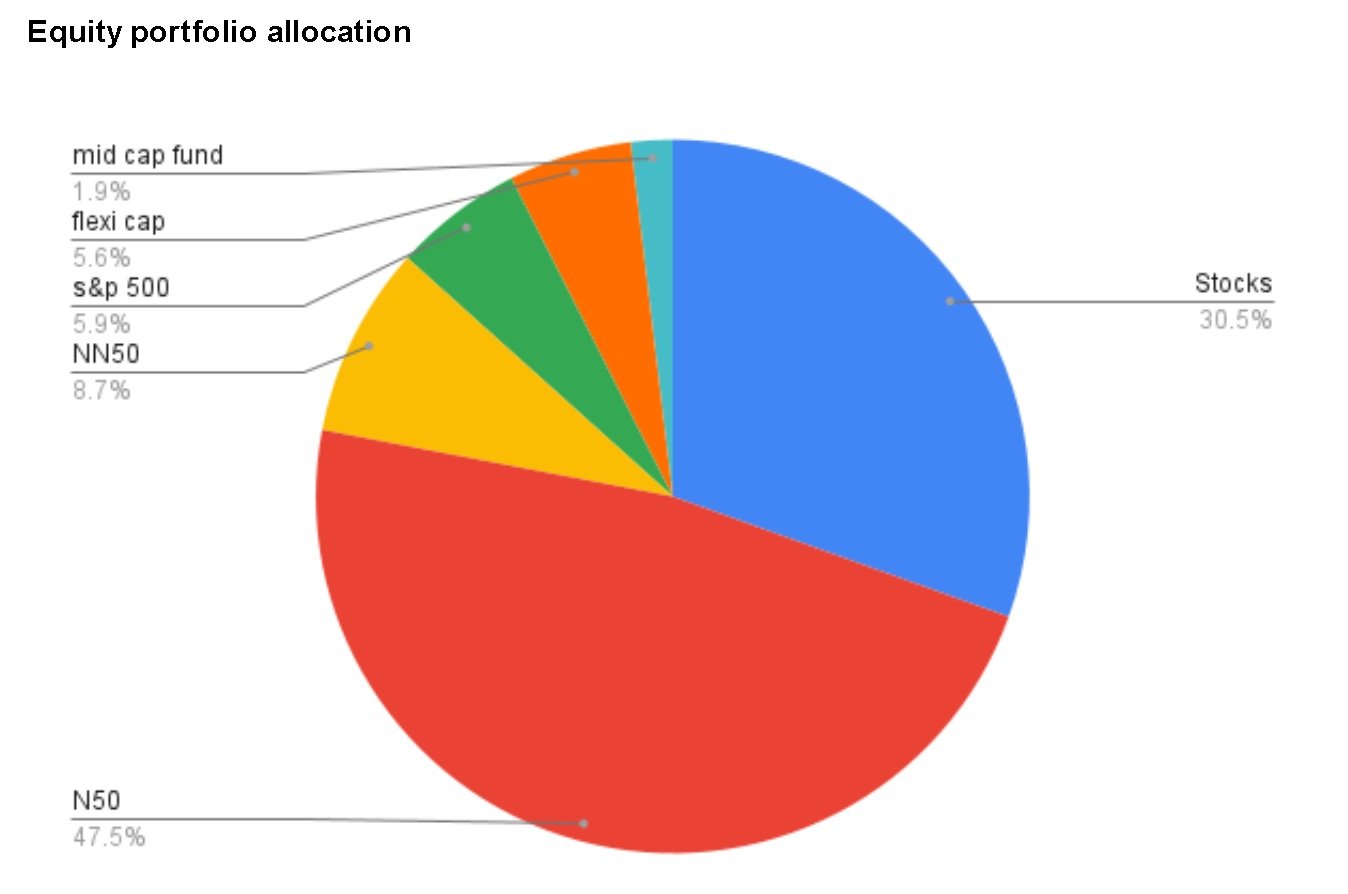
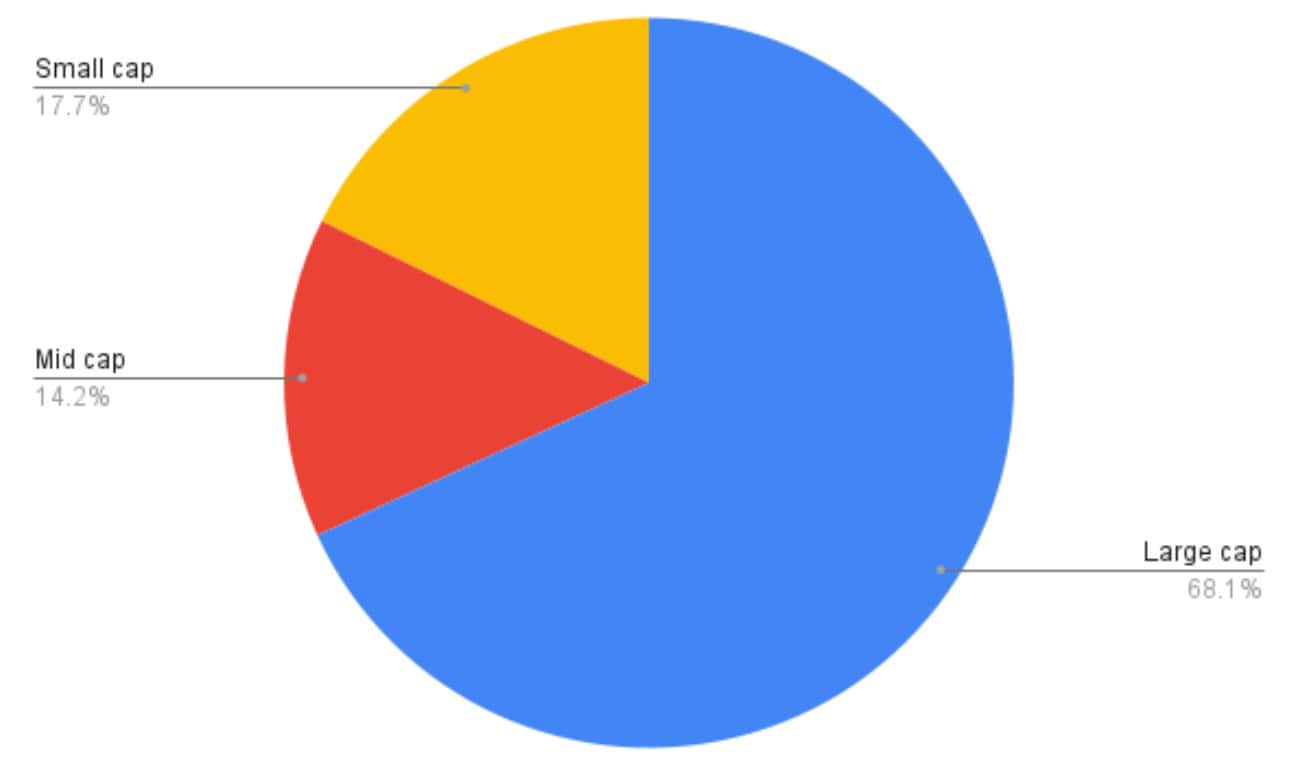
Stock allocation by market cap (Not more than 10% allotted to one stock)
Returns so far (XIRR from Kuvera)
- N50 index – 12.7%
- NN50 index – 17.7%
- Gilt fund – 9.5%
- Flexi cap – 23.8%
- S&P 500 index – 28.7%
- S&P ETF – 20.8%
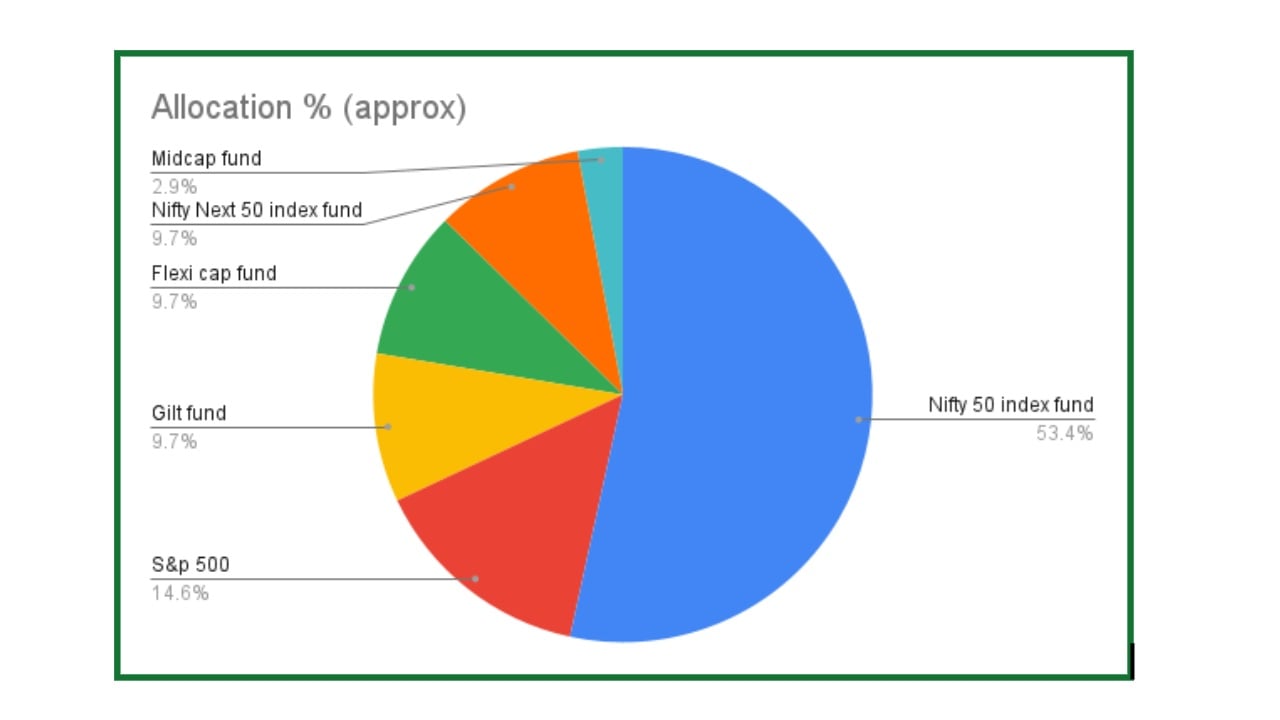
Current SIP allocation (as of Jan 2025)
Started with 2000 SIP per month in Mar 2020. Regularly stepping up SIPs since then. The majority of my monthly savings is invested into SIPs as of Jan-2025. When I have excess money(after SIPs and monthly expenses), I invest in liquid/ultra short-term funds and gradually STP to the N50 index.
Tools/apps used:
- Zerodha – stocks
- Kuvera – MF investing
- Vested – US ETF
- Axio – Expense tracker
- Google sheet – for portfolio, asset allocation, financial goals tracking
Corrective actions taken:
- Bought a personal health policy in 2017 – 5L per member. Gradually increased the insured amount to 20L for each family member.
- After reading a few articles on freefincal, I cancelled the term insurance policy in 2021, took a plain vanilla term plan with no riders and increased the sum assured in 2024 to 25 times the annual expense.
- Tracking monthly expenses since mid-2021 mainly to calculate retirement corpus and emergency fund.
- Surrendered SBI money-back policy in 2022 and invested the maturity amount in equity.
- By mid-2024, identify each goal’s financial goals and associated asset class(es).
- I stopped blindly buying stocks after watching finfluencers videos.
Future plans:
- I will consult a registered advisor to review my financial plan and to seek help in rebalancing for specific goals.
- Trim down the stock portfolio to approx. 10% of total equity, so I need not invest too much time maintaining the stock portfolio
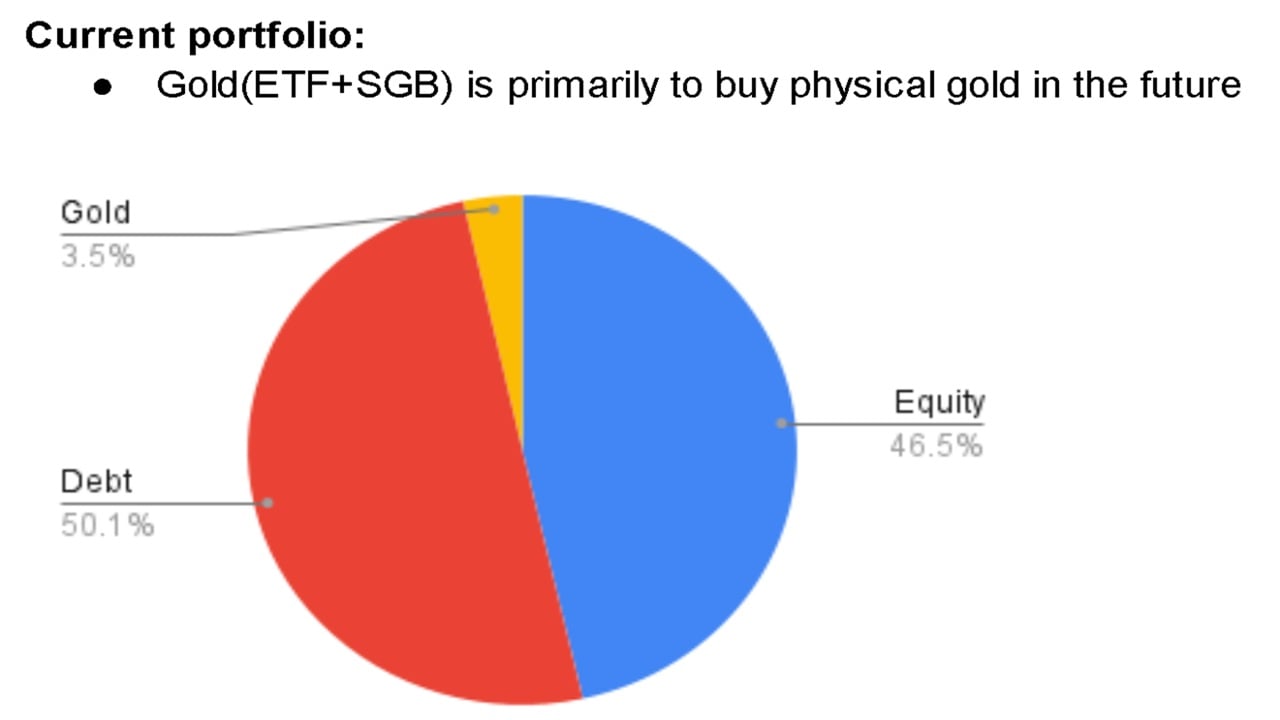
- Increase equity allocation to 60% in the next few years.
- We will reduce the allocation of a few stocks, which are currently more than 5%, to minimize the risk.
- Give importance to health and work/life balance, and don’t go overboard chasing money or returns from investment.
- Not too keen on F.I.R.E numbers. I will be happy if I meet my retirement corpus number.
- Upskill consistently both for my IT and table tennis coaching career. Reduce the time spent watching influencers’ YouTube videos.
Few takeaways:
- Mutual funds and stock market terms may seem complicated for newbies. But once you start investing and learn, you will get a grasp of these terms.
- If you want to master any skill, focus on smaller efforts regularly for a longer period. Consistency is the key – be it career progression, building a huge corpus, mastering art, music, sports, etc.,
- Try to get better at what you do each day. Don’t compare your progression/salary/lifestyle with peers.
I sincerely thank Pattu sir and the freefincal community for all the learnings I have tried to incorporate into my financial journey so far.
Reader stories published earlier:
As regular readers may know, we publish a personal financial audit each December – this is the 2023 edition: Portfolio Audit 2023: The Annual Review of My Goal-Based Investments. We asked regular readers to share how they review their investments and track financial goals.
- First audit: How Suhas tracks his MF investments and reviews financial goals.
- Second audit: How Avadhoot Joshi evaluates his investment portfolio.
- Third audit: How a single mom is on track to financial freedom
- Fourth audit: How Gowtham started goal-based investing & took control of his money
- Fifth audit: Why my financial independence & early retirement plans were postponed by four years
- Sixth audit: How Abhisek funded his marriage & is on track to financial freedom.
- Seventh audit: How Rohit’s early struggles defined his investment journey
- Eighth audit: Why my investments are still on track despite job loss and lower income.
- Ninth audit: How a retirement planning calculation scared me to take action
- Tenth audit: I made several investment mistakes but have turned my life around.
- Eleventh audit: My net worth doubled in the last financial year, thanks to patient investing!
- Update: How I achieved investing nirvana.
- Twelveth audit: My financial journey: from novice to goal-based investor.
- Thirteenth audit: My journey: from a negative net worth to goal-based investing.
- Fourteenth audit: From Fixed Deposits to Goal-based investing in MFs.
- Fifteenth audit: My 10-year financial journey – mistakes made and lessons learnt.
- Sixteenth audit (part 1): How I achieved financial independence without mutual funds or stocks.
- Sixteenth audit (part 2): Lessons from my financial independence journey and future investment plans.
- Seventeenth audit: How I plan to achieve financial independence and move to my native place
- Eighteenth audit: I used the current bull run to reduce my mutual funds from 14 to 4!
- Nineteenth audit: How a conservative investor created his financial plan
- Twentieth audit: I plan to achieve financial independence by 46; this is my master plan
- Twenty-first audit: I have made many investment mistakes but am on course to financial independence by 45.
- Twenty-second audit: I felt worthless six years ago but have achieved financial stability today
- Twenty-third audit: My financial journey was directionless until age 40: this is how I made up for lost time
- Twenty-fourth audit: Why I increased equity MF investments by 275% and reduced PPF contributions.
- Twenty-fifth audit: How I track financial goals without worrying about returns
- Twenty-sixth audit: I am 24 and started investing 1Y ago, but what am I investing for?
- Twenty-seventh audit: How we plan to achieve a retirement corpus 50 times our annual expenses.
- Twenty-eighth audit: I thought equity investing was a gamble, but now I aim to hold 60% equity for retirement
- Twenty-ninth audit: My journey: From 5 lakhs in debt to building a corpus worth six years in retirement
- Thirtieth audit: My investment journey: From random purchases to a goal-based portfolio
- Thirty-first audit: My investment journey: from product-driven to process-driven
- Thirty-second audit: How a young couple is trying to balance travelling and investing
- Thirty-third audit: My journey: From Rs. 30 bank balance to financial independence
- Thirty-fourth audit: Our journey: From scratch to a net worth of 18 times annual expenses.
- Thirty-fifth audit: From a net worth of Rs. 6000 to auto-pilot goal-based investing
- Thirty-sixth audit: How I retired from corporate bondage at 46, two years ago!
- Thirty-seventh audit: How I learnt to keep it simple and build a net worth 19 times my annual expenses
- Thirty-eighth audit: How Abhineeth plans to achieve financial independence and build a house.
- Thirty-ninth audit: How Sahil plans to achieve financial independence by efficient tracking
- Fortieth audit: My Journey to a Ten Crore Portfolio
- Forty-first audit: Burdened with debt for several years, I am now aggressively investing in equity
- Forty-second audit: From Engineer to Librarian after Financial Independence and Early Retirement (FIRE)
- Forty-third audit: I lost six months’ income in F&O and ditched it for systematic investing
- Forty-fourth audit: My retirement plan to handle the harsh realities of the IT industry
- Forty-fifth audit: My investment journey: mistakes, 10 years of MF investing and recovery
- Forty-sixth audit: My MF portfolio is worth six crores despite multiple mistakes
- Forty-seventh audit: Saving, Investing, and Running Marathons: My 25-year Journey to Financial Independence
- Forty-eighth audit: Never Too Late to Start: How I Became Financially Savvy at 40
- Forty-ninth audit: My Investment Journey to a net worth 29 times my annual expenses
- Fiftieth audit: How I audit my portfolio without tracking returns
- Fifty-first audit: Financial Lessons Learned During and After a PhD
- Fifty-second audit: Investment & Financial journey of a 23 year old
- Fifty-third audit: The system I use to draw income and spend after retirement securely
- Fifty-fourth audit: From Start-Up Employee to Millionaire: A Success Story of Resilience and Smart Investing
- Fifty-fifth audit: 25-Year-Old Software Engineer’s Investment Journey: From Stocks to Mutual Funds and Beyond
- Fifty-sixth audit: Crossing the Million Mark: Our Journey to the First Crore
- Fifty-seventh audit: Navigating Market Volatility: How an IT Professional Transformed His Investment Approach for Retirement
- Fifty-eighth audit: How Sahil achieved a 10X retirement corpus by efficient portfolio tracking
- FIfty-ninth audit: How I achieved financial freedom by 45 without onsite assignments or ESOPs
- Sixtieth audit: Building Wealth on a Government Salary: Lessons Learned
- Sixty-first audit: Minimalism, Index Funds, and Staying Calm: My Investing Journey at 28
- Sixty-second audit: Building Wealth and Breaking Barriers: How Swati Took Control of Her Financial Future
These published audits have had a compounding effect on readers. If you would like to contribute to the DIY community in this manner, send your audits to freefincal AT Gmail. They could be published anonymously if you so desire.