I’m happy to share my financial journey on this platform and would like to thank Pattu Sir for giving me the opportunity. I have structured my journey into three sections: Family Background, Financial Mistakes, and Course Correction.
Opinions published in reader stories need not represent the views of freefincal or its editors. We must appreciate multiple solutions to the money management puzzle and empathise with diverse views. Articles are typically not checked for grammar unless necessary to convey the right meaning and preserve the tone and emotions of the writers.
If you would like to contribute to the DIY community in this manner, send your audits to freefincal AT Gmail dot com. They can be published anonymously if you so desire.
Please note: We welcome such articles from young earners who have just started investing. See, for example, this piece by a 29-year-old: How I track financial goals without worrying about returns. We also have a “mutual fund success stories” series. See, for example, how mutual funds helped me achieve financial independence. Now, over to the reader.
Family Background
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
I hate to start with a cliché, but I come from a poor family. More than the financial struggles, the difficult home situation made my childhood a bit sour.
I lost my mother to a heart condition during high school. During her illness, my father, who was a construction labourer in the gulf, returned home with signs of mental illness, which later turned into schizophrenia. We depleted all our savings for her treatment, leaving only 50k when she passed away.
My maternal grandmother stood with us (me and my younger brother) and supported us in continuing our studies.
During childhood, basic necessities were a luxury for us. My acquaintances often recognised my clothes more than my name, as I wore the same pair of outfits all year.
Long story short, I was convinced that through education, only I can lift my family out of this situation. I pursued my studies with a single mind.
After completing my master’s I started working as a research assistant in a research institute in Bangalore in 2011.
I worked there for two years with a stipend of 16k-18k. I would send some money to my family and save the rest to fund my ambition of pursuing a PhD abroad.
In 2013, I went to Europe for my PhD and stayed there for 7 years. During this time, I got married and blessed with one kid.
Financial Mistakes
I was earning and saving well during that period, but I wasn’t investing. I was quite naive about financial matters and had no understanding of concepts like inflation. I used to believe that lending money for interest was wrong. This mindset led to several financial mistakes.
Here are some of them:
(1) Just like houseflies are drawn to honey, relatives and friends would often ask me for money, and I would lend it to them. When I started asking for the money back, I lost both the relationships and the money in many cases. In some instances, I managed to recover only part of the amount or just the principal. A good portion of the money is still tied up here.
(2) I bought real estate with a loan in my hometown. Although I managed to clear the loan over the next few years, the location of the plot was on the outskirts, leading to a very modest appreciation in the land value.
(3) I purchased endowment LIC policies for both myself and my father. At that time, I was only aware of FDs and LIC policies as investment options, so I bought these policies through an agent.
(4) I invested a lump sum in a friend’s fishery business, but he declared bankruptcy overnight, and I lost the entire investment. This friend came from a well-off family but was still unsettled in any profession. Along with another friend, I decided to help him and invest in his fishery business. Within a year, he shut down the business, claiming that the yields were low and the prices of the fish were too low.
(5) I spent lavishly during my marriage due to peer pressure, spending heavily on many unnecessary things.
(6) Coming to the equity investments, I opened Demat account in 2019, did some YT courses and made sporadic investment in some random stocks with minor gains or losses. Never drawn towards to FNO but applied to IPOs in initial days and got stuck with some for years.
I was holding lumpsum with me during the corona crash and wanted to invest if market falls further down from 7500 which never materialized. I was just waiting and waiting for the correction and missed the bull run for next 18 months.
In late 2020, during the pandemic, I decided to return to India permanently to take care of my father due to his health condition. I took a six-month career break. During this time, I discovered a couple of Telugu YouTube channels focused on financial literacy. Intrigued by the concepts, I began reading and learning more. Along the way, I came across Subra’s YouTube channel and Pattu Sir’s Freefincal website, which felt like a gold mine to me. Slowly, I began to realise the financial mistakes I had made.
Course Correction
I consulted a financial advisor to evaluate my financial situation, and with their guidance, I took the following steps to correct my financial path:
(1) I acquired a term insurance policy with a coverage of 1 crore.
(2) I secured health insurance by opting for a family floater plan with a base coverage of 10 lakhs and a 25 lakh super top-up plan.
(2a). My corporate insurance provides coverage of 5 lakhs, which includes my wife, son, father, and me.
(2b). My father is also covered under my brother’s insurance plan, as he is a government employee.
(3) I had a New Jeevan Anand LIC policy with a sum assured of 5 lakhs. Despite only receiving 30-40% of the money back, I decided to surrender the policy as I didn’t want to continue paying premiums for another 10 years and wanted to simplify my investments.
(3a). I decided to keep my father’s policy without paying the premiums as the insured amount was not significant.
(4) I recovered some of the money I had lent out and invested it in PPFAS CHF and DAAA funds as an emergency fund.
(5) Tired of waiting for market corrections from 2020 march, I started investing through SIPs from late 2021. I wanted a simple and easy-to-track approach, so I chose UTI Nifty and Next Fifty index funds along with PPFAS Flexi Cap for my SIPs. I also have some direct stocks (mostly large caps), which I plan to consolidate in the future.
(6) As part of my goal-based investing strategy, I allocated index funds for retirement, flexi cap for my son’s education, and real estate for my future home buying plans.
Assets Allocation
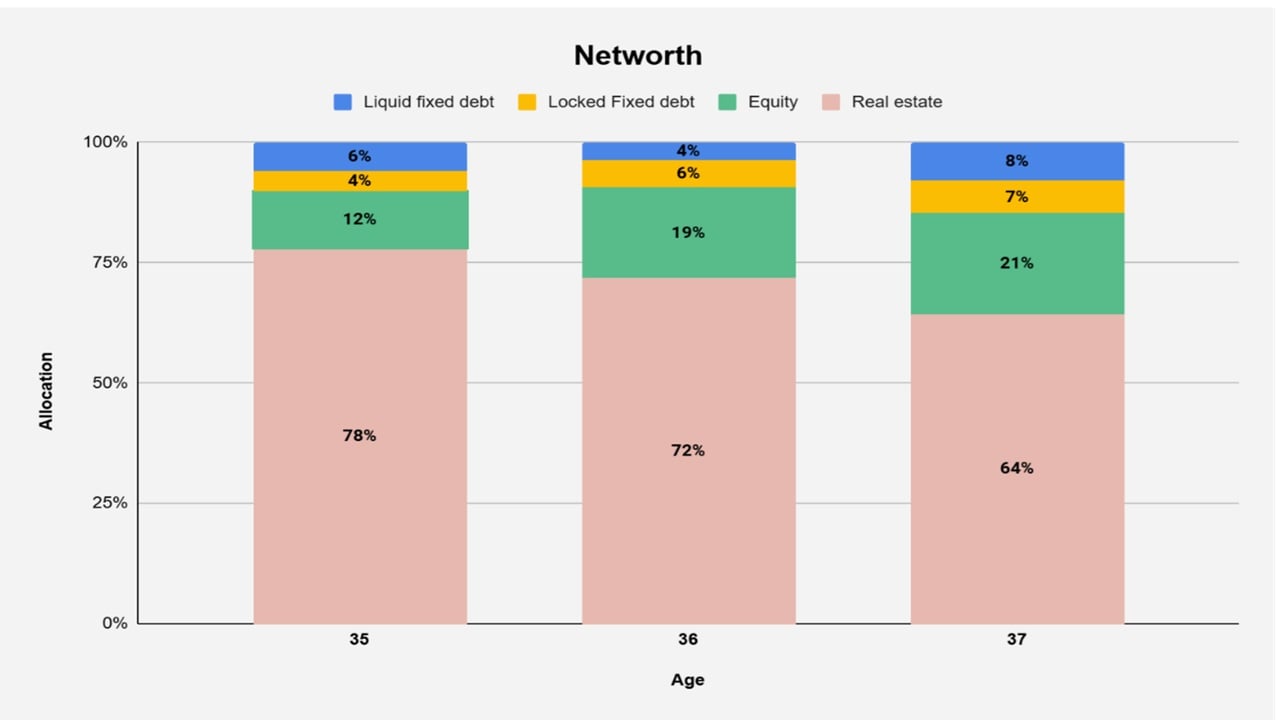
In the liquid debt segment, I invested in the PPFAS DAAA fund, and for fixed debt, along with my EPF, I have funds in the PPF accounts of my wife and son.
The next step is that a significant portion of my net worth is still tied up in illiquid real estate. My plan is to gradually shift funds from real estate to equity over the coming years.
I haven’t included the lent money in my net worth. As and if I receive these funds, I plan to move them into equity.
My retirement corpus is currently 6 times my annual expenses. Since this article is already quite lengthy, I’ve decided to discuss the detailed breakdown of my asset allocation in the next audit.
Conclusion: In his renowned book Antifragile, author Nassim Nicholas Taleb describes three responses to uncertainty: fragile, resilient, and antifragile. Fragile refers to being vulnerable, resilient means withstanding challenges, and antifragile means the ability to grow stronger in the face of adversity.
I have managed to evolve from being fragile to resilient, and the journey toward becoming antifragile has just begun.
Reader stories published earlier:
As regular readers may know, we publish a personal financial audit each December – this is the 2023 edition: Portfolio Audit 2023: The Annual Review of My Goal-Based Investments. We asked regular readers to share how they review their investments and track financial goals.
- First audit: How Suhas tracks his MF investments and reviews financial goals.
- Second audit: How Avadhoot Joshi evaluates his investment portfolio.
- Third audit: How a single mom is on track to financial freedom
- Fourth audit: How Gowtham started goal-based investing & took control of his money
- Fifth audit: Why my financial independence & early retirement plans were postponed by four years
- Sixth audit: How Abhisek funded his marriage & is on track to financial freedom.
- Seventh audit: How Rohit’s early struggles defined his investment journey
- Eighth audit: Why my investments are still on track despite job loss and lower income.
- Ninth audit: How a retirement planning calculation scared me to take action
- Tenth audit: I made several investment mistakes but have turned my life around.
- Eleventh audit: My net worth doubled in the last financial year, thanks to patient investing!
- Update: How I achieved investing nirvana.
- Twelveth audit: My financial journey: from novice to goal-based investor.
- Thirteenth audit: My journey: from a negative net worth to goal-based investing.
- Fourteenth audit: From Fixed Deposits to Goal-based investing in MFs.
- Fifteenth audit: My 10-year financial journey – mistakes made and lessons learnt.
- Sixteenth audit (part 1): How I achieved financial independence without mutual funds or stocks.
- Sixteenth audit (part 2): Lessons from my financial independence journey and future investment plans.
- Seventeenth audit: How I plan to achieve financial independence and move to my native place
- Eighteenth audit: I used the current bull run to reduce my mutual funds from 14 to 4!
- Nineteenth audit: How a conservative investor created his financial plan
- Twentieth audit: I plan to achieve financial independence by 46; this is my master plan
- Twenty-first audit: I have made many investment mistakes but am on course to financial independence by 45.
- Twenty-second audit: I felt worthless six years ago but have achieved financial stability today
- Twenty-third audit: My financial journey was directionless until age 40: this is how I made up for lost time
- Twenty-fourth audit: Why I increased equity MF investments by 275% and reduced PPF contributions.
- Twenty-fifth audit: How I track financial goals without worrying about returns
- Twenty-sixth audit: I am 24 and started investing 1Y ago, but what am I investing for?
- Twenty-seventh audit: How we plan to achieve a retirement corpus 50 times our annual expenses.
- Twenty-eighth audit: I thought equity investing was a gamble, but now I aim to hold 60% equity for retirement
- Twenty-ninth audit: My journey: From 5 lakhs in debt to building a corpus worth six years in retirement
- Thirtieth audit: My investment journey: From random purchases to a goal-based portfolio
- Thirty-first audit: My investment journey: from product-driven to process-driven
- Thirty-second audit: How a young couple is trying to balance travelling and investing
- Thirty-third audit: My journey: From Rs. 30 bank balance to financial independence
- Thirty-fourth audit: Our journey: From scratch to a net worth of 18 times annual expenses.
- Thirty-fifth audit: From a net worth of Rs. 6000 to auto-pilot goal-based investing
- Thirty-sixth audit: How I retired from corporate bondage at 46, two years ago!
- Thirty-seventh audit: How I learnt to keep it simple and build a net worth 19 times my annual expenses
- Thirty-eighth audit: How Abhineeth plans to achieve financial independence and build a house.
- Thirty-ninth audit: How Sahil plans to achieve financial independence by efficient tracking
- Fortieth audit: My Journey to a Ten Crore Portfolio
- Forty-first audit: Burdened with debt for several years, I am now aggressively investing in equity
- Forty-second audit: From Engineer to Librarian after Financial Independence and Early Retirement (FIRE)
- Forty-third audit: I lost six months’ income in F&O and ditched it for systematic investing
- Forty-fourth audit: My retirement plan to handle the harsh realities of the IT industry
- Forty-fifth audit: My investment journey: mistakes, 10 years of MF investing and recovery
- Forty-sixth audit: My MF portfolio is worth six crores despite multiple mistakes
- Forty-seventh audit: Saving, Investing, and Running Marathons: My 25-year Journey to Financial Independence
- Forty-eighth audit: Never Too Late to Start: How I Became Financially Savvy at 40
- Forty-ninth audit: My Investment Journey to a net worth 29 times my annual expenses
- Fiftieth audit: How I audit my portfolio without tracking returns
- Fifty-first audit: Financial Lessons Learned During and After a PhD
- Fifty-second audit: Investment & Financial journey of a 23 year old
- Fifty-third audit: The system I use to draw income and spend after retirement securely
- Fifty-fourth audit: From Start-Up Employee to Millionaire: A Success Story of Resilience and Smart Investing
- Fifty-fifth audit: 25-Year-Old Software Engineer’s Investment Journey: From Stocks to Mutual Funds and Beyond
- Fifty-sixth audit: Crossing the Million Mark: Our Journey to the First Crore
- Fifty-seventh audit: Navigating Market Volatility: How an IT Professional Transformed His Investment Approach for Retirement
- Fifty-eighth audit: How Sahil achieved a 10X retirement corpus by efficient portfolio tracking
- FIfty-ninth audit: How I achieved financial freedom by 45 without onsite assignments or ESOPs
- Sixtieth audit: Building Wealth on a Government Salary: Lessons Learned
- Sixty first audit: Minimalism, Index Funds, and Staying Calm: My Investing Journey at 28
These published audits have had a compounding effect on readers. If you would like to contribute to the DIY community in this manner, send your audits to freefincal AT Gmail. They could be published anonymously if you so desire.