Avadhoot reviews his investment portfolios in his 3rd audit for freefincal. His first two audits are linked below.
About this series: I am grateful to readers for sharing intimate details about their financial lives for the benefit of readers. Some of the previous editions are linked at the bottom of this article. You can also access the full reader story archive.
Opinions published in reader stories need not represent the views of freefincal or its editors. We must appreciate multiple solutions to the money management puzzle and empathise with diverse views. Articles are typically not checked for grammar unless necessary to convey the right meaning and preserve the tone and emotions of the writers.
If you would like to contribute to the DIY community in this manner, send your audits to freefincal AT Gmail dot com. They can be published anonymously if you so desire.
Please note: We welcome such articles from young earners who have just started investing. See, for example, this piece by a 29-year-old: How I track financial goals without worrying about returns. We have also started a new “mutual fund success stories” series. This is the first edition: How mutual funds helped me reach financial independence.
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
Hello friends! This is Avadhoot Joshi. I took my first Personal Finance Audit for 2020, followed by a second one in 2021, inspired by Pattabiraman Sir. Unfortunately, I didn’t publish my next financial audit in 2022 due to laziness.
- How Avadhoot Joshi evaluates his investment portfolio.
- Why I redeemed from EPF to invest in Equity MFs.
So, here is my fourth Personal Finance Audit for 2023 with much gratitude to Pattabiraman Sir for giving me this opportunity—special thanks to Ashal Jauhari Sir (Ashal is the owner of Facebook group Asan Ideas for Wealth or AIFW), Pattabiraman Sir and the AIFW community for shaping my financial journey.
Let’s start with the usual and favourite question – “ARE THE BASICS COVERED?”
- TERM INSURANCE – DONE. With Max Life Insurance. Why? – Premium was the lowest compared to others.
- HEALTH INSURANCE – As I am a PSU employee, cashless In-Patient health facilities in some reputed hospitals around the posting location are provided. Other hospital expenses (inpatient and outpatient treatment) would be reimbursed after the claim (non-medical deductions and TDS). I am currently comfortable with this. I have not yet opted for separate Personal Health Insurance. Maybe I will also opt for a separate cover, depending on developments.
- EMERGENCY FUND – The current emergency fund equals four months’ expenses.
- 36% Parag Parikh Conservative Hybrid Fund Direct-Growth and the rest in a savings account.
FINANCIAL GOALS – Here comes the audit’s next and most important part.
1) Retirement (Officially 24 years away) – I am 36. Wife is 31 years old homemaker. Since the beginning, my retirement portfolio has been debt-heavy for two reasons – 1. Being in PSU, hefty PF contributions from self and employer. 2. I started investing in equity very late – in 2018, i.e., after almost six years of employment.
I must invest as much as possible into the portfolio’s equity portion to catch up and need not bother about asset allocation until my Equity portion grows to at least 50% of my total retirement corpus.
EPFO allowed me to redeem EPF during this COVID Period for two years (2020 & 2021). I used that opportunity to increase my manual SIP in equity to push equity allocation north somehow. The change in asset allocation since April 2020 is shown below.
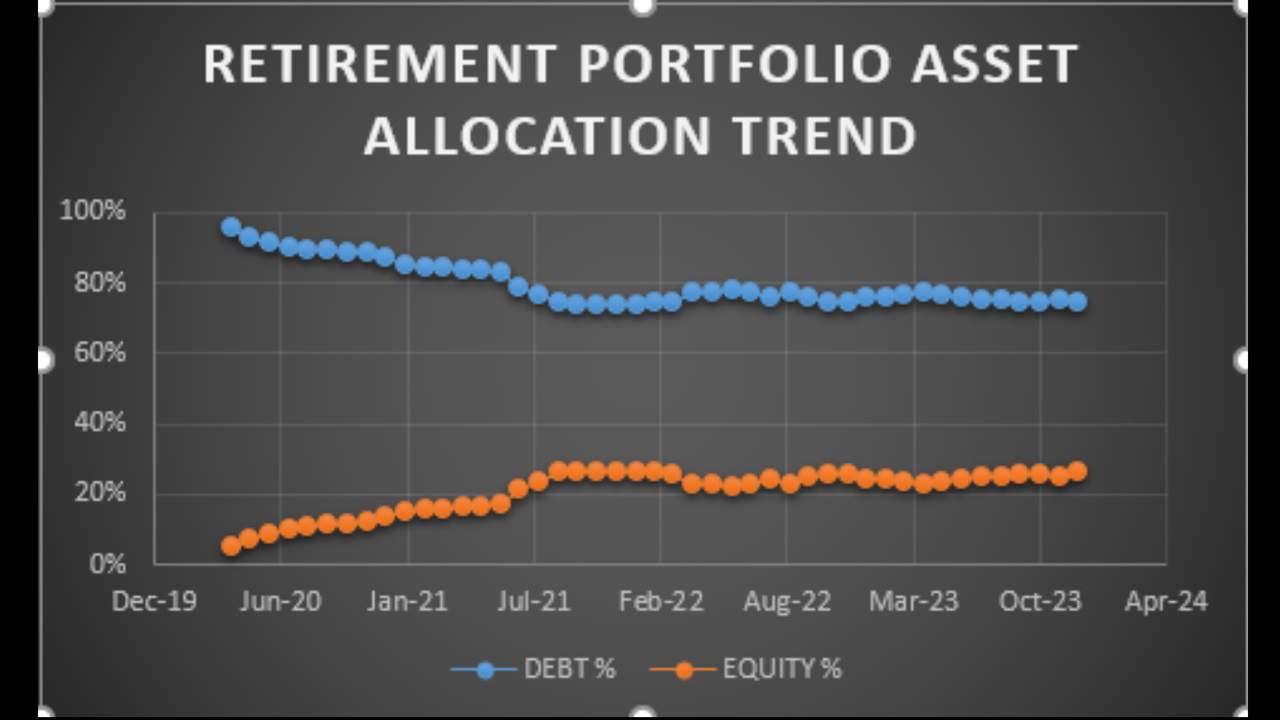
Debt Part of Retirement Portfolio – EPF
Equity Part of Retirement Portfolio – UTI Nifty Index Fund (Direct-Growth) – manual SIP every month.
The Asset Allocation is 26% Nifty 50, and the rest is in EPF.
The current Retirement Corpus is equivalent to 6.5 times the current yearly expenses (Expenses likely to be continued after retirement are considered), i.e. 6.5X. During the last year, a retirement corpus equivalent to 2.5 years of expenses was added, out of which a retirement corpus equivalent to 1 year was added through investments and a balance was added through returns. One thing to remember is that “X” is not constant but changes every year depending on inflation and lifestyle upgradation.
Trivia – Equity portion XIRR is 17.5% (Manual SIP since Dec 2018)
2) Kid’s Graduation
We are blessed with two boys. The first son is 6.5 years old, and the second is two years old. So, the investment planning is modified accordingly.
I started investing in the education corpus when the first son was 1.5 years old (November 2018) with 100% Equity Allocation. The plan was to reduce equity allocation by 6.25% yearly so that when he was ready to graduate, all the corpus would be in debt instrument. After the birth of my second son, I have decided to combine the graduation of both kids as a single financial goal.
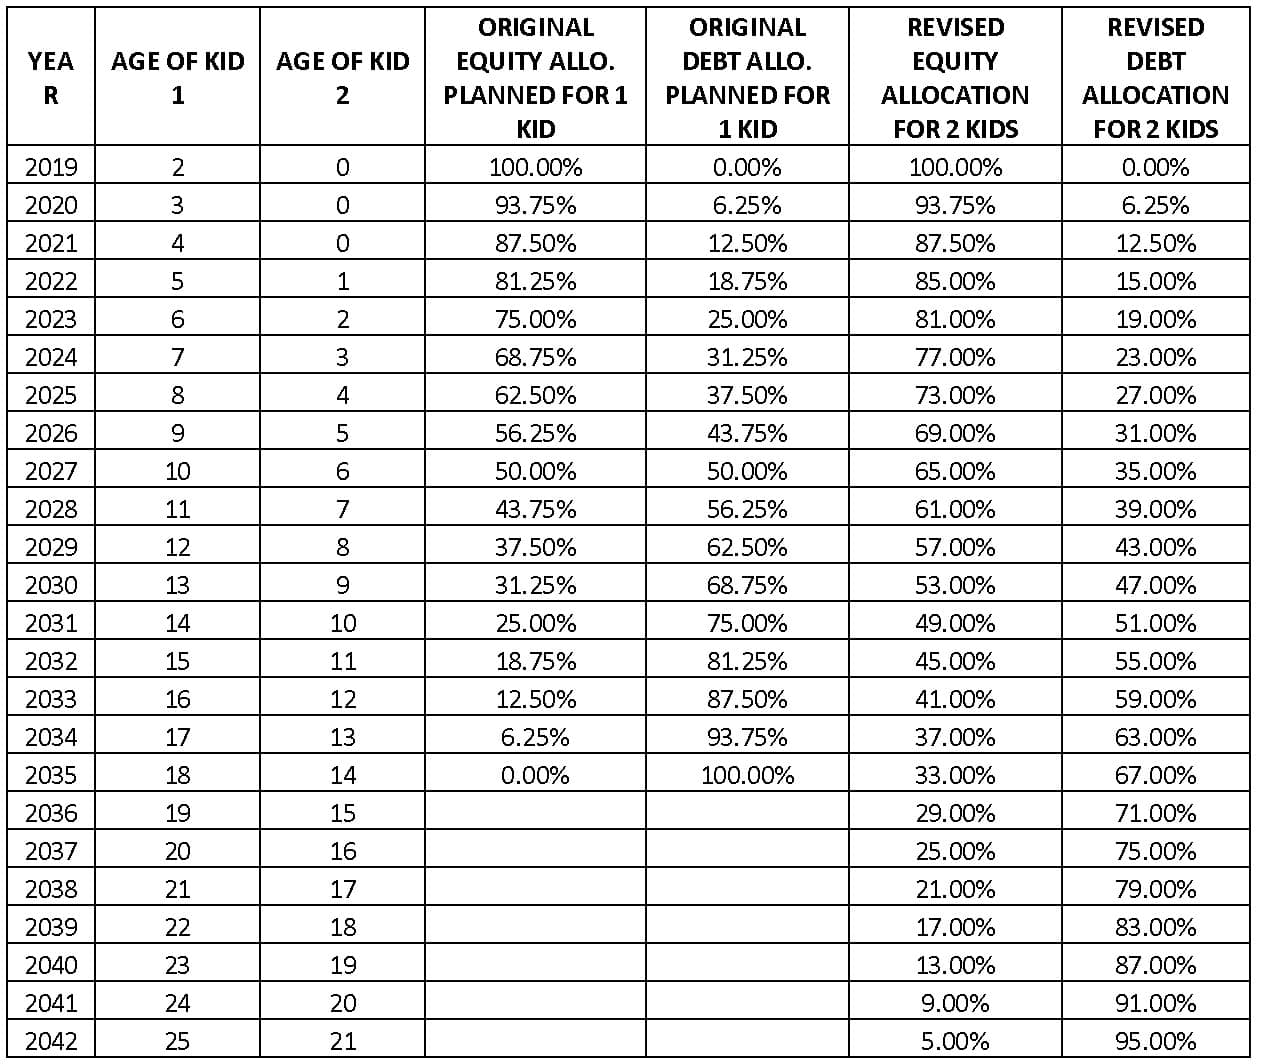
I don’t know how this plan will pan out in future. But since time is on our side, I am taking a leap of faith. The withdrawal will start in 2035 & will go on until the graduation of the second son.
Returns expectations considered while doing the investment plan – Equity 10% & Debt 6%.
The growth of the Kids’ Education Portfolio until now is shown below.
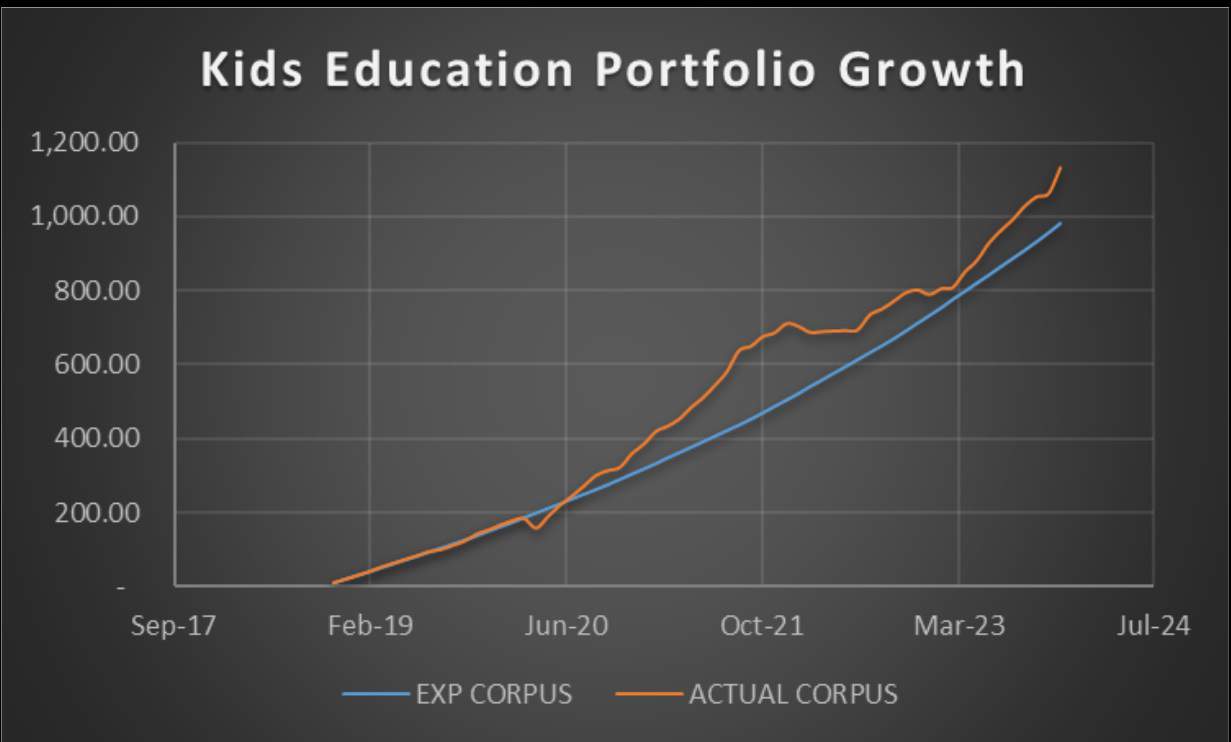
Since the investment journey is in the initial stage, asset allocation is handled by adjustments in every month’s manual SIP in the Equity/Debt part. So, until now, rebalancing is not done as such.
Debt Part of Kids Education Portfolio – PPF (16%) & ICICI Gilt Fund Direct-Growth (4%). ICICI Gilt Fund is added for rebalancing in future, considering the illiquidity of PPF.
Equity Part of Kids Education Portfolio – Parag Parikh Flexi Cap Fund Direct-Growth (80%)
Trivia – The XIRR of Parag Parikh Flexi Cap Fund is 25.1% & and the XIRR of ICICI Gilt Fund is 7.1%.
ASSETS- Since all assets are linked to a goal, it is straightforward to keep track. The current asset allocation is 63% debt and the rest in equity.
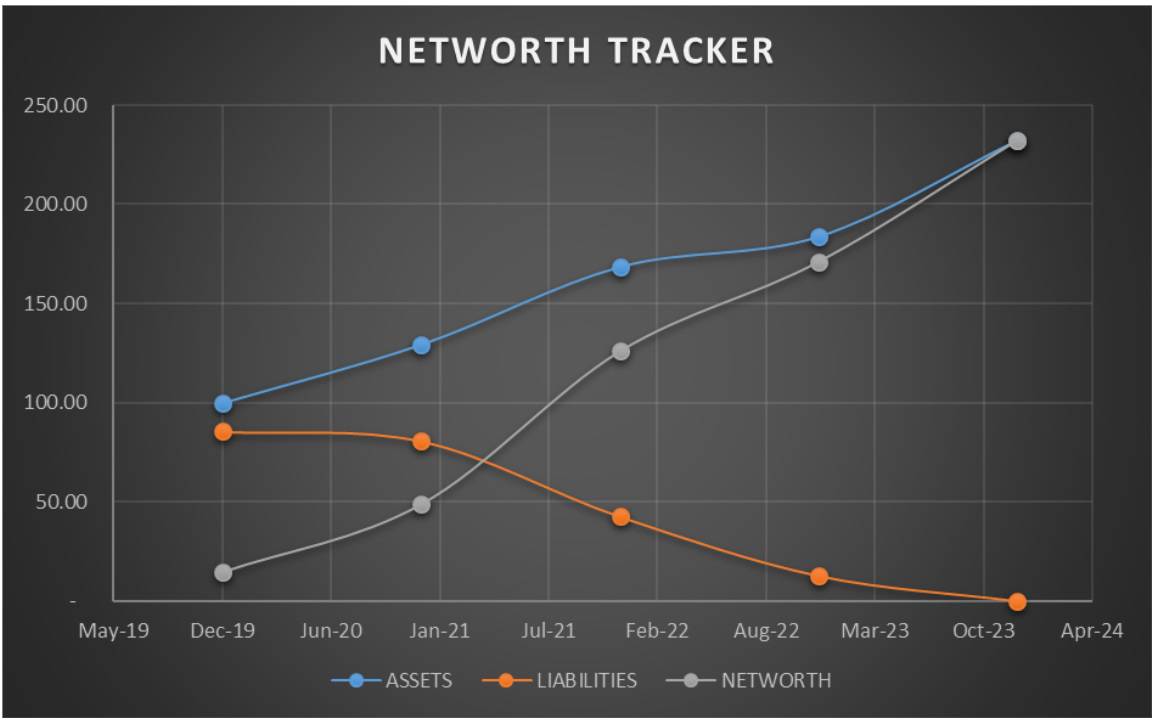
LIABILITIES – We have had only one Loan, i.e., a Home Loan, since 2017. During the 2020 audit, I had planned to close it by 2027 with increased EMI. Due to some extra cash flow, we could prepay some of the amount in 2021 and plan to close it by 2025. We are glad to announce that we have closed the home loan and become debt-free this month.
The Y-o-Y changes in Assets, Liabilities and Net-worth are shown below.
PLAN FOR 2024:
- To increase the emergency fund from the current four months’ expenses to 6 months’ expenses.
- To improve the equity portion in the retirement portfolio to 30% from the current 26%.
- To add retirement corpus equivalent to at least one year of expenses through investing alone.
- To continue investment for Kids’ education as per plan.
Thank you.
Reader stories published earlier:
As regular readers may know, we publish a personal financial audit each December – this is the 2022 edition: Portfolio Audit 2022: The Annual Review of My Goal-based Investments. We asked regular readers to share how they review their investments and track financial goals.
- First audit: How Suhas tracks his MF investments and reviews financial goals.
- Second audit: How Avadhoot Joshi evaluates his investment portfolio.
- Third audit: How a single mom is on track to financial freedom
- Fourth audit: How Gowtham started goal-based investing & took control of his money
- Fifth audit: Why my financial independence & early retirement plans were postponed by four years
- Sixth audit: How Abhisek funded his marriage & is on track to financial freedom.
- Seventh audit: How Rohit’s early struggles defined his investment journey
- Eighth audit: Why my investments are still on track despite job loss and lower income.
- Ninth audit: How a retirement planning calculation scared me to take action
- Tenth audit: I made several investment mistakes but have turned my life around.
- Eleventh audit: My net worth doubled in the last financial year, thanks to patient investing!
- Update: How I achieved investing nirvana.
- Twelveth audit: My financial journey: from novice to goal-based investor.
- Thirteenth audit: My journey: from a negative net worth to goal-based investing.
- Fourteenth audit: From Fixed Deposits to Goal-based investing in MFs.
- Fifteenth audit: My 10-year financial journey – mistakes made and lessons learnt.
- Sixteenth audit (part 1): How I achieved financial independence without mutual funds or stocks.
- Sixteenth audit (part 2): Lessons from my financial independence journey and future investment plans.
- Seventeenth audit: How I plan to achieve financial independence and move to my native place
- Eighteenth audit: I used the current bull run to reduce my mutual funds from 14 to 4!
- Nineteenth audit: How a conservative investor created his financial plan
- Twentieth audit: I plan to achieve financial independence by 46; this is my master plan
- Twenty-first audit: I have made many investment mistakes but am on course to financial independence by 45.
- Twenty-second audit: I felt worthless six years ago but have achieved financial stability today
- Twenty-third audit: My financial journey was directionless until age 40: this is how I made up for lost time
- Twenty-fourth audit: Why I increased equity MF investments by 275% and reduced PPF contributions.
- Twenty-fifth audit: How I track financial goals without worrying about returns
- Twenty-sixth audit: I am 24 and started investing 1Y ago, but what am I investing for?
- Twenty-seventh audit: How we plan to achieve a retirement corpus 50 times our annual expenses.
- Twenty-eighth audit: I thought equity investing was a gamble, but now I aim to hold 60% equity for retirement
- Twenty-ninth audit: My journey: From 5 lakhs in debt to building a corpus worth six years in retirement
- Thirtieth audit: My investment journey: From random purchases to a goal-based portfolio
- Thirty-first audit: My investment journey: from product-driven to process-driven
- Thirty-second audit: How a young couple is trying to balance travelling and investing
- Thirty-third audit: My journey: From Rs. 30 bank balance to financial independence
- Thirty-fourth audit: Our journey: From scratch to a net worth of 18 times annual expenses.
- Thirty-fifth audit: From a net worth of Rs. 6000 to auto-pilot goal-based investing
- Thirty-sixth audit: How I retired from corporate bondage at 46, two years ago!
- Thirty-seventh audit: How I learnt to keep it simple and build a net worth 19 times my annual expenses
- Thirty-eighth audit: How Abhineeth plans to achieve financial independence and build a house.
- Thirty-ninth audit: How Sahil plans to achieve financial independence by efficient tracking
- Fortieth audit: My Journey to a Ten Crore Portfolio
- Forty-first audit: Burdened with debt for several years, I am now aggressively investing in equity
- Forty-second audit: From Engineer to Librarian after Financial Independence and Early Retirement (FIRE)
- Forty-third audit: I lost six months’ income in F&O and ditched it for systematic investing
- Forty-fourth audit: My retirement plan to handle the harsh realities of the IT industry
- Forty-fifth audit: My investment journey: mistakes, 10 years of MF investing and recovery
- Forty-sixth audit: My MF portfolio is worth six crores despite multiple mistakes
- Forty-seventh audit: Saving, Investing, and Running Marathons: My 25-year Journey to Financial Independence
- Forty-eighth audit: Never Too Late to Start: How I Became Financially Savvy at 40
These published audits have had a compounding effect on readers. If you would like to contribute to the DIY community in this manner, send your audits to freefincal AT Gmail. They could be published anonymously if you so desire.